Pierre Heurtebize: SaaS Valuations, Exit Planning and the M&A Market in 2021 [SDI]
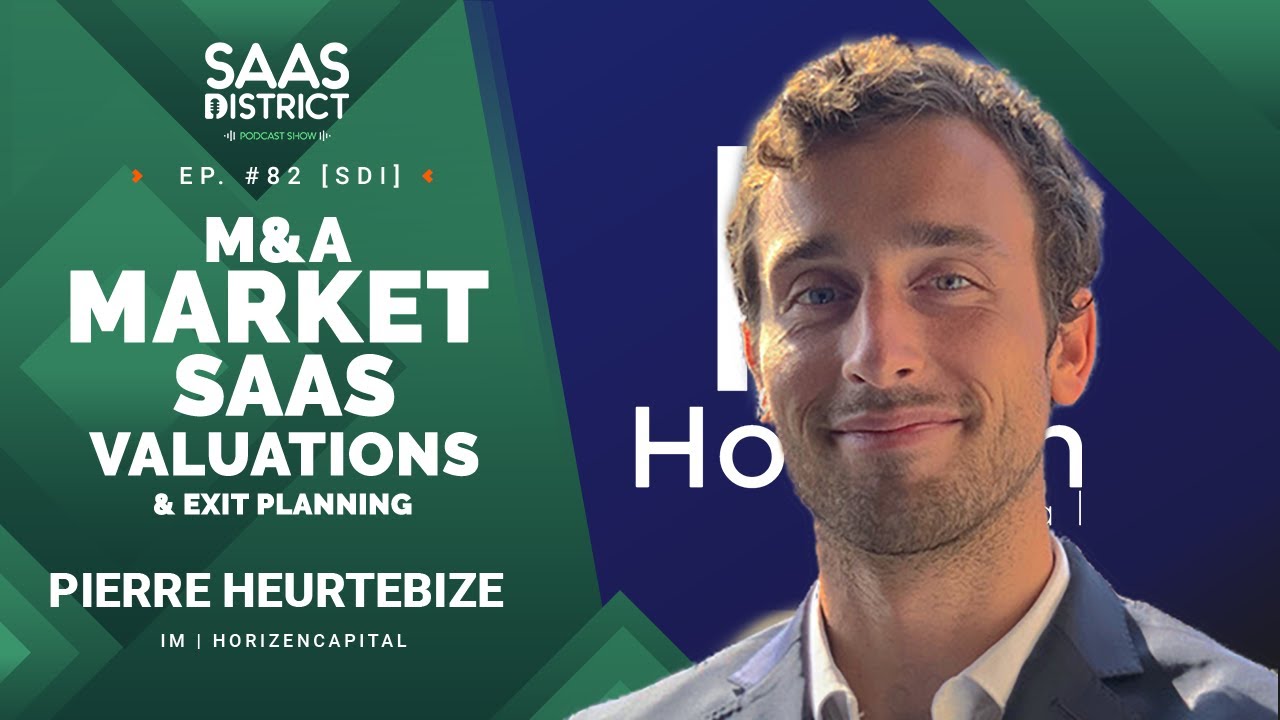
Pierre-Alexandre Heurtebise of Horizon Capital breaks down SaaS valuations and M&A in 2021. Financial buyers and strategic buyers value deals differently. Realistic multiples: 1-3x ARR for sub-$1M revenue, 3-5x for $1M-$5M with solid growth and low churn. Most deals take 7-8 months.
Chapters
Hello, hello everyone. This is your host, Akeel Jabbar, and welcome back to another episode of SaaS District. In today's episode, we'll be talking about SaaS valuations, exit planning, and the M&A market in 2021. Today we have our guest Pierre Hurtubise joining us once again. It's the first time he's actually joined. We've had a guest come on the show for the second time, and he's actually here live with us here in Guadalajara. So we thought we'd record this episode and share some insights on what's been happening, what's going on at Horizon Capital, and share what our kind of predictions are going into 2021. So welcome, Pierre. Glad to have you back on the show.
Yeah, very glad to be here as well.
Yeah, awesome.
Been looking forward to come.
Yeah, enjoying your time here in Mexico so far?
Yeah, it's pretty nice. Yeah, and the weather is cool. Looking back at Europe where everything is Basically not going very well. Am I quite happy to be here and finally meet?
Yeah, yeah, you got here at a good time. So we're going to start talking about multiples, valuations. I think that's a question a lot of founders have. They're looking to exit their company, there's always that picture in their mind that they always think 10x is the number. I don't know where that number came from, but they always think it's 10x of the revenue of what they can sell their business. But before getting into the actual weeds of the multiples of what SaaS founders can expect, In terms of the exit valuation, I want to clarify for audience, what are the differences between the different profiles of buyers, right? You have the people who are financial buyers and then you have the strategic buyers. What is the difference between them, if you can explain for people?
Yeah, sure. So basically the 2 different categories that we see, as you say, is financial buyers on one side, so generally investors, and strategic buyers. The main difference between the 2 is the financial buyers are going to look at the company mostly based on the financial and cash flows they can expect from the company on a standalone basis. Whereas on the other side, the strategic buyers have their own agenda, have their own products, and they're more looking for synergies, right? They're looking to acquire potentially technologies that will help them grow faster or additional revenue, and that they will be able to incorporate into their existing customer base and immediately increase their revenue and revenue per customer. So generally what you see is financial buyers will pay a lower multiple So in our case, Horizon would be considered obviously a financial buyer.
Who are some examples? Be more specific. What is a strategic buyer? I guess, how does that look like when people are looking? Is that like the Googles and the Amazons? Is that what you're talking about?
So those would be the bigger ones. You can see that Google doing a lot of acquisition, especially trying to integrate startups. They also pay a premium because they know that they're going to be able to integrate them. they don't want those startups to become competitors. So that's also a strategy to stay on top of their game. If you look at maybe smaller companies, you can have a company like HubSpot, which is still fairly big and which will try to integrate other services that make a lot of sense. If you look at a CRM company, for instance, it could make a lot of sense for them to partner or to merge with a company that offers emailing. So emailing sequences, outreach, sales outreach, or help with the sales process. And by combining those companies, then you could immediately first benefit from economy of scales for sure. But also you're getting some values along the value chain, right?
Right.
Because now you're getting customers that use your CRM and pay you for that, but they also use your other service. And your existing customers are very likely going to sign up to the new companies and products that you're integrating. So that makes a lot of sense.
That makes a lot of sense. In terms of the market, I want to talk a little bit more about the market because as we've seen in 2021, investors had a shift in their perspective of what they've become interested in. You have things like hospitality, retail, there's a lot of other stuff like that that maybe have lost a lot of interest for investors and the market has become even more and more important and people are looking at that as a major factor.
E-commerce has been big.
What are some other SaaS businesses would you say are trending right now and hot in the current market?
Yeah, so basically markets, especially in the investing community, has always been one of the top 3 criteria to invest into a company with management generally. So the things that are trending right now on the SaaS market, I would say AI, so artificial intelligence. It was trending before the COVID incident and it's still trending very high right now. And I personally am a big believer of the AI, even though you need to be careful about what you can call AI and what is just a simple algorithm. There is a huge trend on everything related to remote working as well that we see, which makes a lot of sense, which is an interesting trend, I think, because fairly people think we will move towards a society that works remotely. But more and more after like a year of working remotely, you have a fair bit of the companies that realize that they also have a loss of productivity. So baseline is remote working is not for everyone, at least not on a 100% basis. But still trending on those type of product and SaaS product that will help you organize your workforce, manage a remote workforce, or even communicate within an organization. All things that were actually very important before COVID But the whole situation made everyone more aware of that. One of the things which is obviously trending is going to— sorry, has been everything related to virtual events.
Mm-hmm.
You can think of Hopin. I think we've scarcely seen a company grow that fast. It's crazy. I think they've been recruiting over a few hundred people over a couple of months. Well, it's been crazy.
I guess with the remote work, do you anticipate that this is just a short-term trend for maybe 2021 and then it kind of dips back after that?
So, I reckon people will see some values attending virtual events and working remotely. My guess is you may have a drawback because once things go back to normal, people will be so happy to actually meet in person again that you may have a drawback. But the thing is, Based on the latest analysis that I've seen, experts don't actually expect the situation to go back to fully normal before 2024.
2024, okay.
And on top of that, I feel like the benefit of having remote webinars or remote conferences is it makes it so easier to slide it into your busy agenda. And from an economical perspective, I'm pretty sure people know that may make a fair bit of money, right? Because then you don't have to host it in a huge location and pay the rent for it. You can have unlimited attendees. So a lot of things that make economical sense and which I think would be one of the reasons why it's going to stick.
Yeah, makes sense. Well, things like Clubhouse are trending right now as well. So yeah, people love it. They're loving it.
By the way, if anyone has an invite, I would be keen to do it.
Pierre's still waiting for his invite. So if anybody's listening has one, send it our way. He's excited to jump on. Yeah, I would love to. Um, so, you know, interesting, speaking about 2021, you know, it's weird. In, in the last quarter of 2020, we saw kind of like a drop of people wanting to get into conversations. And then, you know, January hits and we start getting flooded with people, uh, you know, in the M&A landscape, people are starting to, you know, wanting to sell their business, they're looking to raise money, they're, they're looking to talk, they're, they're super active. Uh, what's your take on why that is and how do you anticipate like the remainder of the year will look like?
Yeah.
So, that may be only a personal assumption, right? I feel like people started to postpone their sale due to COVID. I mean, you had 2 categories. You have the people benefiting from COVID and seeing 300% growth thanks to that and seeing the momentum and trying to push for a sale. But you also have a lot of people that felt like they would not get such a good deal due to COVID and potentially postpone. But then I guess you have the psychological point of moving to a new year and realizing that COVID is here to stay and that people need to get back to business. They can't postpone forever, right? So I feel like after the Christmas period, people kind of went into reset mode, looking back at 2020 and revise their objective for 2021 and feel like, all right, We need to move forward now. If we want to sell that company and move on to another project, we need to do it now.
Yeah, it makes sense. I feel like people felt like January 1st, 2021, now things were going to go back to normal all of a sudden. And then they realized, okay, I just have to face this reality and it's time to make some decisions and not wait for that moment that things will open up and be normal.
Right?
True.
And there is also another huge criteria, I think, is the US election.
That's another point. Yeah.
So, so much uncertainty. Yeah. I would understand why no one wanted to have like proper conversation in December with all this uncertainty going on. So now that Biden has been elected, I guess that has really helped also release the pressure for a lot of people.
Yeah, makes sense. And then from that psychological perspective in how people are thinking right now and ready to take action of selling their company, whether it's Because it's trending upwards or it's on the downtrend and they just want to move on. How do you think that'll impact valuations going into 2021? Do you see any difference in changes?
So, if you had asked me 6 months ago or a year ago, I would have answered that I would have expected valuation to decrease simply because valuation is supposed to include and be dependent on risk, right?
Yeah.
So right now we're in a higher risk situation due to COVID. So mathematically, in theory, valuation should have decreased. The reality is, I've read several stuff on the subject from other brokers and looking at actual transactions happening, it appears that valuation hasn't moved. Interestingly. It's still the same. Part of the reason I would say is I had a few conversations now with buyers who in a sense didn't want to take advantage of COVID to offer a lower valuation and didn't want to be seen as taking advantage of it. Generally though, what they would do is they would include more earnout into their offer. And because they also know that generally when they're trying to buy a company, they're also trying to have a good relationship with the seller because a lot of times the seller stays within the company and still works with them and they need him or her for the transition. So that made sense to not try to be seen as super greedy and instead finding a good deal to make everyone happy.
It makes sense. And coming back to the actual theme of this conversation, which is around the valuations of SaaS companies, What are multiples of some of the offers and deals that we're seeing kind of go out there in the market? And what can SaaS founders expect if they're looking to sell their companies this year? So first thing, it's going to stay the flat, it's going to stay the same this year, 2021, and they're looking to sell, what can they expect?
Yeah, so that's a huge question. And believe me, there's a huge discrepancy in the type of offers we see. And that's a good thing. We're working also in M&A. You can see proper offers from different buyers and on the same products, you can have an offer at one 1x ARR and 8x ARR. So the type of discrepancy is crazy and will generally depend on the type of buyers and how they look at your product, whether they have synergy or not. So if I was going to give a wide range, I would say for SaaS companies below $1 million in ARR growing at less than 20% year on year, you would expect something around 1 to 3x ARR. If you start moving up in terms of size, going more into the $1 million EBITDA range, still growing at 10-20%, well, you could start looking at 3 to 5 times revenue, especially if the product is good, if the churn rate is fairly low. However, because you were mentioning the 10 times ARR valuation, so this is a trend that I still struggle to understand. And I think a big part of it is all the press around the huge SaaS and super successful publicly listed companies selling for these crazy multiples.
Mm-hmm.
However, people may have struggled to differentiate those huge, crazy valuation companies with more regular ones. And I was looking at a list of 200 listed SaaS companies from an article basically where the title was, oh, the median ARR multiple is still over 12 or 13%. I'm like, all right, cool. And I was looking at the data row by row. And if you focus on all the companies that have less than $1 billion in ARR, all those ones were trading around 3 to 6 times, maybe 7 times. But all the huge ones, the Salesforce, the HubSpot one that trade at 15, 20, 25 times ARR, they're the ones really driving the average. So bottom line is, if you have a company that is growing at 200% year on year and you have almost no churn, yeah, sure, you can attract a super good valuation. If you're growing at less than 50%, I would say try to be more realistic and see what the market is telling you before wanting to have this crazy valuation.
Yeah, makes perfect sense. From your perspective, what are generally the biggest red flags that we see in SaaS companies that would make you avoid structuring a deal? Or do you think you tell founders that they should work on to improve their multiples? So if I'm looking to exit My business, I'm trying to plan it and they come to you and you're like, look, these are some problems you need to work on if you want to get a proper valuation and a good deal.
So first one would be a high churn. And mostly because the whole point of and the whole value of SaaS businesses is the recurring part. By definition, if you have a high churn rate, that means that your customers are not staying. So you can't claim to have that recurring revenue in a sense, right? So high churn would definitely be my number one red flag. Other red flags which are common and not only for SaaS businesses would be a high concentration of your revenue within a few customers. If you're doing 60 or 70% of your revenue with maybe 3 customers, then as a buyer, you have a lot of risk around that, right? Because if one of those customers leaves, you're taking a direct hit. And on top of that, you can Generally, never knows the real relationship that these buyers have with the seller. So they may have a close relationship, and they may be there only because of that special relationship.
Right?
In terms of other red flags, I would say potentially a decrease in market as well. Right?
Yeah. A declining market.
Yeah. As we were saying, markets is generally one of the main things that investors look at. And obviously, if you're on a market which is shrinking or stable, then you have higher chances of your investment not being a good one.
What about the size? Is that generally a filter that you see, like revenue itself? Because I know some, a lot of strategics or even other buyers, right, they have a minimum threshold. They're not, they don't even look at a lot of these deals just because they're too small. What's a good, I mean, obviously you want to keep growing the company as large as possible, but at what point should So, what would you say to a founder, if they're looking to sell, like, look, I'm at this stage right now, I might be able to get a good multiple, I'm thinking of getting out, what's a number that I should start thinking about that?
So, first numbers that would come to mind as a founder, from a founder's perspective, I would say maybe $1 million in ARR. I mean, because psychologically speaking, that's $1 million. I think where you really move towards the next category of interesting private equity firms and buyers that are more competitive in a sense would be that $5 million mark. Yeah. But obviously it also depends on what type of buyers you want to sell to. Sure. Sell to.
That makes sense. I think once you hit that $1 million or so, it also kind of proves you have product-market fit, which I think lowers a lot of the risk and people are interested as well, right?
Exactly. And we'll also have some Something to do with your profitability as well.
Yeah. So speaking of profitability, I mean, that's one part of it. What are some other biggest drivers or metrics that you say are getting the highest multiples or offers on acquisitions and would get you excited or any other financial investor excited about?
So the first thing, and that has been super consistent in all the research about SaaS valuation, is the growth rate. The multiple is going to be directly correlated to how much you grow.
Right.
Small caveat though, because again, I have a lot of conversations where people don't necessarily differentiate between 2 companies of totally different size. If you're growing at 20% year on year, but you're only doing $100K in ARR, this is not an impressive growth. If you're growing at 20% when you have $5 million ARR, then we're talking. You have to also think about it from absolute value perspective.
Exactly.
Because 20% at $100K ARR, you're just bringing in $20K additional revenue each year. So, don't expect a crazy valuation multiple based on that. If you start being at $400K, $500K and growing at 20%, 30% year on year, then I would say you start being fairly attractive, right? Because you're demonstrating that you're growing and that you're on the right path.
It makes sense. And would you say there's any difference on how that's generally viewed from a strategic acquirer's perspective based on some of our M&A conversations we've had with Horizon and, you know, buyers that are interested? Would you say there's— do you see any difference in terms of what gets buyers excited about a deal from a strategic side versus how we would?
Yeah. So with the strategic buyers, it's generally harder to give a generic response simply because it really depends on their strategy and the products they are offering. Like, you could have a very niche product that doesn't interest any financial buyers. But if you find the exact strategic buyers that could totally integrate that feature and immediately make money out of it, Then that's an interesting conversation. So the main difference, if you want to differentiate strategic and financial buyers, I guess the main difference in their approach is financial buyers obviously are going to spend way more time reviewing your accounts, doing deep dive analysis of the trends, understanding your churn rates, who has been churning, how they've been churning, is there any changes in in patterns in the recent months, et cetera, et cetera. Whereas the strategic buyers, especially if they have a high interest from a strategic perspective, either due to the technology or your existing ARR, they're going to spend more time understanding your customers. Who are they? How long have they been staying? Because it gives them an indication of how good your product is and see how they can integrate those customers to their own ecosystem.
Makes sense. And then, you know, I think we had this conversation slightly just before this interview. We're talking about, you know, management having to stay on. If I'm a SaaS founder, that's a question I usually get is, if I want to sell to a strategic buyer, I'm looking to engage an M&A company to help me consult in finding a buyer, do I have to stay on? If I'm tired of this business, I want to move on, do I have to stay? Um, should I think about staying, or can I leave completely? Or what if I want to stay? What would you— how would you answer that?
My short answer would be From what I see, I think you have higher chances to find a buyer if you're committed to stay. Because first, it makes more sense for the buyers to decrease their risk. If you're staying and you still have skin in the game, that basically tells them you still believe in your product. Whereas if you're just trying to exit, you can have perfectly good reasons, right? And a lot of those reasons I understand. You want to focus on something else. focus on your family, you want to change industry, or you want to cash out on what you've built, they are all very valid reasons. However, since we're— if you see that as a game, as an M&A game, you're in a game with distortion of information.
Yeah.
So you don't have perfect information. And from a buyer perspective, they're trying to derive all the possibilities from the answer you give. And one of the possibilities that can be derived from a founder not wanting to stay or not wanting to retain any equity in the business is, well, There's something wrong somewhere. That may be a red flag. I haven't found it, but he knows about it, right? So if you're looking at not staying, you should make sure that you give them a very valid reason and that you're transparent enough for them to get comfortable with the fact that you're not staying.
Makes complete sense. Last question, Pierre. If I'm a founder, I'm looking to prep my SaaS company for an exit. What are maybe 2 to 3 or more tips that you'd suggest to them to get their pitch right and then also increase their chances of getting acquired or invested in?
Right.
You create that pitch. What are things you would tell them that they need to focus on?
Yeah.
So, so I guess to answer that, maybe I would try to mention one of the main mistakes I see when I talk to founders looking to exit or prepare a pitch deck. I think One of the number one things I discuss with them is expectation. Don't have expectations out of the roof, both in terms of valuation but also in terms of forecast. Because if you're pitching a forecast where you're going to multiply the company by 3 within the next 6 months, people will have a tendency not to take you seriously.
Yeah.
The second thing I generally see is people trying to get too technical about their product. You just have to keep in mind that if you're looking to approach investors, that may be slightly different with strategic buyers, especially if you're in a very technical industry where they know all the technical side of it. But let's take like regular financial buyers who may be aware of your industry but not necessarily a tech guy. If you just throw him a lot of information. You know, this guy is reviewing maybe 10 pitch decks a week, right? So he's not going to spend the time understanding your product. What you want to do is kind of sequence the type of information you give them and making sure you tick the boxes that they're looking for. So those boxes are going to be, all right, what do I do in 1 or 2 sentences? They need to understand the market you operate in in a short sentence. You don't need to go on and on and have like 5 paragraphs. Because also you need to keep in mind that they need to understand it for themselves, but they need to communicate with the rest of the team. And very often your pitch deck is going to be reviewed by an analyst that needs to pitch it to his investment director, that needs to pitch it to his board of directors, right?
Yeah.
So the easiest you make it for them to understand what you're doing, and the easier it's going to be for them to pitch it to other people. So remember that.
Right.
So one sentence to really clearly explain what you do. Main numbers. What are the numbers that they're going to look at? Revenue, how much you've been growing. If you're a SaaS company, what's your churn rate? What's your LTV? Explain a bit more about what market you target. So the buyer persona, how you get there. And then basically, what are the opportunities? And if you already get those information right, you can pique their interest. And if you manage to pique their interest, then you can enter in conversation. And in the idea of sequencing when you release information, once you engage in the conversation, they're going to ask for more, right?
Right.
And so you're going to provide them the information at this stage. So that's one thing. And the other thing is also potentially to structure your approach. I feel like if you have a systemic approach and a good process on how to select the right buyers and how to do the outreach, you will also greatly improve your chances to get a deal. And one thing I would say that people underestimate a lot is how much time it will take to run a formal process and get sold. Because you're going to have a lot of companies looking. And fortunately, if you manage to raise interest, you're going to have a lot of potential buyers looking at your company. But that doesn't mean they're going to buy it.
Right.
They're still going to ask questions, still going to take a lot of time. And that's generally one of the main reasons why people decide to hire M&A advisors to run that process for them. Because it just saves them a lot of time and helps them structure the process.
What's the typical timeline you think that people should expect? I mean, in general, they're looking to sell their company, how fast is that whole process?
So, again, depending on the size of the company, say if you have a company below $500K, I would say you could find a buyer who, like an individual willing to buy your company, and it could take 2 or 3 months. That could be very quick, right? If you have a company slightly bigger than that, generally— so if you're lucky and that's your first IoT and your process goes smoothly, I would say you could sell it in 4 months, right? 4 to 5 months, including the start where you're basically putting together the IAM, the pitch deck and you're preparing for it.
Yeah.
More regularly though, because you can have a lot of back and forth because the buyers you reach out to first may not be the right one and you may need to have a second outreach sequence. I think on average what we see on the market is it's not unusual for a deal to take 7 to 8 months and sometimes a bit more than that to close.
Interesting. Final question, Pierre, I guess just to wrap it up. Going into 2021, what do you expect the M&A activity to look like? Because I feel like last year there was a lot of people holding on to their cash. Do you feel that's still happening right now or do you feel buyers are ready to buy some deals right now?
So given how hot the market is, I think at least first half of 2021 we should see a fair bit of deals Because there's a lot of capital available. Investors are also getting crazy about all the hype happening at the moment, even though a lot of that hype is attracted by the financial markets and trying to go to the moon. So I would expect first half of 2021 to have a lot of deals happening. I may be more skeptical about the second half because I still think that At some point, we will suffer from the economical downturn caused by COVID. And right now, I feel like all the money which is basically lended keeps a lot of business afloat, but for how long, right? And so if at some point we enter into a downturn, that is going to make things a bit harder.
Right.
So we're just buying time, basically. It's just inevitable at what point that happens that Hopefully that cash will save us. Pierre, thank you so much for joining. I always love talking to you and catching up. If anyone's interested to sell their company, they're looking to even just get a valuation or talk about their exit strategy or planning in an early stage, how can they get in touch with you? How can they learn more about what you're doing?
So easiest way to reach out is either you can go on my LinkedIn, Pierre-Alexandre Hertebise. They can also go on the Horizon website. We do have a form they can fill up and they can have a look at those different things that we do there. They can also send me an email directly at pierre.horizoncapital.com, P-I-E-R-R-E. And any other way that they find to reach out, send me a Twitter DM, I will answer.
Okay, awesome. We'll put those in the show notes, pierre@horizoncapital.com. All right, thanks again for joining SaaS District and appreciate you jumping on.
All good.
Cool.
Thank you all for watching this episode and joining SaaS District today. Don't forget to like, subscribe, and hit the bell for future episodes where we interview top leaders in the SaaS industry. If you're a SaaS company looking to grow and unlock the true value of your business, get in touch with us at Horizon Capital and myself or one of our consultants will provide a free assessment to help you get there and hit your goals. If you have any feedback or suggestions for this podcast, please comment down below and help us improve our content for you all. Thanks again, and see you on the next one.
More from Akeel

Get a mentor as soon as possible — and make sure it’s a mentor in your space.



Keith Gillispie: Why Most New Investors Fail & How to Avoid the Common Traps #250 | SaaS District