Q & A on Rehab Loans 02 16 2023 Session
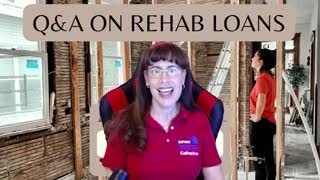
Catherine Hall (NAFAC executive director) hosts a live Q&A about rehab loans, explaining how buyers can use renovation mortgages (FHA 203(k) limited and standard, Fannie Mae HomeStyle, VA/USDA) and when to convert a purchase into a rehab loan. She contrasts home inspection reports (which grade condition relative to optimum) with the FHA Minimum Property Standards (MPS) Report (a HUD/FHA pass/fail appraisal focused on livability, soundness, and structural integrity) and describes contractor upfront payment rules for limited (up to $35,000; lenders may advance up to 50% of repair funds per HUD guidance, though many cap lower) versus standard 203(k) loans.
Chapters
Hello, hello, hello, hello, and welcome to Q and A on rehab Loans. My name is Kathryn hall, and I am excited to have you here today. We're restarting this series, and we just got it back up and running in the beginning of this month. And so every Thursday, I'm going to be here live for 30 minutes to answer your questions about rehab loans, FHA 203K, Fannie Mae, VA rehab loans at USDA, and anything that has to do with renovating a property and having the cost of that added to your mortgage. So behind me, you see a picture of a person who basically ripped off all the drywall and is down to the studs, the plaster and wood lath. This is what I used to look at all the time when I was a rehab consultant in Philadelphia, and that was the city that I cut my teeth on renovation loans for almost 30 years. And so now, as the executive director of the national association of FHA Consultants, I am a guide and a cheerleader and a support for people around the country who are wanting to use renovation loans. So now we're going to be getting started with some of the questions that I received via email. And please do not hesitate to send me a request via email. My email address is c hallafac.org that's c h A L L at N A f h a c.org and I'll be happy to answer your calls. So. And answer your questions and take them down here live as well. So one of the calls that we got, one of the questions that I got that was very exciting was the question was, I'm buying a house and the appraiser wants to see, the underwriter wants to see my home inspection report. But there's a lot of things on it that I'm afraid of. What do I do? Okay, that is a great question. So first of all, if you're buying a home and the home inspection report that you've had has a lot of issues on it, maybe that's a property you want to consider buying with a rehab loan. Almost every type of mortgage that you can be purchasing today can be converted to, to a renovation loan. The FHA 203K, the Fannie Mae home style for conventional so and the VA renovation loan. So don't think that I didn't start it as a rehab loan. I can't be. I can't use a rehab loan. That is absolutely not true. You can convert to a rehab loan at any point in the process, up till, you know, closing, I guess. Okay, so the question was, what do I do about my home inspection report? Well, there is a very powerful tool that members of the national association of FHA Consultants can provide to their customers who are getting a home inspection and don't want to share that information with their underwriter. And that's called the FHA Minimum Property Standards Report. In fact, I talked about it this morning in the monthly Rehab Consultant Skill Building Call, which was also live streamed from 8 to 9am this morning. And in that conversation, I was sharing with Rehab consultants the power of a report that is not as subjective as a home inspection, but provides the details and information that we all need to be able to provide to make sure people who are funding the loan providing us the mortgage are going to be happy with the transaction. So that's called the FHA Minimum Property Standard Report. And I'm gonna see if I can share my screen. Okay, let's see. Because we are live.
If I can share my screen.
See if I can open this up. All right, come on now. Share screens.
Ah, let's see. And let me go back. I might not be able to do that right now. I'll figure it out by the next time I'm here. I. I have done it before, so let me see if I can do that. Let me go back here and look and see if I can do this.
I don't see it. Let's see.
Let's try that button.
I'm sorry, I'm having trouble here. Technology. Sometimes it gets in the way. I was trying to share my screen and let's see if I can do that. Okay, there it is.
Okay, great camera. Let's see. It's on there. Nope, that's not going to work.
All right, so I'm not going to be able to share it. All right. I will have to share it next time. And when I do, I will make sure I have the ability to show my screen to you and I will show you the FHA Minimum Property Standard Report. But let me just tell you what it is. The MPS Report is a. Is a valuation of a property that is based solely on minimum property standards that have been established by fha. And there is a uniform appraisal guideline that's created by HUD for both Fannie and fha. Freddie, Freddie Mac, Fannie Mae. These are the different types of loan CAD classifications. Those have minimum property standards. So now, the picture you're looking at behind me, well, that doesn't meet minimum standards. The drywall is missing. The outlets are exposed. There's damaged wiring. You can see the windows have chipping, flaking, paint. All those things are obvious and gross minimum property standard deficiencies. But in the typical home buying scenario, most of the things in the properties that you're looking to purchase as a buyer will not fail minimum standards. So don't be afraid if you see, you know, a little bit of damage in the property, a little bit of rust, a little bit of issues here and there. The standards that the guidelines are requiring for the appraisal are minimum. What, in other words, is the home not livable? Is the home unsound, or is the home structurally compromised? Those are the three categories. Categories that are used when determining whether or not a property fails to meet minimum property standards. And so if the property that you're buying is livable, obviously it probably is, since you're looking to move into it. And is it sound? Does it have holes in the floors, holes in the walls, holes in the ceilings? You know, is the light fixture hanging from the wire? Unless it is obvious and gross failures, most of the things that the home will have will pass. That being said, the home inspector does not evaluate a home based upon minimum property standards. A home inspector evaluates a home based upon highest and best use. So, in other words, we compare property to optimum standards. When we do a home inspection, we're looking at the home to see how well does it compare to perfection. Because as a home inspector, our job is to give you as much information and detailed information as we can to help you make the best buying decision and to give you all the information and tools you need moving forward with that ownership of the home. So what does that mean to you? All right, so if we're looking at a house, and let's say, for example, we'll look at. Let's take a heater. The heater is 30 years old. The typical life expectancy for most furnaces is 20 to 25 years. So the heater is beyond its life expectancy by five years. Also, there's some minor rust that we see on the heater. It's just a little bit around the base. Maybe there was some sort of a plumbing leak or moisture and condensation, and it just rusted. Just a little bit of rust on the base of the heater. Or we take the COVID off the panel and we look inside the heater, and it's a little bit of rust on some of the elements. Okay, well, a little bit of rust and five years past the recommended life expectancy are conditions that would make a home inspector put on their report that the heater is in at best, marginal condition. You see what is perfection? What would be the optimum condition? Well, the optimum would be that the heater would be within its life expectancy. So in other words, under 20 or under 25 years based upon the brand and type and that there's no visible rust, that everything looks clean and great, that's optimum condition. And if those conditions were met, the home inspector will report that heater as functional or satisfactory. Okay. Or acceptable. As a renov. As a home inspector reports things that are beyond their life expectancy, show evidence of age and wear. If it's minor and not consequential at the time of the inspection, the home inspector will report those items as marginal. Marginal means that the item is subject to repair or replacement with within the next one to two years and the borrower should budget for that activity. So a home inspection report that says heater is beyond its life expectancy, visible evidence of rust inside the, you know, out on the elements or on the cabinet. The heaters listed as marginal recommend monitoring for possible repair or replacement within the next one to three years. Okay, I put that down on a home inspection report and an underwriter sees it, they're going to freak out. They're going to say, wow, wait a minute, this heater needs to be replaced in the next one year. That's, you know, they're not even going to be, you know, settled in making these mortgage payments. Maybe we need to have a heating contractor give a certification or maybe we need to have someone come out and look at this heater more. All because as a home inspector, we have to advise you of the present physical condition of that element. Now, with the minimum property standard evaluation with that type of report, it's a pass or fail. It's either yes or no, good or bad, passes minimums, meets minimums or does not meet minimums. And the heater that I just described would pass. So the underwriter can get an easy to understand report that is clear, concise, simple and gives him just what he needs to know. Does it work or does it not work? Because that is the guidance that a minimum property standard is based upon. And NFAC member consultants all have access to this report and can provide it to their buyers as an additional for an additional small fee on their TO in addition to the home inspection or as a standalone product also for a fee. And the fees are determined by each individual consultant. But the point is this, there are alternatives to a home inspection. If you are just looking to know whether or not the appraiser will pass or fail this property. And there is additional support to the home inspection that can help address the needs of the underwriter and cannot interfere or impede your ability to get a mortgage on a perfectly good home. Now, if the property is going to fail that test, if it's not going to make it, and it looks like it's going to be a problem from all perspectives, then, yes, it should possibly be upgraded to a rehab loan. And when you're working with a minimum, when you're working with an FHA consultant home inspector, you have the ability to flip it to a FHA 203k or a Fannie Mae home style or whatever type of mortgage base you're using, the rehab component of that base, very simply with the benefit of a renovation consultant who is a NAFAC member. So I hope that answers your question. It was a long answer. It took about 12 minutes. But the short answer is this. If you are looking to get a report to give to the underwriter, a minimum property standard report will answer your needs. Okay, so onto our next question. So we have just two more questions that I'm going to try to get to before we end today. The next question I got was with regard to choosing a contractor for a rehab loan. The question I got was, I'm struggling to find a contractor who will work with the rehab loan because. Because they all want money up front. That is a common question. It's a common issue. And I wanted to answer that because it's so important to understand. All forms of renovation loans can provide a contractor money to start the project. The FHA 203k loan has two different forms. There is the limited 203k and there is the full or standard 203k. Let's take the limited first because that's the easiest one. The limited 203k loan allows a borrower to purchase a home and add up to $35,000 of renovation costs that are not structural in note in repair. So looking behind you at this picture, which is a great example for this call, actually looking behind, you can see we're replacing the plaster. You can see we're down to the framing. We're going to put in new framing and new partition walls, but it doesn't look like we are removing any structural walls. If we're not moving a structural wall, if we're not removing a structural wall. And over in the corner over here, looks like we have a, you know, piece of 2x4 holding something up. So this might need to go full. But let's assume that they're not moving or removing any walls. And so we're going to able to use the limited 203k to just simply replace the drywall, run some electric wires, maybe replace some duct work for some heating systems, or add windows. Anything up to $35,000 which can go fast, okay, can be done with a limited 203k. If the contractor is working with the limited 203k, he can submit a request at closing or prior to closing actually to tell the lender how much money they need in upfront cost. Lenders will have specific and different parameters of how much money they will allow a person to borrow get in an advance. The HUD guidelines state that a person can borrow up to 50% of the total loan for upfront material costs. Most lenders try to stay away from 50%. That's a lot of money and it's a lot of. You can do a lot of hurt with that. Many lenders limited to 40%. Some are even lower at 30%. And some will require the contractor to provide a purchase order or, or an invoice or some sort of a quote for the cost of these materials to justify that expense. Whatever the paperwork that's required with the limited 203k, a customer's. A contractor can get up to up to 50% of the repair amount. This is only with the limited K. All right. And with the standard or full 203k loan, the contractor cannot get any money. The loan closes. They cannot get any upfront money before closing. At the time at the settlement table, a contractor can get a portion of the funds that have been allocated for materials in an advance. So in other words, if you're doing a project and let's say for example, we have a line item for wood floor, the cost of the total line item is $5000. Of that $5000, let's say 3000 of that is for materials. If the contractor submits a purchase order from the material supplier, Wood Floors or US and he submits that purchase order at closing, where it states that he's going to need to spend $3,000 for the wood floor, the lender can give the contractor 50% of that amount in an advance at the time of closing. So if he has purchase orders from Wood Floors or US Lighting in the World Lighting Inc. Whatever the companies are that give him the material amounts and the material amounts category is in the work write up, then he can get 50% of that amount given to him at the close of the loan as an advance. Now, once the loan closes. And this is where confusion begins. Once the loan closes and it's a full 203k, the contractor cannot get any upfront cash. However, there is a workaround. Let's say again, using our example with Wood Floors Rust, he has a purchase order from Wood floors rust for $3,000. The consultant can allow for a materials payment to the supplier to Wood Floors or rust for 50% of that amount. So in other words, the contractor would then give the purchase order to the consultant from Woods Floors r us for $3,000. The consultant would create and materials draw and the check would be payable to Wood Floors r us for $1,500 and would be mailed to the borrower. The idea is by mailing that document, that check to the that material is ordered in the borrower's name. Now why am I making that such a specific point? Because.
Many times, unfortunately, times are hard. Contractors like the rest of us, have trouble floating money. And sometimes a contractor will get a check if you give that check to Wood Floors R Us. And sometimes on the check it might have in the memo section your property address or your name, but it might not. And if it doesn't, that contractor can take that check to Wood Floors or US and it might possibly be used to pay off a past due balance that he might have on another project, in which case the money is not there for you, for your home. Okay, so this is why we urge you to stay actively involved in your rehab project and do the things that are going to create the accountability and protections for you as a borrower. So yes, the check is going to be mailed to you, payable to Wood Floors R Us. Or it might be at the lender might say, give us the address of Wood Floors or us. We'll send it directly to them if we do that. If they do that, you want to make sure from the lender that they are going to put in the memo your property address and your name. Okay? Many times they do. But if not, if the check is mailed to you, and most times it is, you should walk over, drive over, or go to Wood Floors R Us with or without your contractor and say, hey, here is a deposit on the Wood Floors from this purchase order that my contractor is going to be picking up sometime later. And at the time he'll pay the balance when he comes in to pick up the flooring, he does have to pay the additional 1,500. He doesn't get that money advanced. But the goal is when he goes in, pays the $1,500 quickly installs the floor. He can schedule a draw and be reimbursed for the fifteen hundred dollar material out of pocket and for his labor cost. So in other words, he would get the 2000 for labor, the 1500 for material in a check for 3500 because the 1500 was already paid to the supplier for a total of $5,000. This is the best and most successful way to ensure that your project monies, your escrow funds are being used for, for your property in a way that serves you best. And it doesn't impede, doesn't interfere with the contractor much at all. He should be able to float 50% of the materials just for a couple of weeks. And that actually encourages him to get the job renovation done as quick as possible so that he's not hung out to dry for a whole lot of out of pocket cost for materials. That is the value and the perfect special relationship that HUD wants you to have with your contractor when it comes to material advances. Now let's talk about other types of rehab loans like the Fannie Mae Homestyle. The Fannie Mae Conventional Renovation Loan does not have the same kind of restrictions or requirements or guidelines that HUD does. And in that circumstance, a contractor may get an advance and usually again, each lender can be different and is different, but usually 50% of the material a total. What that means is if your total project is $100,000 and the material portion of that project is 60,000, Fannie Mae Homestyle may allow the contractor to receive 30, $30,000, 50% of the material only category. If that is the case, you need to make sure if he's got, if the lender is going to do that, you want to do serious, careful due diligence on the quality, the accountability and the financial soundness of that contractor before you hire him, before you go to closing, you want to check reviews, you want to check for judgments, you want to check for credit problems. Because once he gets that $30,000, there's no going back, there's no getting it back from him. Many cases, okay, so you don't want to let that money go without you knowing that it's going to. The person you truly feel deserves that money and will use it in the correct fashion after settlement. And the Fannie Mae home style, yes, a contractor can receive money advanced to move forward with the project. So as you are the borrower, this is your property, this is your mortgage. The escrow funds that are being paid to the contractor are coming out of you the next 30 years. So you can say to the contractor, look, I don't feel comfortable with any contractor getting $30,000 up front to hasn't started the project. I don't get paid before I go to work, okay, I've got to go to work, do my job, and then I get compensated. So I tell you what I will do. I will let you get 15%, you know, 25% of the upfront capital or $15,000. And then after we start work, when you provide me the purchase orders of the materials I've selected, I haven't even selected materials yet. I don't even know what the total costs are going to be. So after I select the materials that I'm going to be using and you give me the purchase orders and I will approve and agree to the consultant and the lender advancing you more money based upon that purchase order. At that time, he can get more advances because Fannie Mae does allow it to be paid to the contractor directly as opposed to suppliers. So protect the process. The consultant can guide and support and help you. But we can't tell you how to run your rehab loans and we can't tell you what what to demand of your mortgage lender or your contractor. Remember, you are paying for their services. You are the employer. And these people need to work and respond to your needs. So I hope that answers that question. Now, we just have about five minutes left for the last question and so I'm going to get to that real quick. The last question has to do with the upcoming 203k discovery days and you can actually go and log and sign up for that event absolutely free. The question I had was I'm not a home inspector, I'm not a contractor, but I want to know more about rehab loans. Can I attend this event? And the answer is of course, yeah. And please do. This event was made free and we have received so much support from people because need to know you as a buyer, as a real estate agent, as a lender, as a contractor, all need to know more about rehab loans. This little quick conversation we had about just two topics only the tip of the iceberg. And at the 203k discovery days, you'll be able to hear from some of the most amazing industry leaders on success and renovation, mortgages, real estate services with rehab loans, consultant activities, how to become a consultant who qualifies to be a consultant. How to be successful as a rehab consultant, lender contractor or real estate agent. Hey, it's 2023. Interest rates are up, inventory is still down. Many homes that look like the one behind me are open for sale and the prices are less because it's easy. It's harder to sell these homes. Don't turn down the diamond in the rough. Get your 203k rehab loan, your Fannie Mae homestyle loan, your renovation, your VA rehab loan. Join us at the 203k discovery dates. Learn how to be able to be using a rehab loan as a power tool for you, someone you work for, someone you know. So we're just about out of time. So I just want to thank you all so much for joining us today. Remember, you can post your questions here on our NAFAC Facebook page, our Instagram page, or you can email me directly@c hallafac.org so until I'm able to support you in the future, which will be Next Thursday at 10am I hope you will be outstanding. Have a great day. Bye. Bye.
More from Catherine
Getting last minute details ready for the 203k Discovery Days just 5 days away!
Savvy real estate pros are attending the 203k Discovery Days Livestream event 2/25-26...are you?
Real Estate Sale Pros Can Grow Their Business In Spite of Sluggish Market With Rehab Loans