211- Courage to Leap & Lead with Louise Story part 1Courage to Leap & Lead
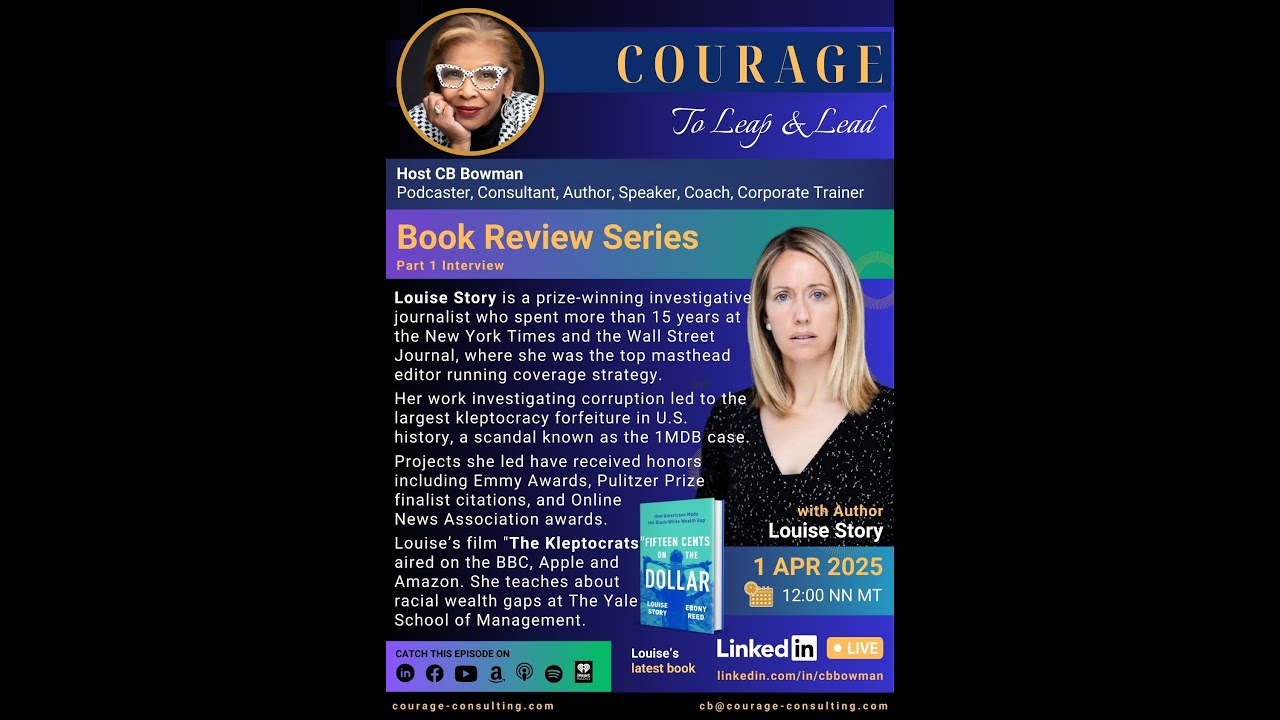
Journalist Louise Story and co-author Ebony Reid analyzed Federal Reserve data and found that the typical Black family holds only 15 cents of wealth for every dollar held by a typical white family. Most Americans don't know this gap exists. They wrote a 460-page book telling the history through narrative, arguing that debt, inheritance, and systemic mechanisms like risk-based pricing keep the disparity alive.
Chapters
You've got courage to leap, courage to lead.
Be brave and be bold.
Wow!
Let it roar. Welcome to the Courage to Leap and Lead podcast, where each of our guests share the stories of courage that helped them become powerful leaders. Before we start today's show, please remember to visit courage-consulting. Where you can find all the episodes and other excellent resources, all at courage-consulting.com. Now, here's your host, Leadership Courage Coach CB Bowman.
Hi everybody. This is CB Bowman, your favorite podcaster. And we are live on Courage to Leap and lead. And speaking of which, I have an incredible guest. Let me fix my straps here so I don't look weird. Thank you. We have a great guest who's written a book about something I hate to admit my ignorance, but I was completely ignorant about racism in relationship to generational wealth. And we met on LinkedIn, and I saw what her concentration was, and I thought, wow, that's interesting. I need to have her on as a guest, a 2-part guest, one to talk about herself and her work, and the other to talk about her book. So we have a combo today. So please, let's get started because we have got a lot to talk about. I want to introduce Louise Storey. Louise, welcome.
Thanks for having me.
Thank you for your research and your book.
Thank you.
First, let's start with telling us about you. What do you feel comfortable sharing about how you grew up, your parents, and what led you to writing this book?
Sure. And you know what's so interesting about writing a book, particularly a book that revisits history of our— the history of our country like this book does and talks about things that have happened through the generations, you start to rethink your own history. And so I'm going to tell you about a little bit about myself, but I'm going to tell you what I'm going to tell you now may not have been exactly what I would have told someone 6 years ago, you know, because I, in doing this book— and I'll go ahead and show it. We'll show—
we can show it a few times.
Please. But in doing this book, It made me rethink a little bit which aspects— you know, there's many different things in your history, and you only highlight a few when you talk to someone— which aspects, you know, have been really important and influential in my upbringing to some of the things that are my values today and my interest later in life. So I grew up in Florida. I moved there when I was 2. I was born in Atlanta. The book is set in Atlanta, where my father had been from, and I was born in Atlanta. And then I grew up in Florida, and in Florida I went to public school K through 10th grade, and my elementary school was on in Maitland, Florida, on the border of Eatonville, Florida, and about 40% of the students were from Eatonville, and the others were from Maitland. I was from Maitland. Eatonville, as you may know, is one of the oldest historic Black communities in the country. communities in the United States. And by being in an elementary school with my classmates, so many from Eatonville, and a higher percentage of Black Americans than you would have in many elementary schools, and also higher than our national average in the population, I just felt very open and friends with people who were white and Black from a very young age. And the birthday parties that I went to were birthday parties of people in Maitland and Eatonville. And I remember in the '80s, the 1980s, when, you know, Eatonville— there was an effort and a big fight to keep a highway from coming out of Eatonville. I didn't fully understand that at the time, but I remember it, and I've come to understand these things better now. Like, what does it mean when someone's gonna put a highway through your community? So that was part of my upbringing. Other parts of my upbringing is that I was very active and involved in the theater arts and opera community in Central Florida, and I was in a lot of performing arts, which also at a young age put me in a very inclusive community. You know, even in the '80s and '90s, the LGBT community was very welcome in theater, but they weren't as welcome nationally. And again, as I think about my values today, I think these things in the young age, you know, helped me really value inclusivity. So I did theater. I thought I would grow up and be an actress. When I got to college, I went to Yale. I started doing this school newspaper, and I found very quickly that journalism has a lot in common with theater, because when you play a part, you have to step in someone's shoes and you have to embody them. You have to understand another perspective. And as a journalist, the best journalists listen and learn other people's perspectives and capture those in the writing. And there's storytelling in both and there's learning and a lot of listening. And so I think that, you know, from a formative age, focusing so much on understanding all different people by being in theater also made me want to do that as an adult. And in journalism, I do do that. So, you know, after I went through school, undergrad and business school, I went to The New York Times. I worked there for 12 years. A lot of those years as an investigative reporter, some in digital strategy for the New York Times, helping figure out, figure out the future business model for the New York Times. Then I went to the Wall Street Journal as a senior editor and ultimately as the chief product and technology officer, again working on some of the strategy to reinvent news for the future, but also running the coverage. And I was running the coverage strategy at the Wall Street Journal in the year 2020. When George Floyd was murdered. And you know, that set off a period of a lot of conversations in our society, and we were having those conversations at work. And you know, in my job I was thinking about how we would cover the demonstrations, how we would cover the corporate pledges. If a bank said they were gonna do something new, was it a big story or not? And what did we share about that with readers? Because there were a lot of pledges, and no one knew if they were serious or not. But I was also, you know, it was the pandemic, and I was also talking with my colleagues and team members of all races on Zoom. But also, you know, with one team member in particular during the pandemic and during this racial reckoning, some of the conversations turned personal. And this colleague is also a very talented journalist. Her name is Ebony Reid. And if we had never had the pandemic and never had these the racial discussions of 2020, maybe she and I would have just focused on our work and not also started talking about our upbringings. But I found very quickly we were very similar on paper. We were in a similar prestigious area, you know, of journalism, both highly accomplished. We both had fathers who had been the first in their family to go to college. We had a lot of similarities, and we have a lot of similar values. But there were also choices and situations that her family and she had faced in her life that I didn't face, that when we really drilled into them, race and racial differences seemed to be a part of the explanation. And so Ebony and I looked around to see if there was a book that explained all this, and we found that there is no book on the whole history of the Black-white wealth gap. And I'll never forget the day— like, I'm really into data and data crunching— I went and crunched the data from the Federal Reserve, and I found that the typical Black family has 15 cents in wealth compared to $1 in wealth, a typical white family. And I called Ebony, and I said, do you know this? And she was shocked. And she said, I know it's different, but 15 cents in the dollar? I mean, she thought it was— there was a gap, but not that big. And so we decided we would be the perfect pair to write this book. And so this is a book that's a book done in partnership. And I'm so happy to be here talking about it. But it's also really important to me to recognize Ebony, because we did this book in partnership, and we worked on it for 3 years together, and it was a journey we went on. And so I'm really happy we were able to do it.
So, okay, that's, that's a long story, and I have so many questions coming out of it. The first question I have is, first of all, let me acknowledge That I was not aware, was totally ignorant of the representation of 15 cents on the dollar, of generational quote-unquote wealth, of racial differences in wealth. I'm not saying that I didn't understand that we people of color made less money.
Right.
That we had— we were not able to buy homes like white people. We were not able to move up in corporate America like white people. I'm not saying that. I think it was more of a shock, like for Ebony, this 15 cents on the dollar. It's when you go down, drill down to actual numbers.
Yeah.
You know, there was a lot of coverage on the media with the killing of Floyd about generational wealth, about, you know, racial differences in wealth. But hearing those numbers, what the hell? How did we even— people of color survive?
Well, I just want to tell you, you are not the only one who doesn't know this data. One of the reasons we decided to do this book and we decided to call the book 15 cents on the dollar.
Right.
Because this statistic is not well known. There's studies that show that 42% of white Americans think there is no Black-white wealth gap. 42% of white Americans think the wealth of typical white and Black people is the same. But get this, 38% of Black Americans also do not know the size of this gap. And, you know, yeah, that think it's smaller than it is. And so there's—
Awareness. You said that— correct me if I'm wrong— 38% of white people don't know that there is a gap in the wealth between white people and Black people.
40— close, 42% of white people.
But it's 38% of Black people Also, right, but wait, how could you not? I mean, I knew there was a gap. I didn't know it was 15 cents on the dollar. How could you not know? How could you live in this world and, and see the difference in wealth?
Well, you know, um, this book—
Upsets me, and there's not a lot that shocks me these days. But tell me that you don't see the ghetto versus Chapel Hill, or, you know, or some other wealthy area, some of the many, many wealthy areas in the United States. Come on.
There is a lack of knowledge about the gravity, the hugeness of this gap, and a lot of people who don't know how big it is just think there's been more progress than there's been because of things like the civil rights movement and so on. And so it really motivated us to write this book to help not only inform people of this gap and explain it, but also to help people care about it. So this book, as you know, is told through people. It's really like reading a novel when you read it, and that's to help people to create empathy. And we have been speaking around the country. We've had more than a dozen regional racial wealth gap symposiums. We did one in Denver out by you and all over where we have brought together panels of other people from the region also who work in spaces around this and tried to bring this data point and the focus on wealth more in the conversation, because a lot of people are focusing on things related to this, but not on wealth. They're focusing on— Housing, very important, or business formation, very important, or a lot of companies are focusing on pay equity, very important. But none of those things are exactly the same as focusing on the wealth gap. And so we just think more people need to focus on this wealth gap and understand it better.
So I remember seeing relative to this, I never knew that was— there was something called the Black Wall Street.
Mm-hmm.
And I noticed recently there's a new commercial out, and I don't remember the name of the bank. It's really funny, where a Black woman who owns, I believe it was a restaurant, never thought she could buy a house until she opened an account at this bank, and one of the bankers helped her get the money to buy a house. When you see things like that on TV, do you— and I'm not saying you could speak for every white person in the world or even in the United States— does it not occur to people that there is a huge difference in the ability to just buy a home and it's based upon wealth?
Well, I mean, I think there's a lot of things people who have you know, examined different levels of income and economics of white people might say to explain why some white people, you know, there's plenty of white people who also don't have a lot of wealth, right? And they may not understand that still compared to someone of the same income who's Black, they have more wealth than them. But the focus of our reporting was on what's happened through history that has increased this gap and held it in place and caused this gap, not really on, you know, analyzing everyone's perception on today. We just know those data points where I can tell you that a lot of people don't really understand it well. And, you know, we think if more people take time to learn the history of this and even just know the basic statistics, you know, they're going to think differently. Our number one goal for the whole project we've done, not just the book, we think of it as a public impact project. is to make 15 cents on the dollar a nationally recognized statistic, because we think if people knew that, knew what it was, then they'll talk about all kinds of things— education and housing and policies at work, all kinds of things differently— if they just, if they just know that's where this Black-white wealth gap stands today.
So what is it that you are doing or that we can do Number one, just to call awareness to employers. Now I'm going in the organizational side that the difference in pay is part of this wealth gap.
Well, a lot of companies have worked on pay equity policies. And that is a part of the gap, but it's just not the whole gap. So let's talk about for a second what wealth is, and that'll help us understand the gap better, because a lot of people don't actually understand fully what wealth is. In fact, Ebony and I co-teach a business school class at Yale University. We've taught the past 3 years about racial wealth gaps, and we find even MBA students have different definitions of wealth when we ask them. So, you know, wealth is everything you own minus what you owe, right? So, your assets minus your liabilities. And the common mix-ups that we see is a lot of times people confuse income with wealth. You know, when we'll tell people, you know, we've written about wealth gaps, they'll say, well, you know, at my company, income of people in the same job has been, you know, we've got pay equity, so there's no income— income gap. So what's the problem? But income is a flow. It's what you get every year. Wealth is a stock. It's what you're building. And for example, if you sit next to someone at work, and if your company has equalized pay, which not all companies have, there still is an income gap between white and Black Americans, as well as white and Latino Americans. But if your company has stabilized it, you get this flow of income, and then the person next to you of a different race also gets a flow of maybe the same income. But let's talk about the fact that the average Black person who went to college has more student debt than the average white person. So now you're sitting, a white and a Black person next to each other at work, and just statistically speaking, The Black person— let's say these are 2 people in their 20s. The Black person has more debt to pay off with that same income as the white person. So the white person is able to take that flow, and if they want, start building wealth, buy a house, invest in stock, put in their retirement fund. But that Black person with equal pay has that bigger debt and isn't able to start building wealth. So just understanding that income is something, and it's really important to equalize it. When people are in the same job, they should be getting the same pay, whether they're male or female, whether they're different races. Pay equity is important, but it's just not the whole picture, because if all pay is equalized, there's still different debt levels in our society. A lot of people forget debt when they think of wealth. They think they see someone in a nice house or a nice car, they're wealthy, but they don't know how much debt is behind that. And debt is kind of invisible. You can't see it. And so Debt levels are different. And the other thing that's really different is generational inheritance.
I just wrote that down. I said, I wonder if she's going to touch on inheritance.
You got it. Yeah, you read my mind. But it's not just inheritance when someone passes on. Throughout people's lives, the ability of your family to help you with things gives you another source of income outside of your job throughout your life, depending on your family situation. And so that, you know, hinders the ability to build wealth.
So is there a solution other than informing? Is there an action step that can be taken?
So Ebony and I are both journalists, and, you know, journalists are nonpartisan. We don't, you know, pick political candidates or push particular policies. But in the scheme of working on this book, we felt by the end of working on it that we had some personal recommendations for people, some things people could do in their own life that would add up and make a difference. And so our final chapter does include personal recommendations, and I'll share a few with you.
Please.
One is support wealth transparency. Very little is known. One of the reasons that a lot of people don't know about this wealth gap is there's not actually that much government data collected about wealth, period. If you think about all the government resources that go to collecting information on unemployment or GDP growth, it's a lot. And the study we feature in this book is the Survey of Consumer Finance from the Federal Reserve. It only comes out once every 3 years. The data is not very granular. You can't look at data of wealth by race, by region, for example. You can't look at different states in it. You can't look at household structure. It's not that extensive of data collection. And so, you know, we just think for people to understand something, you need more data. And it's not, I'm not saying, you know, you get to know each person's wealth, like, but aggregated anonymously, you know, helping our society study where wealth is. And part of the reason it's not that well understood is also, of course, to the government, we report income, right? We don't report wealth. And so where, where would the government have this wealth data, right? And all at the point of, of someone's passing, then there could be a snapshot into their wealth. But a lot of money has passed hands before people pass away. Plus, race is not asked in those filings, so you wouldn't know the race. So we just think, you know, that's one thing. Another thing that we think would be really eye-opening for a lot of people is to do what we did, which is partner with someone of a different background and lived experience from you. And when we say partner, we mean something where you have time on the line, money on the line, reputation on the line, a major project. And this was a major project for us. It's a 460-page book, right? And we spent 3 years on it. And in our partnership, it was really important to us from the beginning to be fair to each other and to make this, you know, a partnership. And so we started out—
What did that look like?
Well, so we started out with the idea, you know, the idea is a partnership will try to— you first go to the word equal, right? But we found over time that we really needed to try to make things equitable. So equal, you know, would mean We both do exactly the same. We both contribute the same amount of time. We both contribute the same amount of money. But when you really get to know someone, and if you really are in a partnership where you're learning about the other people, you realize that $1, one person's budget would be a different percent of the money they have available than the other person's budget. So is that fair? So $1 from one of us might like really set us back more than the other person. So we decided that it wasn't right to try to have exactly the same thing, that we wanted to be equitable, which is working out solutions that we thought would create a great project, but that we're cognizant of each other's situations and what we, what we could each do, which was different in different circumstances. And so it's been a great partnership, and we've really learned more about the give and take that a real partnership that tries to be equitable has. And, you know, if more people founded a company or undertook a big, you know, a creative project, or, you know, a big project with someone of a different race or a very different economic level, and really wanted to be thoughtful partners and fair, not just tit for tat, I do this, you do that, people would learn a lot. So we make a recommendation that people find a way in their life to carve out a big project where they're going to do that.
And number 3?
Well, there's some others. We suggest that people be— this is going to sound basic, but be open to change. So, you know, there's a lot of people who will talk about, you know, that they would like to see, for example, more affordable housing, so a broader variety of people could live around them. For example, this is an example, but then they don't want it built next to them, right? So we also talk through in these recommendations how people should think about if they say they want change, that they really need to be comfortable with change. happening around them and embrace that and be open to that.
So, you know, when I talk about fixing this, I'm also thinking, is there— I don't know, I'm going to say a workshop, a class that parents can go to to learn how to set up or start the ball rolling with regard to wealth Well, there, that's, that's a, that's a good idea, and certainly could be helpful to parents of probably all backgrounds, and might be helpful.
You know, a lot of what companies have focused on is financial literacy, financial education. We think if you read our book, it will be apparent to anyone who reads the book That this is not just about people not knowing what to do. You know, it's very clear when you really dig into this and follow the history, which happens year after year, that even if you are working hard and trying to do the right things, there, there are things just in the way policies work and broader things beyond an individual's actions that are financially hitting people of different races differently. So I'll give you an example. We highlight, for example, automobile insurance in the book. So, and that's part of a long line we have in the book about risk-based pricing that goes through the insurance and banking industry, and we trace it from the 1800s. But today in 2024, automobile policies are priced in part based on the zip code where you live. And the crime rate in your zip code plays a role in the premiums that you pay. It makes complete sense from a company's perspective. If there's higher crime in an area, they want higher premiums because there could be more break-ins to cars, right? And so part of the problem we highlight are these ways, business practices that have been developed and become commonplace without an eye on what does that mean for the individual. So let's talk about what it means for the individual for a minute. You can have a person lives where they live, and they've worked really hard. They've saved up money, enough money to go purchase a car or to do, you know, a long-term lease on a car. Now they need auto insurance. And let's say this is a Black person or a Latino person who lives in a higher crime zip code. Now they have to pay more for their automobile insurance than someone living in a really wealthy zip code. I really do not think that people living in wealthy areas know that they are getting to pay less money for auto insurance than people who have less money than them. And you have to ask yourself, is it that individual's fault that they're in a higher crime— if there's more crime around them? No, not for all people. They may never be involved in crime. They may live there 'cause that's where their family lives. They may live there 'cause that's where they can afford to live. There's all kinds of reasons people live places. So is it that individual's fault that there's higher crime? So why are they paying more for auto insurance? So that is an example of, you know, all the financial literacy in the world you want doesn't change the way, in fact, that like this is just being priced differently and it's not priced based on race. It's priced based on zip code, but there are racial patterns in zip codes. And this does mean in practice that Black and Latino Americans pay more on average for auto insurance than white Americans.
Oh, I'll give you another example. Grocery stores. Grocery stores in a high-crime zip code charge more for food than low-crime. Zip codes.
Interesting.
I was shocked to find that out. I thought, well, you know, because I lived in New York, I'll just go here and buy this and here and buy that, you know, depending upon what I was cooking, whether it be Asian food or food for people of color, you know, I wanted to do some hand hogs or something like that. Much more expensive in the Black markets and Black stores than in the white area zip codes.
And by the way, we didn't look exactly at that in the book, but I can just, in listening to you, tell you there could be many reasons.
Part of that— They assume that— well, there's 2 that we see immediately as people of color. One is the crime in stealing groceries, and the other is because we're a deep pocket for the companies. Because one of the traits is, as a person of color, you don't do price comparison a lot because you're embarrassed that you can't afford what's being asked.
Hmm. Those— that's really interesting. And I'll tell you, other reasons also could be we do write extensively in the book about minority-owned businesses, Black-owned businesses, or could be— there's also been a lot of emphasis on women-owned businesses, Latino-owned businesses. And we do write about the challenges that non-white males— non-white and not male, you know, you know, not if you're not a white male. People have in getting business loans.
Loans. Yes.
So it also could be the case in some of these instances you're describing that the business that you're shopping at wasn't able to get as low of cost financing for their business, and therefore that bakes into their cost of operations, which they have to pass along to shoppers. So there's just a lot of reasons.
When I'm talking about it, it's not Black-owned businesses.
Oh, I see.
It's places like, uh, you'll see Safeway.
Oh, I see.
Example where if you go to Safeway in one area, the pricing is very different.
I see, I see. Well, we did not even examine that. You're giving, you're giving your listeners even something in addition to our— and it's really interesting and important for people to understand these things, you know.
Yeah, because if you're paying more for the cost of living, yeah, That's going to affect what you can afford in terms of insurance, and then health insurance and car insurance and even apartment insurance. Then of course it's eating into your ability to leave money to the next generation or even to help the family of the current generation.
Right.