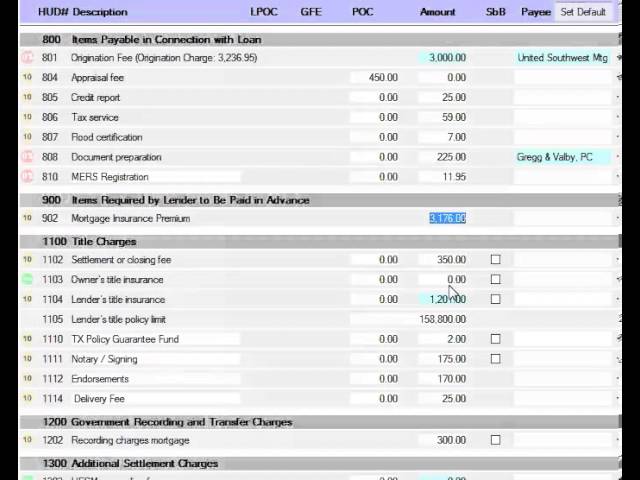
Cliff Auerswald explains how reverse mortgage lending limits work: they're roughly 63.7% of your home's appraised value, minus closing costs like origination fees and mortgage insurance. On a $158,000 appraisal, you'd get about $92,000 in net credit after costs. A lower appraisal drops that significantly.
Chapters
Hey there, it's Cliff Auerswald with All Reverse Mortgage Company, and I just wanted to respond back to your questions about how the reverse mortgage closing costs and figures work on the line of credit option. So basically what we have here is based on a value of $158,000, you receive a principal lending limit based on your age of $101,000. $155,000. That equates to 63.7% of whatever the appraised value comes in at. So if the appraised value comes in lower or higher, you're going to get 63%, 63.7% of that appraised value before the finance closing costs, and you would have a net credit line of, on this case, $9,200. $92,000, sorry. So the closing costs are all included with the exception of the appraisal fee, which we get on your credit card to begin the process. That's by default, but if you'd like to move the appraisal fee over to the finance fees, that's fine as well. And these are all of the closing costs on your loan: $3,000 origination fee, you've got mortgage insurance premium, title insurance, notary, all of the third-party closing costs that are actually required to process and close your, your loan. So if we come up with a property value comes back at $125,000, all of your closing costs will adjust to that, including the required mortgage insurance premium, the origination fee, and the third-party foot costs. So you would net a total line of credit of $72,000 should the property value come in at $125,000. And basically the appraisals are, um, 90% of appraised value is going to come in based on other sales in your area that are comparable in square footage, bedroom count, and lot size. So the appraiser is going to come out and typically go within a half mile to a mile out of other sales 3-4 months back. And they're going to do a comparison approach, which is a sales comparison based on your property versus the others that have sold. And they'll make adjustments for condition, overall condition that is, and square footage, things of that sort. But basically, after we get the application received in our office, we will schedule the appraisal. And after the appraisal comes, get comes back in, you'll get a copy of that report, and we will go ahead and give you your updated figures and make sure you'd like to proceed as is. So if you have any other questions, just let me know. Cliff Auerswald at All Reverse Mortgage, 1-800-565-1722. Thank you.