The Financial Freedom Formula Master Your Money and Grow Your Wealth 16 November, 2022
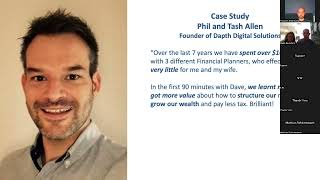
Dave Parry teaches a framework for building wealth through three visions: lifestyle, cash flow, and debt-free. He covers five pillars (income, cash flow, debt, tax, future), three asset classes, and compound interest, with an eight-week coached program to turn strategy into action.
Questions this video answers
76% (Australian Bureau of Statistics, as cited in the talk).
One in three single women over the age of 60 are living below the poverty line (as cited).
$2.3 trillion (figure cited for Morgan Stanley).
Chapters
For the price tag. So now onto something serious but light heartedly informative. It's my absolute pleasure to be introducing Dave Parry, an accomplished finance consultant, passionate educator, presenter and wealth Coach with over 32 years experience in financial consulting, education and property investing. Dave's passion and mission is to inspire and enable everyday Australians to achieve their own sense of financial freedom. A keen businessman, an international presenter and trainer, Dave has interviewed over two dozen multi million dollar earning entrepreneurs and has rubbed shoulders with the likes of Hugh Jackman, Rick Astley, Sir Cliff Richard and of course Sir Richard Branson. Today, as part of the Financial Freedom Formula series, Dave will be running us through a whirlwind of ancient and contemporary financial wisdom and will generously share principles with you that if you take hold of and put into action, will have extraordinary benef for you not only today, but in years to come. So get ready to be inspired, open your mind and learn something new while having fun. Please give a thunderous round of applause for your host for today, Dave Parry. Well, welcome, welcome, welcome and thank you for joining me to the Financial Freedom Formula where you will discover the four steps to really master your money and grow your wealth. Now you've just had a little bit of time to find about me and we have a limited amount of time and I, I promise you I will try and cover as much information and as much give you as much value out of this as I possibly can. But look, I'd just like a little bit of feedback from where, where are, where are you dialing in from? Whereabouts are you dialing in from? If there's this thing in Zoom called the chat box, unless you've been living under the rock for the last two hours, you, there's this thing called the chat box. I'll put a little welcome in there saying, hi all, someone SW is from Sydney. Welcome sw. I'm coming from a little town you may have heard of, begins with P and ends with Earth. It's called Perth. So I'm coming from Perth and it's just wonderful that I've got clients all around the country. Now I've got another Perth. Welcome, Thurston from Perth. But also look curious, where actually specifically are you dialing in from? Are you sneaking in still from work or you're down the park in the car? Anyway, I'm obviously in, I'm in the studio office here and that's the fun thing. We've got this whole new way to of approach of learning these days via Zoom. Look, and if you just in case you're not sure, how it all works. If you click on your zoom, there'll be an option to open up a chat box and the chat box will let you type in and just support each other with a little bit of fun. We've got actually Navid also we've got, we've got Tashi or Tashi, Tashi from Melbourne and Navid from Sydney. So we just want a Queenslander and we'll be close to being done. Now forgive me, every time I look over to side here I've got another screen open. So that's why I'm looking at the chat box and keeping a tracker things there. But just get started. I want you to consider a question, a little question for you and the question is quite simply this. What does financial freedom mean to you? I want you to think about this. Don't type an essay in the chat box, but what does financial freedom mean to you? What would it actually look like? What would actually mean to you? What would it look like? It may or may not be something you've reconsidered before, but it would be as simple as maybe being debt free or being able to quit your job, maybe start a dream career, have more holidays or bigger holidays, maybe buy a new car, upgrade the house, downgrade the house, or maybe get to that ultimate place and being able to contribute or volunteer now. Interesting. There's been a survey going around by amp what about large financial institutions and on top a lot of people's lists these days as they head towards future with freedom is that ability to volunteer, to give back, to contribute. Now, whatever financial freedom means for you, the cool thing is that's what it means for you. I'm sure you've got some sort of vision of what you'd like your future to look like, to have some sort of financial freedom in the future one day. But let's be honest, there's probably, if you've come to an event called the Financial Freedom Formula, there's probably a bit of a gap from where you'd like to be and where you are today. Now, I'd just like you to consider this, that you are in fact under no obligation, you are under no obligation whatsoever to keep doing the same things that got you to wherever you are today. You see, wherever we are today is the result of our actions. But just by being here today and showing up, I just want to commend you and say thank you for giving up some time. But also shows that you're a decision maker and an action taker because you've clicked a link you've followed or something, you've seen the emails and the text and here we are. So you've made a decision and taken some action to be here and put some time aside to learn. So wherever you are today is a complete result of, I guess, the results of the actions that you've taken. But if you'd like different results, in fact, just put a R in the chat box for results. If you'd like some different results around your finances and your wealth, just put an R for a different result here on that. Or maybe you'd like to, in fact, you know, increase your results or maybe elevate your results. So if you want to elevate your results, it's just possible you might need to take some different actions. In fact, Einstein put it quite succinctly when he said the one definition of insanity is this. It's doing the same thing over and over again and hoping to get different results. So you're under no obligation to keep living the way you've been doing things before. You just might need to consider to take some different actions. Now I'm just going to show you some of the value that I'm going to cover today. And before I do that, I just want to. Now I'll show you the value and I'll give a disclaimer. I'll show you the value, then I'll give a little disclaimer. So what we're going to cover, we're going to cover the four simple steps that you can follow to start to master your money and grow your wealth. And it's called the Financial Freedom Formula. We're going to hear a few statistics from these people, which is the Australian Bureau of Statistics, that maybe put things in a slightly sobering light for some of us. We're going to hear some very interesting commentary from Morgan Stanley, one of the world's largest investment banks. We're going to hear some words of wisdom from probably the world's most loved genius, Einstein, and I'm going to explain to you the five pillars to wealth. The five pillars to wealth. The five pillars to wealth. If nothing else, soon I'm going to be drawing a diary diagram up here. And if nothing else, just pay attention to the five pillars of wealth. And look, before we go any further, please, please take some notes. Please take notes. I'm just trying to pack a lot of value in here. I've. I sometimes go a bit quick, so just make sure you grab a pen and please take some notes. And ideally, I don't know if you can see this or not, it's a multicolored pen because some of the diagrams I'll be drawing are in multi colors. So follow along with the five pillars to wealth as well. And we're also going to hear from these people and find out not only from these people, what they have in common with some of these, let's say celebrities or famous people, I'm sure, at least some of which you would recognize. And look at the end, I've got a little surprise bonus for you as well, but I have a disclaimer. I have a disclaimer and the disclaimer is quite simple. You may have been coming along to a lot of different events under the guise of this. And if you're expecting at the end of this event for me to try and sell you something, I'm sorry, you're going to be quite bitterly disappointed. I have nothing to sell. I'm not, there's nothing to sell. So you can just put away your credit cards, leave your wallets at home. The disclaimer I had is this, this is a financial event. And yes, I've got training, you can probably see my qualification, the diplomas at the back. But I don't know your situation. So we're going to give you a lot of information, have a lot of fun. Just bear in mind this is not specific to your situation and the disclaimer is there's nothing to buy. This is a great something I need to tell you about. I've got an eight week program, the eight week Bulletproof wealth Breakthrough program. But I just like to talk about that with people offline, one on one and just see if we're a fit. So there's nothing to sell. So just relax and enjoy the information. So with that in mind, I would like you to answer these six questions if you can. Now, if you have the ability to actually put your cameras on and wave and put your hand up, it's appreciated because you need to understand I'm just sort of talking to a camera. I can see a few of you have your cameras on, which is kind of nice. So either with a show of hands, with a, with a hand up or just put a Y in the chat box. Just let me follow along with these questions. First question, would you like more money? Would you like a bit more, a bit more of this stuff perhaps? Okay, cool. Well, actually I'm going to give you an opportunity to get some of this literally later on. You'd like a bit more money. Cool. Let's be a bit more specific. Would you like to find out how to increase your income. Okay. Would you in fact, maybe like to create a bit more cash flow in your life? See, there's the distinction there. We want to increase our income, but income and cash flow are quite separate. I'll be talking about that soon. Look, if you've got debts, would you like to find out how to get your debts down? Great. Now, often we have this thing when we're earning an income that we pay. It's called tax. If you're paying tax, would you like to find out how to pay less tax? Cool. And the final one is, would you one day like to have a future that you can look forward to where you know it's a future with freedom in it and it's something that is really inspires and lights you up. Financial freedom in the future. Would you like that? Great. Well, look, if you've answered yes to any of those, look, you're in the right place. And in fact, you're also 100% not alone. They're the things I want for myself. I want to constantly be able to increase my income, create more cash flow, pay whatever debts I have, whether they're investment debts these days more than anything else, pay less tax and have a fantastic future, not only for me, but my family, and maybe leave a legacy for those that I love. Now, over the last 25 years or so, it has been my privilege and pleasure to have had hundreds. In fact, I've clocked over 10,000 hours in individual consultations with everyday Australians. And these are the things we want. So you're in the right place and you're not alone. But I want to talk a little bit about one of them in particular, and it's called cash flow. Now, cash flow is a little bit overlooked. And the distinction is this. Income is where the money comes in and cash flow is where the cash flows. So money, income come in income. When cash flows. Where the cash flows. Now, cash flow, when it comes to our finances, when it comes to our wealth, is super important because from a psychological perspective, it's cash flow that gives us choice. And from a psychological perspective, the more choice we have, the more freedom we experience. Does that make sense? The more choice we have, the more freedom we experience. In fact, the opposite is true. In terms of will we take away your choice? We experience less freedom. We feel less choice, less freedom, less control. In fact, our society understands this because we use this in our penal system or our prison system, if you like. Because if you're a bit of a naughty person and you don't need your show of hands for this. But if you've ever driven a bit, speed or whatever, you lost your license, if you're naughty with your car, break the rules, we take your license away. Well, not we, the government does. If you're very naughty person and break the rules or the laws you end up with in a place begins with P and ends with risen. And it's called prison, where just about all your choice and freedom is taken away. And the worst of the worst offenders in prison are in solitary confinement where for 23 hours a day they have no choice. So the point I'm trying to get to you is this. In fact my wife, who's a developmental psychologist, I've been married to Jasmine, my beautiful wife, for over 22 years now. It's a developmental psych psychologist. She still reminds me that I'm normal, I'm human, and I get stressed and bugged out by things you said, Dave, you're acting like you've got no choice. So the more choice we experience, the more freedom we experience. So with our finance, it's cash flow that gives us choice and choice gives us freedom. Get it? Cash flow gives you choice and choice gives you freedom. So in that context, the show of hands or just a why in the chat box, would you like a bit more cash flow, choice and freedom today? Awesome. Great. Now, in fact, would you like some, maybe cash flow, choice and freedom not in today, but heading into your future maybe to have that cash flow, choice and freedom to retire, Start living the way you want to live your life, whatever that means for you, Maybe even some cash flow, choice and freedom to start to really plan ahead or contribute or leave a legacy, even for those that you love. Well, if that's for you, if that sort of concept lights you up, I say you are in the right place. But I need to share some statistics with you that puts it in a slightly different light. And the first statistic is from the Australian Bureau of Statistics and they have to say this, that 76% of Australians will in fact retire on $20,000 a year or less. 76% of Australians will retire on $20,000 per year or less. Now, $20,000 a year is less than $400 a week. Less than $400 a week. So how much cash flow, choice and freedom do you think you'll have on less than $400 a week? Now, I'm here to tell you this. If you are not debt free by that time, if you do not own your home because you've either still got a mortgage or you're renting. Can you, can you probably see that $400 a week is not going to be a pretty picture. So that's statistic number one. Statistic number two comes again from the Australian Bureau of Statistics and some other sources. Now this one was quite pertinent to me because this was this what happened to my nana and my gran when she was alive, that one single women over the age of 60 are in fact living below the poverty line. One in three single women over 60 are living below the poverty line. Now you may or not be aware of this, but divorce is on the increase in this great country of ours, Australia. And divorce is on the increase more so than ever in a particular age bracket. And that age bracket is in couples between the ages of 50 to 60. Now, it's a little bit of a concern to me because I'm in that age bracket. I'm actually 53 years old. But nonetheless, divorce is on the increase for people between the ages of 50 and 60. So more and more single men over the age of 60 are finding themselves single and they're finding themselves in incredibly financial hardship situations. Now one of the biggest causes for divorce in people of any time, but particularly in that bracket of life is around financial stress. Financial stress causes all sorts of things. Of course it causes dis ease or disease, if you like. Any stress causes that. So there are a couple of things I want to want you to consider. That 76% of Australians living below will retire on $20,000 a year or less. And one in three single women over the age of 60 are living below the poverty line. Now the third statistic I want to share with you is from Morgan Stanley. Now, have you heard of Morgan Stanley? Does anybody know who Morgan Stanley is? So Morgan Stanley, look, they're an investment bank, if you like. They are, would be, say, arguably the largest investment institution in the world because they manage $2.3 trillion. $2.3 trillion. Now how much money is $2.3 trillion? It's a lot. Now I want to play a little game because $2.3 trillion is a sum of money that most of us just cannot picture. So I have here in front of me a $100 note. It's a real genuine Australian $100 note. Now here's the game. I'm going to ask three questions and try not to use Mr. Google. But anyway, going to ask you three questions. And if you get all three questions correct, I will personally send you this hundred dollar bill. Literally I will Send you or we'll get offline and we'll get your address. And I will. Not only that, I'll actually give it to you in a copy of my international best selling book, elevate your results. I'll stick it chapter here in the chapter there and I'll send you $100. But you got to get the three questions. So who wants to play along? You want to play along? Why not? Why not? Nothing else to do on a Tuesday night. Play along and win $100. Okay, here's the first question. If I had a million dollars, and that, that million dollars was a pile of $100 notes, in other words, if I had, if I had $100 notes, as in a pile and it got to a million dollars, how high would the pile be? We're talking a few centimeters, a few meters. So have a think. Put the answer in the chat box. Put the answer in the chat box. A million dollars of $100 notes stacked on top of each other. Just how high would that pile be? Gonna give you another 5, 4. We've got navards coming at 1.5 meters. 3, 2, 1. Let's have a look. We've got a navit at 1.5, weighted a meter SW at 10 inches, which is 33ish centimeters. No, 22 centimeters. And Thurston's. Come on a meter. Okay, see, we got, we have got at the moment, Wade and Thurston are in the running to win a hundred dollars. Because you're quite correct. A hundred dollar notes. A million dollars is about a meter. It's about, it's about as high as the back of my chair. You just can't see. That's what, that's what it. A million dollars is. All right, now you can play along anyway because it might end up being a two out of three. We'll see. Here's the next question. Here is the next question. If I had. Sorry, didn't mean to do that. If we, if I had a billion dollars, a hundred dollar notes going up to a billion dollars, how high would that stack be? A billion dollars and a hundred dollar notes, how high would that actually. How high? We have a kilometer from Wade because Wade's got a bit of help over there. Two. Two brains for the price of one. It looks like we got a thousand. Yep, we got a kilometer. We got a thousand meters. Okay, I tell you what, you tell you what we've got here. It's actually, it's. Look, I'll, I'll give you that on a Kilometer. Hopefully you can see this picture of the Burj Khalifa. This is, look, allegedly the tallest building in the world. So visually, I want you to this that this building is just under a kilometer high. You would need to have $100 notes all the way up, all the way up, higher than the Burj Khalifa to get to a billion dollars. Now that's just a staggering amount. Can you imagine that? A hundred dollars all the way out there. Okay, now the final question. The final question. And I'll tell you the results at the end. Now, for this one, to get it correct, I think I'd like the answer to be within the nearest $10 million. Is that okay? Within the nearest 10 million. And here's the question for you. How high would $100 notes have to go to get to be a trillion dollars? How high would we need to go to get to a trillion dollars? I'm giving out a 5, 4, 3, 2, 1. We've got a thousand kilometers. Now, I did say. I'll let you do one more guess because I said I did want to get it to the nearest 10 million. So you can't do a rounded to a thousand. I want to. I want you to have a good. Have a good guess here. A good guess, like a distinct number guess. Can you guess again? Guess again. If you like, you'll do a thousand and something. A thousand and something and something to get to 10 million. All right, we go. There we go. 10, 79, 1,000, 7. Okay, okay, okay, okay. Right. Well, look, I'll tell you what it is. I should tell you. This is a picture of the International Space Station. So the International Space Station. This the International Space Station above the Earth. Now, to get to a trillion dollars, you can see here, the space station is 400km high. So you have to go two and a half times up and down to the International Space Station and you. Actually, it's 10, 15 kilometers and 400 meters. 10, 15 kilometers and 400 meters. So I'm sorry, I don't think anybody's within 10 million because 10 million is 10 meters. So I'm sorry, thank you for playing along anyway. But I get to keep my hundred dollars, which is always nice for me. First rule of investing from Warren Buffett, don't lose money. So thank you, Mr. Warren Buffett. I get to keep my money. But the point I'm trying to make is a trillion dollars is 10, 15 kilometers and 400 meters worth of $100 notes. It's ridiculous amount of money. And Morgan Stanley managed $2.3 trillion. Now, the Australian stock market in its entirety is about 1 point. What used to be 1.6. It's probably still. It dropped, it's about 1.5 probably today, 1.5 trillion. So it's more than almost double the Australian stock market point. Out of all this I'm trying to get to is when Morgan Stanley make a comment, I pay attention because I think you've got to be pretty clever to manage that amount of money. I hope that's making sense. And I've been fortunate enough to meet Nathan, who's the head of, head of economics for Morgan Stanley here in Australia. And I pay attention to them now. Recently, Morgan Stanley made this comment specifically about Australia and it's this, that globally, Australia has the highest or near highest levels of household debt across most measures. Globally, Australia has the highest or near highest levels of household debt across most measures. Our debts are insane globally. So there are statistics. 76% of us are going to retire on less than 400 bucks a week. One in three single women over the age of 60, they're single, living below the poverty line and our debts amongst the highest in the world. But I want you to get this, that for the number of years I've been doing this and the hundreds and hundreds of Australians I met in the thousands of conversations, when I draw some diagrams, some of which I'm going to be drawing tonight, and I start coaching people and getting them on track, the most common comment back is, Dave, we just weren't taught this at school. We just weren't taught this at school. And you're right, you weren't. So whoever taught you how to do these things? So tonight, welcome to the School of Dave and hope you have a bit of fun. I know that I will be. A little word of warning. Sometimes I accidentally, if I get a bit serious, I get a bit monotone, sometimes I get a bit overexcited and talk too fast. And there will be the occasional dad joke. So that's the School of Dave for you. But nonetheless, hope you get some good knowledge and content out of it as well. You're at an event called the Financial Freedom Formula. And what I'd like to suggest to you is two overarching concepts to that. You simply need to learn how to master your money and then you need to grow your wealth. Why do you need to master your money? Well, pretty simple. You need to master your money or you will become a slave. You need to master your money or you will become its slave. Now that might be a bit of a Harsh call. And I get that it's not necessarily a very nice analogy between master and slave, but I need you to consider this with the relationship between a master and a slave. Who gets to sit around at home and do nothing and who goes out to do all the work. Does the master get to sit around or the slave get to sit around? With the answer in the chat box, who gets to sit around and do nothing? Who goes to do the work? Yeah, I think you can work it out. The master gets to sit at home and do nothing. The slave goes out to do the work. Now, when it comes to your relationship with your money, now, whether you're aware of this, you actually do have a relationship to your money. Ideally, we want to head towards an attraction, a level of appreciation, a relationship, if you like, of appreciation with money. Because on a side note, in life, whatever we appreciate, in turn, appreciates. So if we want our money to appreciate, we need to learn to appreciate it. It's a bit of a deeper conversation for another day. But no matter what, you have a relationship with your money. Now, with you and your money, who is the master and who is the slave? Do you go out and work for money or does money go out and work for you? So you need to master your money or you will become a slave. Another way of considering is this. You need to learn to control your money or it will control you. Now, what do I mean by that? Look, if you don't control your money, your money will control you or dictate to you if you like certain things. It will control or dictate where you live. It will control and dictate what sort of holidays you have. It will control and dictate to you what sort of school your kids get to go to, what sort of cars you drive, whether you can go out for dinner, when you go out to dinner, what you can order. So you need to learn to control your money or it will control you. So they're the overarching concepts that sort of underlie this presentation today. So you need to master your money or will control you. But really, what? Today, to put in a positive context, you need to master your money to grow your wealth. So you want financial freedom. Sure, you need to master your money and grow your wealth. I'm going to show you now the four steps that you need to follow. And step one is pretty simple. The first step is you need to have a financial freedom vision. Might write that down near the financial freedom freedom vision. So what's a financial freedom vision? Look, I know you Have a vision of your future. Whatever vision you have for your future, I don't know what it is, it may, it may be a bit of a vague one, it might be crystal clear, but, but most people have this thing of look, someday I'll do these things, see if any of these things resonate for you. That someday I'll have a holiday or maybe a big party holiday, upgrade my house. Or maybe I'll get to, you know, maybe upgrade my car or get that fancy car I've always wanted. Maybe I'll have more time to spend with the people that I love. Maybe I'll be able to quit my job. Maybe I'll be able to start a dream career, something completely different. Or maybe I just have more free time to do what I want to do with the people that I love. Or maybe I'll get to that stage of being able to volunteer or give back. So you've got this vision of someday I'll be doing these things. Someday I'll now with a bit of a cheeky little sneaky play on words or you think that someday isle because your future is a destination. Or do you consider that the someday isle is in fact an aisle in terms of an island, it's a destination. Now, I don't know what destination you've got in mind. Is it this big party island kind of thing or a cruisy one or relaxed on a holiday? Either way, your future is a destination. It's a destination. Your future is coming whether you like it or not. You are approaching your future. It's a destination that we're all heading towards. So if that's the case, you better get pretty clear on where you're heading. Because there is nothing worse almost in life. I'd say to you, ending up at the end of your life and that future that you thought you're heading to and going, I don't like where I am. I don't like where I am. So my suggestion would be let's get pretty clear on where you're heading. That is why you need to have a financial freedom vision. The financial freedom vision just helps you get clear, gets clarity. Now there's three parts to it. There's a lifestyle vision, there is a cash flow vision, and you need to have a debt free vision. So if you want to know the three parts you need a lifestyle vision, a cash flow vision, a debt free vision. I'll go into some more detail of those. But there's some things that get in the way. There are three things that get in the Way. Now, up on the screen here, you can probably see some of these celebrities I've shown before that you might recognize someone. They've got Rihanna and Elon Musk, the Rock, Hugh Jackman. You know, there's all these famous people and they have all done incredible things with their lives. But I'm here to tell you, every single one of those people that I just showed you at some stage has come across one or more of these three blocks that I'm going to tell you about. And these three blocks are this. We all have these things called limiting beliefs, trapped emotions and conflicted values. Now I'll talk about the first one, limiting belief. What is a limiting belief? Well, it's quite simply, it's any belief that we have up here that limits us. Or in other words, it's a belief we have that holds us back. We all have them, we're all human beings. And we're going to hear from Hugh Jackman a little bit later on as well. What his was, his take on it is we all have these things that hold us back. Now, when it comes to your money, when it comes to your wealth, just put our answers in the chat box, if you don't mind. What do you think some of the common limiting beliefs are around money, about wealth? What do you think some of the limiting beliefs are? All sorts of them. I'm too old, I'm too young, I pay too much tax, I don't earn enough money. I'm married, I'm not married, I've got kids, I don't have enough kids. Yeah, money is the root of all evil. There's all these sorts of. If I earn money, I'll be this sort of person or I can't start a business because I won't see my family, you name it. There are just lots and lots of beliefs that we have that hold us back. And you know what they are? It's a load of bs, which stands for belief systems. Now, these are some of the things that get in the way and we just need to get rid of them. And that first one is, Yep, money is for materialists. All these ideas and beliefs that we have that hold us back. The first one is limiting beliefs. The second one is trapped emotions. What are trapped emotions? Well, they're emotions that we carry. Then hang on to that again. Trap us or hold us back. Now, when it comes to money, can you guess what one of the biggest emotions is that holds us back about money? And it begins with F and ends with ear. It's fear off a Lot of people, it's fear. There's other ones as well. Insecurity, not being worthy, those sorts of emotions as well. But fear, it's either fear of making a mistake or fear of missing out. So it's another one of these things we just need to work through and get, get rid of. And the third one is conflicted values. So conflicted values are when we have two things that we like and we can only see that they clash with each other. Now, what do I mean? What do I mean by that? Well, let's say, for example, let's say, for example, you wanted to go and get a nice new shiny car. So you really value the idea of getting a shiny car, but at the same time you're scared that if you get this fancy shiny car that someone will scratch the paintwork. And all you do is sit around at home on the weekends and watch Netflix. Can you see there's a conflict of values? You want the car, you're worried that someone will steal it or scratch it, but you're doing nothing about it. You're not in alignment. There's all these conflicted values with things all the time. It's just an example about the car, which is probably not a great example, given that this is about wealth and cars generally go down in value. But the point I'm trying to make of there's all sorts of things we have that are important to us. And often we, we think, if I do this, I can't do this. And we get stuck, we procrastinate, we get overwhelmed, we get stressed and we don't do anything. So these are some of the things that just get in our way. So you need a financial freedom vision, but you need to get rid of those things. So. So financial freedom vision. The first part of a financial vision is having a lifestyle vision. What is a lifestyle vision? Pretty simple. It's the vision that you have for the lifestyle that you would like to have in the chat box, if you don't mind, in the future, would you like your lifestyle to be the same? Would you like your lifestyle to be better, or would you like it to be worse? They put S for same, B for better, W for worse. Would you like in the future your lifestyle to be the better, the same, or worse? Look, most of us, at least, most of us at least want it to be the same, but guess what? You didn't have a vision, a crystal clear vision of how to get your lifestyle to be the same in the future, but to get it to be the same in the future, then let's make sure it's not worse, let's try and get the same and let's head towards how can we actually make this better. But the key to this is actually fully understanding what your values are. See, as human beings, we all value slightly different things. And not only that, we have a hierarchy of things that we value. For example, you might like spending time with your family, you might also like going out with friends, but you might also like traveling. Now there's a hierarchy and sometimes you're faced with a conflicting or a confusing view. I want to spend time with my family, but my friends have asked me are out want to spend time with my family. But there's a mates trip or a friend's trip or a girls night coming up on holiday and we're confused and we can't work them out. They're our values and we have a hierarchy of them. Now when we go through our lifestyle, what we often find is what we think we want isn't actually the thing we need. I'll try and say that again. When it comes to our lifestyle, we go through life often with the thing that we think we want isn't actually correct. It's the thing that we need, something else that will satisfy our needs. I want to talk about this thing called money and put it as an example. See, we often want money. In fact, just about everyone said yes when said you want more money. But money in itself, it actually doesn't do anything thing. It's this funny sort of flappy bit of plasticky funny money stuff. So money itself doesn't do anything. So it's what the money represents. And for most of us, the money either lets us be something, it lets us do something, or it lets us have something. Does that make sense? So it's not the money itself, it's what the money lets us be or what the money lets us do or what the money lets us have. So sometimes we get all hung up on the money. It's actually we just want to be something or be someone. We just want to have some things, we want to do some things and we really need to. What I'm trying to suggest is you really need to understand your values and what's most important to you just to make sure you're chasing your dream and you're not chasing someone else's dream. Now there's a layer behind that which I don't have a great deal of time to go into. It's not anything we want to be, do or have, but it's actually the emotion or the, the feeling that we get from, from having that thing and. Forgive me, I'm going to tell you a story about me and my, my passion for kite surfing. See, I've been a surfer all my life living in Perth and. But I'm now quite a passionate kite surfer. And when I first got into kite surfing I, I got a bit obsessed with buying new kites all the time. Now the way Jasmine I structure our money is we've got various accounts called no question asked accounts which I probably don't have time to get into, but we might later nonetheless. I started getting frustrated because I wanted to buy a new kite. And what I found was every time I bought a new kite I got excited so I needed the money to help me buy the kite. So I started focusing on the kite and when there was enough money to buy a kite, I'd get annoyed. But then I found that I wanted, after a little while, not long, I want to get another kite, then another kite, buy, swap, trade, whatever. And then finally, it was a couple of years ago now. I was up north at this place called Exmouth, beautiful part of the northwest coast of Australia. All the whale sharks are up there and turtles, et cetera. And I was out there kite surfing with, with some friends and we were out about a kilometer off, off to sea. It was amazing. There was seven of us out there about a kilometer off off the shore. We're doing this long, long trip down just, just on our, with kites and surfboards. It was, for me it was exciting. Might be scary or whatever for you, but that it was, it was fun for me. We're dodging turtles and seeing manta rays and there I was out there in the middle of the ocean with these guys that suddenly hit me. What I love about kite surfing isn't necessarily buying more kites, it's being out there in the ocean and having this sense of freedom because I'm out there in the elements and just being exhilarated. This incredible sense of freedom. And I looked up and I was flying a four year old kite. It wasn't anything about the kite, it was about the experience or the emotions, wasn't about the money. What I really wanted to do, the money let me get the kite which let me have the experience which gave me a sense of freedom. I also looked around and realized with a bunch of guys that were great and we hit the beach and we had a beer on the beach. So for me also the important thing was having a sense of belonging. So the Money is the thing that let me have the kite. What the kite let me do was experience freedom and belonging. So when it comes to you and you really figuring out your lifestyle vision, if you haven't worked out your values, it's very, very risky because it's just possible that you are chasing the wrong dream. And I hope that makes sense. I'd just like that to sink in a bit. Now, the second part of the financial freedom formula, the lifestyle vision, is the CA flow vision. Now I don't know about you, but personally people ask me this question over and over again. The question is this, Dave, how much do I need to retire? And the answer is the same. I don't know. And I don't know because I don't know what your lifestyle vision is. I can tell you this. Once you know your lifestyle vision is, it's not that complicated to work out what your cash flow vision is, how much you actually need only today, but moving forward so you continually enjoy that lifestyle. So that's why it's in order. You've got to have your lifestyle vision. Then we can work out your cash flow vision. Now the third part to having a financial freedom vision is also having this thing called a debt free vision. What's a debt free vision? It's pretty simple, It's a pretty clear vision that you have. It is a day with a date written down on some mathematical equations where you are debt free. Now, I don't know where you are in relation to that. You may have a massive mortgage, you may be at the beginning of your journey, but it's so important to have a day with a date written down where you know you are debt free. And as someone who is very fortunate enough to be debt free at the age of 38, I'm here to tell you this. There is almost no greater sense of freedom you will experience apart from that first time you realize you are debt free and own your own home. And it's not as complicated as you think. There was a Lady sue that came to one of my events some time ago and it's fairly simple. Money does not have to be complicated, but there's a process we went through and she did a little bit of number crunching and I guided a coach through it. She said, dave, you mean if I do that, that and that, that's the day? And yeah, it can be as simple as that. So some of you might kick that idea out. It's, it's just here to suggest to you that if you want to financial, you know, freedom the first step of it is to have a financial freedom vision. And these are the three parts you need to have your lifestyle vision, your cash flow vision and your debt free vision now. And you need to get clear on where you're heading now. How do you get clarity? Hope you can see on the, on the slides here there's two identical glasses of water and the one on the left is kind of murky and the one on the right over here is pretty clear. In other words, it's got clarity. So just put the answer in the chat box if you like. How do you get clarity in a glass of water? How do you get clarity in a glass of water? It's about putting more and more stuff in. It's about making things more and more complicated, more convoluted, trying more and more different things. It's a pretty simple answer. How do you get clarity? You need to remove some stuff. You just need to remove some stuff, no matter what it is. And these are stuff when it comes to us, you need to remove. And, and I showed you these people before. These are all these famous people. I'm here to tell you every single one of these people here faced some sort of hardship, some sort of disappointment, some sort of devastating something along the way. And you reckon they had stuff to get rid of? Yeah, they did. But I want you to hear this little snapshot from Hugh Jackman. See Hugh Jackman, this is Australian icon of ours. I was very fortunate to study with him many, many years ago. But you may or may not know this, that when Hugh, I think was about 8 years old, living in Sydney, his mum just up and left, just left him and the dad and five kids, I think it was in Sydney. And so, yeah, then Hugh just talks a little about this. You know, he's obviously gone on to do incredible things, but this is what Hugh has to say. Just listen carefully. Family, Parents split up when I was young. And I think for many years I carried a doubt about whether there was some kind of wound or damage that would frame my entire life. And all the decisions I make. And no matter what, no matter how I handle that, is it always there? Is it just something I have to kind of manage, you know, like you would manage an injury. I've always got a bad knee. No, no, no, sure. Something bad happens, something bad happened. Everybody on the planet, I don't care who you are, something bad has happened to you. But if you continue to tell that story to yourself that that is who you are, it will continue to be true that damage will Stay for the rest of your life. But it doesn't have to be that way. You don't have to spend years and years and years and years in therapy. In one hour I can get rid of that. And it's pretty powerful. Family. Oops. Kind of if you got that, you said, said muted myself. So I don't know if you got that. He said, look, we've all got stuff. But he said, you don't have to be like that in one hour, you can get rid of it. Now, I know that Hugh says that because I know something about Hughes that he's had a coach for years and years and years. So he's just know some of these techniques that you can do to get it out. So that's what I want to suggest to you, that you want, you want to get clarity. You just got to actually get rid of some stuff. You just need to get rid of some stuff to get, get clarity. I mean, Wade says another way you need to need to filter it out, but yeah, you need to remove stuff. It's as simple as that. And look, this is a guy I've been working with for a while, Jason, Young fella. He says, look, before meeting day, my progress was pretty slow, but just goes on to say, look, I've got a lot more clarity and more importantly, got to take action. And he's just on track to get his investment property and doing this stuff. So it's pretty cool. I don't know if you ever thought, look, is there in fact a pattern for success? Is there a pattern for success? Look, don't know if you've seen this guy before, Tony Robbins, he says, look, if you want to be successful, find someone who's achieved the results you want and model what they do, and you'll achieve the same result. So there seems to be a pattern for this thing. There's a pattern for that. Is there a formula for wealth? Well, I'd like to suggest to you that there is. It's called the financial freedom Formula. I'm going to tell you about step two. If you want to master your money and grow your wealth, we're going to look at step two. So as a recap, if you want financial freedom, I'm saying you need to master your money and grow your wealth. That's what you need to do. And we look at step one, which is lifestyle vision. Step two is you need to understand the financial freedom pillars. So what are the financial freedom pillars? There are in fact five pillars to wealth, but something always goes wrong. Now, at this Point in time. Please grab a pen and some paper and ideally, if it's a multicoloured one, play along with this. Now, I'm going to do one of my little works of art over here behind me to give the back of my head while we do this and hopefully you can still hear what I'm saying Now, five pillars to wealth. The first pillar begins with Inc and ends with and it is income. Told you. There's some dad jokes coming. So their first pillar is income. Second pillar to wealth begins with cash, ends with flow. And it is cash flow, Makes you get high cash flow. Now, the third pillar to wealth is something if we have begins with D, ends with et and we have it, we want to try and get it down. And it's debt. Okay, we've got income, cash flow. Now we have debt. Fourth, political wealth is something that we pay. We don't like it, begins with T, ends with acts. We want to pay less of it. It's tax. And the fifth letter. Wealth begins with F and ends with future. And we probably want to have some freedom in it and is of course our future. But I would like to suggest to you that they are the five pillars to wealth that we need to start to master now. Generally, generally, this is kind of what we think. And see if you agree with this. Generally, we kind of think, look, if I start increasing my income, I'll probably have more cash flow. Now if I've got more cash flow, I can get my debts down. I've got to pay a bit more tax, but surely my future will be okay. That's usually what we think. If I get more income, get more cash flow, get my debts down, my future will go to go pay more tax. Generally, what we think. However, I am here to suggest to you that this is actually more in reality, what tends to happen, see, as we increase our income. Put it in the answer in the chat box, if you don't mind. What is 100% guaranteed the next thing to go up as we increase our income? Yep, SW and Thurston, they're onto it. It's tax. Income equals tax. That's why we call it income tax. So as the income goes up, our tax position goes up. Now, what's the second thing that tends to go up? Up as our income goes up? Can you guess? In the chat box, what's the second thing that tends to go up? It's expenditure. Expenditure, generally speaking, is under the times of debt. It's the Harvey Norman car. The bigger car, the bigger house, the after pay, the Whatever. Our debts or expenditure also tends to go up. Now let me ask you this. If it comes up, but we're paying more tax and our debts have also gone up, what tends to happen to our cash flow, it often in fact goes down and it just confuses the heck of us. We kind of go, but I'm earning more money and there should be more, but there's just not. Not. And what tends to happen is we get stressed and confused. We go round and round and round. But tell you what we ignore is this thing called our future. And that stresses us. Deep down, we know we're not putting the right things in place that are heading us to a future that we're going to be excited about or lit up about and living the life we love. And we get confused and we stress out. How do we alleviate our stress? Most of us, we spend more money on the things that we think we get enjoyment from. More cars, more going out, more Netflix, more food, whatever. And it goes round and round. And our debts get out of control, we get less cash flow, so we work even harder on our income. Then we leave out our stress by buying more, spending more, and we end up in this, this rat race cycle. It just goes round and round and we're literally spinning our wheels. Literally spinning our wheels. And as our future gets closer and closer and closer, unfortunately we are faced with these dreaded three letters, the big W, T, the. Which of course stands for we have totally failed. We have totally failed. Now, this is my big promise. This is my big promise to you. I'm going to show you a different example of this diagram or we can start turning this WTF from We have totally failed to wear a tasting freedom. Would you like me to show you how? Glad you said yes. And as they used to say on some of the shows I used to watch when I was a kid, here's one I prepared earlier. Now, this time, and this is the one you really need to follow along to. This time, we're going to do something ever so slightly different this time as our income goes up. And I'm pretty sure earlier I made the distinction. Oop, just lost my pen lid and went rolling away. Forgive me. Well, I made the distinction between income and cash flow. Income is where the money comes in. Cash flows. Where the cash flows. Now I am. I'm a big fan, don't get me wrong, I'm a big fan of people increasing their income. Not only increasing their income, but in fact generating multiple income strengths that are my private client works, my coaching clients, Et cetera, that come through the eight week bulletproof wealth. And whatever they do, it's increasing your income and developing multiple income strengths, which I'll explain in a moment. Moment. So, yeah, I'm all about increasing your income. But this time, as we increase our income, we just want to pay a percentage, or put a percentage if you like, towards our future. Straight away a percentage to our future. And at the same time, whatever debts we have, if they're personal debts, credit card debts, home loan debts, or even investment debts, we just want to start siphoning some over to get our debts down. Now let me ask you this. If your debts are going down and you're already putting some money towards your future, but is your debt going down also help your future? I'd say yes, because in the future you will have no debt. So by paying our debts down, we are also helping our future. Now we've got some income going to our future, our debts are also helping our future. Is it time to have a bit of a think about what we're going to do with that? And the answer is yes. Now, there's three main categories we then need to start focusing on. The three categories are investment categories, if you like. Now there's multiple asset classes. It could be argued there's nine. There's probably more than that. But for today's purposes, I'm just breaking them down into three asset classes that you need to start paying attention to. The first one is we need to get. Getting some IPAs. Need to get some IPAs. You might want to write that down. Some IPAs. What IPAs. IPAs are investment producing assets. Investment, sorry, income producing assets. There's investment producing assets. Sorry, income producing assets. Sorry, to do with income. Income producing assets. They are assets that are predominantly designed to produce income. They may do other things as well, but predominantly designed to produce income. And there's many of them. I don't want to go into the details. They could be, look, it could be business, could be shares, it could be property, it could be term deposit, all sorts of things. However, the point being it's an asset that is predominantly designed to produce income. Got it. That's the first time. Now if we had then some of these income producing assets in our future, you think that also might in fact improving our cash flow? The answer is yes. We started to use the concept of leverage and opm or other people's money maybe, or just the rules of leverage and compound interest and things like. I'll talk about Einstein later, the eighth wonder of the world. So income produced assets can help us with our cash flow. What do we do with our cash flow? We turn that around and also then start to eliminate our debt. Now, I don't know if you can see here, but now we have a cycle of. By kicking off the cycle, getting some IPAs, we start to get a little snowball cycle. Little snowball cycle. Why I call a snowball cycle if the concept of a snowball rolling down a snowy mountain. It starts small, but as it rolls down and down and down, it grows and grows just because it's rolling. So we need to get into one of these cycles, not the rat race cycle I was talking about earlier. Now once we get to that stage, we need to start thinking about the other type of asset class to look at, which are CGAs. So what are CGAs are the second type of asset class we need to look at. What are CGAs? They are capital growth assets. CGA, capital growth asset. Simply put, it's an asset that is predominantly designed to grow in value. Capital growth just means growing in value. Fancy term growing in value. Distinction to be made. As we go through life, we need to develop two things. We need to always look at income producing assets and capital growth assets. Why? We always need income. To the day we die, we will need income coming in. We will need money coming in. But money coming in on its own is not enough. We also need to grow our wealth. Now over my 25 years or so, I've met a lot of people that have got a lot of wealth but no income. I also met a lot of people got a very high income but with no wealth. So we need to draw a line of distinction and say you need both. You need to generate income and grow wealth. Hence these two things. Okay, now the third asset class we need to look at are called WPAs. Now WPAs are called wealth protecting assets. Wealth protecting assets, predominantly. Just any asset that protects your wealth. Now it could be structures, it could be systems, it could be things like, you know, gold or whatever, but there's just assets that are predominantly designed to protect your wealth. Certainly as we go through our journey and our stage, the closer we get to that retirement, that future, we're free. We want to actually preserve money. We want to preserve capital as a technical term. But Warren Buffett, the most successful investor arguably of all time, he said, look, first rule of investing is don't lose money. So how do you got to protect it? What's his second rule of investing? He says don't forget rule number one. So don't Lose money. Now, do you think there might be some ways to look at income producing assets, capital growth assets and wealth protecting assets that the wealthy know about using these pretty clever, fancy, sometimes slightly more complicated laws around us to also reduce tax? And the answer is 100%. So this is what we can start looking at doing. We can get this cycle so our money starts to work for us by developing these things at the same time pay less tax. So they are the five pillars to wealth that you need to start to understand. Now, it can look a little bit confusing if you sort of, it's kind of posing, but I'm no good with money. Well, this is a very big concept at the moment. We need to put it into a system. Am I put into a system? Yes. That's what Vijay had to say. He used to work for the banks and he says, look, I learned more from Dave in just 30 minutes in my entire career. I'm amazed by how profoundly and simply Dave makes mastering your money. Look, he says it's a great system. You need to have a system. Folks, I hope you can see this picture on the screen here. It's not a mistake. It's a toothbrush. Why have I got a pitch for toothbrush on the page? Well, pretty simple. When you brush your teeth, do you use this hand or this hand? Do you brush your teeth in the same room or different rooms every day? Do you do it over the sink or do you walk around the house? Do you put the water on first, then the toothpaste or the toothpaste, then the water? Whatever you do, there's a pretty good chance you pretty much brush your teeth almost identical. Why? Because you have just developed a super simple system to brush your teeth. See, anything that's disorganized doesn't get done pictures. If your toothbrush was in one room and your toothpaste was in another room and the sink was in another room, it's chaos. But it's a thing as simple as brushing your teeth and get systemized. It's just super fun and super simple. Super simple and easy. In fact, if there's a super simple system, work. Yes, it, because it lets you. It helps us teach our kids how to brush their teeth. So if we can put systems in place for brushing teeth, can you do it for other things as well? 100%. This is what Dina had to say, but she was a pretty experienced investor when she met me and she said, dave, I wanted to thank you. Look, she goes on to say how many investment properties she'd done, but she said, I've attended many workshops. This is by far the best explained system, but how to do it safely, why it works and how to create a solid system for investors. So we've been covering a lot so far. Big picture. Again, you want financial freedom. You want to master your money and grow your wealth. The first stage to that is you need to have a financial freedom vision with a lifestyle vision, a cash flow vision and a debt free vision. You need to understand the financial freedom pillars. Now, the third part of this you need is a financial freedom strategy. Now why do you need a strategy? Because I'm here to tell you this in almost any area of your life, but also particularly with or particularly with finance, but many areas of life, strategy wins. Talent doesn't always win. Intelligence doesn't always win. It's strategy. Strategy wins. War. Strategy wins. Politics. Strategy wins. Sport games. Strategy, strategy, strategy. So strategy wins in the game of finance and wealth creation as well. And there's three simple golden rules, rules that you need to follow. And you might also want to write these down. Oh, look, before I do that, actually just wanted to check in with you. I've been yabbering on for ages. Look, are you getting some value out of this? I'll take a support, just put a V. Let's put a V for value. If you're getting some, some value added is so far. So I'm not talking to people that have fallen asleep. Thank you. Thank you. Okay, thank you, thank you, thank you. All right, that's all I need to keep going. If you have me keep going, I shall keep going too. So the three golden rules, Please write these down. First golden rule is to work hard to earn your money. Work hard to earn your money. Now why do you need to work hard to earn your money? It's pretty simple. I do not believe in get rich quick schemes or scams. To my world, they do not exist. They do not work. And the underlying thing about it is, if you do not believe you have earned the money, you will not believe that you deserve the money. And if you do not believe that you deserve the money, you will in a short space of time do whatever you can to lose the money. Let me say that again. If you do not earn the money money, you will not feel that you deserve the money. And if you do not feel as though you deserve the money, in a short space of time, you will do whatever you can to lose the money. There is evidence in almost every continent on the world that has a lottery of people that win an incredible amount of money. And within 18 months, months are in a worse financial situation. Just Google it. If we just get a large sum of money that we don't feel we deserve, we just get rid of it. So rule number one, work hard to earn your money. Second rule, work hard to keep your money. As Warren Buffett says, you know, first rule of investing, don't lose money. That's the second rule of how to keep it. Work hard to keep your money. Don't let it slip through your fingers. Have a solid strategy to do something. It was as simple as putting a little bit towards your future. So work hard to earn your money. Work hard to keep your money. But this is the third one in the power. Get your money to work hard for you. You get your money to work hard for you. And that is the underlying thing to, of course, no matter how you're doing, let's just be safe. Let's just be safe about it. Now, how does this work? There's a little bit beyond the five pillars to wealth and the two U's. So what you need to understand that there are in fact two U's that you can use to grow your wealth. So. So when we're talking about developing a strategy, this is some of the things that people do. So over here, there is you. That was terrible. Y for you. Forgive me, Scrappy. That's a you. You have a real you over here. Now that I'm going to annoy me. Sorry, but that's a you making it worse. Aren't I you. That's you over there. There's the real you. There's the real you, thirsted. There's the you world way. There's Matthias, there's Navid, et cetera. There's the real you sitting here. There's now probably in your world. These are generally the three things we do. We probably got some sort of money sitting somewhere in some sort of cash account, maybe got some money. The second thing, if we don't have it, we're probably heading towards getting it at least. And it's this thing that begins with P and ends with rocketty. And that's my universal symbol for property. And the third thing we may have is something that goes up and down. And that's my universal symbol for the share market, or as I've been calling it recently, the scare market. That's what's been going on. So that's what we can do. There is, there is the real you, which you can do to start growing your wealth. It's a money property in the Scare market. But there's a second you and the second you that you can use to grow your wealth is kind of cool. In fact, it's got some superpowers. That's why I call it. There was also the super you. Okay, so we've got the super you, the super you. Now the super U, of course that I'm currently referring to is of course the most neglected thing, the most misunderstood thing, the most thing that people think is boring. That is of course your super now. But there's some pretty super cool things that you can do with your super, just with a few little tweaks and tricks. However, generally speaking, people in their super may have something that looks a little bit like this with some cash and then possibly whether or not they've got any idea what's going on with it, they've probably got some sort of exposure to the scare market. Now whether that's in, I don't know what it would be and you might not even know yourself. It's predominantly probably in a managed fund of some sort. There's all sorts of other ways you can access other things very, very cost effectively, but you've probably got that, that. But in certain circumstances, at a minimum you can have some exposure to also in your super to have exposure to property. Now whether that's just exposure to property, actually directly buying a property, which there are options to do that I've helped multiple clients do, particularly buying through self and a super fund when it's correct and when it's safe. But that's generally understanding. I want you to understand this, there are two use that you can use to grow your wealth as you go through a strategy. This is something that people might do, they might do something like this. You might say, I've got this property look, and saving for your first home is not easy. It's tough, it's hard. But after a while, particularly if we use things called ADRs, as I described more accelerated debt reduction concepts, we get our debts down, the property goes up a bit. With this thing called equity, we may find that for no money down, we can get this property to buy another property. Now none of this is rocket science. If you've been to other events, you've probably seen something very similar. The difference is we want to make sure that they are completely safe and not related to each other. And for some people, that's it, that's all they want to do. And to be honest, if you know what your lifestyle vision is, if you get three things going over here and something like that you're very possibly done. Or you might get very, very fancy and eventually get this one in time if things are going well. And what I mean by going well is we have applied this concept. As our income goes up, we pay to our future, we get our debts down and generate cash flow. So we got this going on once, then we get it ongoing again, we might be able to get it going again. And look, if you get super fancy, you might end up doing it again, who knows? You get the idea it's using leverage other people's money. It's a bit of a strategy of how it looks. But this is the beginning of a strategy. Because what people don't talk about, what a lot of people don't realize, is that this thing over here, tax, the rules for tax in your real world are very different to the world of tax in the super world. Now let me, let me put it in this context. See, until the day you die, you will need some sort of income. You will need money coming in in. Now if you are in retirement and all you are doing is drawing on what we call a pension, your superannuation's gone to pension phase. Now, whether it's from your own superannuation or a little bit from the government as well, if you're drawing money from there, guess how much tax you pay? 0. Does that sound nice? Having money from your superannuation and maybe some government pension and paying no tax sounds nice to me. However, if you've gone and generated a whole lot of wealth and some income producing assets over here, even if you're retired with this income, how much tax do you pay? Who knows. But if you're earning whatever you're earning, the first $18,000 is tax free. After that you start paying tax all over again. So it's very possible if all you're doing is developing assets outside super, you will be doing tax returns until the day you die. So as part of the strategy, we need to have a look at and consider how can we get our assets from here over to here and while we're doing it again, pay less tax. Because here's the other thing. There's another thing called capital gains tax. If you've got one or two of these properties that go up in value and you sell it it, which you might want to do, if it's gone up in value, you may pay tax on that whole thing called capital gains tax. For example, if it goes up worth $200,000, you might be liable for another hundred grands worth. That's added to Your income, you might be liable for a whole lot of tax. Now that might push you into a different bracket. You might find you're paying 37 cents in the dollar tax, you might be paying 47 cents in the dollar tax. Who knows? If you've got property over here with your super unit goes up in value, guess how much capital gains tax you pay. 10%. So would you rather pay 47% tax or 10% tax? You don't have to answer that. It's a rhetorical question. The other thing is though, if you've got some value over here, whether it's in the scare market or property, and you sell down some assets in retirement, guess how much capital gains tax you pay? 0. 0. So hence we always need to understand the strategy in conjunction with the five pillars to wealth. So this is not financial advice. It's a concept of how you can start developing a strategy using the five pillars to wealth and the two U's. So that's what we've been talking about. Financial freedom vision, the financial freedom pillars and then of course, the financial freedom strategy. Now I'm just checking how we're going for time, see if I can squeeze through this one. So Einstein talked about this thing called the eighth wonder of the world. Does anybody actually know what Einstein said was the eighth wonder of the world? Look, it's. Einstein said this, he said, look, compound interest is the eighth wonder of the world. He who understands it, earns it and he who doesn't pays it. So in that context, look, who do you think understands compound interest the most? Is of course the banks. Look, I think I'm looking at the time I'm going to. You get the idea that I wanted to do this whole thing about, you know, income, you know, savings accounts and losing accounts and why the banks win. I just want to tell you know, that there's way, if you look, I, I'm just going to rip through it really quickly. Basically, savings accounts, losing accounts. No matter what, what income you earn, you earn interest in the saving account, you pay tax. There's ways to structure things. So maybe instead of earning 4% on a savings account and paying tax, you can earn 5% and pay no tax. But they're just some of the little hacks that we can do along the way. Because I'm just conscious of the time and I want to try and stick to the under 90 minutes. People say there's, I know, good money. This is Jeanette. Look, Jeanette is a self confessed no good with money person. Even Jeanette thoroughly recommends My sessions. But I do want to tell you this. It's the miracle. It's a little miracle. I'd rather spend a bit of time. It's a miracle of the saving safe versus the super safe because it does fall under the context of strategy. So I want you to imagine that you in fact actually have two safes. No, that's. We've done the picture there. We've got the two safes in your house. You actually have what I call a saving safe. And it's literally a safe. It's a safe where you might put money in. We actually have two of these. We've got a little bit of money, but Jasmine's jewelry in the safe. But you also have a second safe. It's called a super safe. Now, it's a super safe because it is super safe because it protects you from a few things. So literally it's a safe and then you have a super safe. Now the super safe, of course, is your superannuation. Again, I'm talking about. But it's super safe because it's not in your house. It's also super safe because backed and backed by the government up to a certain point. But it's also super safe because it protects you from someone that may want to access the money. And the person is ultimately protecting you from is yourself. Because money that goes into super is very difficult to get out again until later. The whole point is it's just getting it in our future. But I want you to picture this, that look, if you've got $2 and you just put $2 a week and you gotta go put it in your savings safe, okay? You give yourself two weeks off a year. So $2 a week. $2 a week. $2.00 a week. the end of the year, you basically got one of these things. Hundred dollars, okay? So I want you to imagine this. You got $100 in your saving safe. You put it in there, You've locked it away, the money's gone, okay? It's in there. End of the year, you go and open up your savings safe and you literally take out the hundred dollars. Simple math question. If I had $100 in there, I take $100 out, how much money should be left in there? Zero. Got it? There's nothing left. We now have this thing called choice because we have some money. But what we're going to do now is we're going to go put it around the spend. We're going to go put it. Remember this guy's talking about this super safe, so you Decide to put it in your super safe, which is actually putting it in your superannuation. But as you put it in, you put a little code in and you forget about it and you go ahead with life and do your tax return or whatever. And then you start to get your $2 for the next week, and you go to your savings safe safe, and you open up your savings safe, you go put your $2 in, and something weird, something really weird has happened because when you open up the safe, there's $32 in there. How can this be? And this is what I really want to try and get to you, that there's this miracle of the super safe, that the laws changed a little while ago, that if you actually take some of your savings and pay yourself by putting into your super and letting it know with a certain code that triggers the Australian tax office, you get tax back on it. Now, if you're earning 32 cents paying, sorry, 32 cents in the dollar tax, you put $100 in, you get $32 back. So you've paid yourself to get it in the future, and you get tax back. Now. If you do the same thing over again, you put your $2 a week, $2 a week into your saving safe, you end up at the end of the year having $132. You take that across, put it into your saving safe, end up with $39 back. Now, I don't get this, but you've actually just got a tax return on your tax return. It's got a tax return on your tax return. Now, does it only work with, with $100? Well, no, of course it works with, with. With a large sum of money as well. Plenty of people, my clients, we go through this. They, they end up putting $1,000 and getting $320 back a year. I have clients that actually save up deliberately now. Now put $200 a week aside to get to 10 grand, because they put 10 grand in, you're putting 10 grand a year into your super. How much better you think your future's looking? A lot. And on top of that, you get $3200 back for tax. See what I meant with this cycle? This cycle, I would have had more time to go into it, but there's just some really cool things that you can do with it. So really, that's just some of the concepts that you can play with. Strategy. And look, this is a guy, Phil, that came on board. He said, look, over the last seven years before me, he'd spent over ten grand with Three different financial planners who did very little. So in the first 90 minutes we did, we learned more and got more value about how to structure our money, grow our wealth and pay less tax. It was brilliant. But why am I passionate about what I do? That's me as a kid, that's me. But why am I passionate about what I do? Well, pretty simple. I was very fortunate when I was very young, you know, at a young age to buy a block of land. I bought my first block of land when I was 18 and, and really essentially, look, if you'd met me 25 years ago, you would have found me working as a high school chaplain, believe it or not, in the government school system, just trying to make a difference in the life of staff and students and their parents. And I found myself in a situation where I could buy my first house and I was not earning very much money. I was about 25 years old, living with mum and dad. So I bought this house and I got this debt and it just seemed really, really big to me. It seemed huge. But I got some advice from some people and the suggestion was I stay at home with mum and dad and I rented the property out. So I did that and I just threw every dollar I could at this debt and I just saw it go down, down and down. Then if about 10 years later you would have found me married to my beautiful wife Jasmine, with two kids and one on the way and we'd both been paying our money and throwing money into our debts and watched them go down, down and down. And we got a lot of advice for some people that were more experienced, a bit cleverer than us at the time and we'd be able to invest and our investments are just better to go up, up and up. And I remember being 38 years old, we just built this beautiful house in Karen up two story house with, you know, with the pool and theater and it's the house we still live in today. And with two kids and one away at 38 years old, we found ourselves in the ability to be debt free. And that gave us an incredible sense of freedom to really, for me to quit the chaplaincy and reinvent myself. You can see the diplomas behind me in finance and then literally getting certificated, certified by ASIC and then certified again international with the International Federation of Coaching for Results. Coaching and wealth Coaching, coaching. So it gave me my passion to help everyday Australians follow the same path of just finding out how to get debt free as quickly as possible. I developed this whole concept around the financial freedom gave Jasmine the really the ability to be free, to be the best mum she could. She just still loves the kids. They're still with us. We've got 19, 18 and 15 year olds now. And Jasmine just volunteers her time at the local primary schools with the most at risk kids developing, using, using her developmental psychology skills. And throughout the way, I've been very, very fortunate to have some mentors. This is one of the guy, Ben, he's actually the guy that he's worked with Dr. John Martini and Tony Robbins. And Ben is actually the guy that certified me in the results coach methodology as well. And very fortunate that we actually got to write a book together. He invited me to do a guest chapter with his book and that's me with Ben and his co founder Chad at a book launch in Sydney. So very, very lucky to have had some mentors along the way. And this quote I read earlier from Tony, if you want to be successful, find someone who's achieved the results you want, model what they do and you'll achieve the same results. And because of Ben's connections, if you can see this, this is the back cover. This is actually a real. I want to show you the picture. This is actually on the, on the back cover of the book, you can see there's a quote from, from Tony. Tony there. It's just, it's just kind of nice that we got this quote from Tony Robbins there on the back of the book, which is kind of fun. And, and then ultimately, I suppose the most fun thing about it for me is my little brag is that Ben asked me to go on his podcast and interviewed me. This is what he said about. I've known you for a long time and I know that everyone who interacts with you just in a very strange way seems to just make money. Like, it's just there's this bizarre correlation between people who meet you and people who sort their finances out and tend to generally just become wealthier. So I'm pretty excited about this podcast because, I mean, who doesn't want more money in their life? And I know that you're definitely the man that people should be searching out. So it's just kind of nice when your mentor says some nice things about you. What have we covered so far? We've covered a lot. I said at the beginning, if you want financial freedom, then there's, you know, you need to master your bunny and grow your wealth. But the first step is you got to have a financial freedom vision, which encompasses a lifestyle vision, a cash flow vision, and a Debt free vision. You need to conquer the financial freedom pillars which are on this crazy diagram behind me. They're not complicated, but they just need to be in a system. And then ultimately you need to work out what is your financial freedom strategy. How are you going to get there? Because strategy wins every single time. So look, I hope you've gotten some value out of this so far. I did mention there's a bit of a surprise bonus. It's nothing to sell. Bit of a bonus. But the final thing of course is if you want to master your money and grow your wealth, the final step to this is of course. Well, what's it, I just put this thing on the stage. I need to explain it in this context because you can probably guess the logo of this company. You've probably heard of this small company, it's called Google. Now you've probably heard of Google, they're pretty big beast these days. But there was a guy from Google. Google actually has a CEO or chief executive officer. And to answer the final piece of the puzzle, I think that this guy Eric Schmidt, who's the ex CEO of Google, actually answers the final piece of the puddle puzzle probably better than anybody else. See, so Eric, Eric Schmidt was, sorry, interviewed on this interview and people said, what's some of the best advice you've ever given? And I'll let Eric explain. What's the best advice that he ever got? So just listen to this. The best advice I ever got from the CEO of Google. Over the years, I've received so many different kinds of advice, I don't know where to start. One that comes to mind is to have a coach. Our board member in 2002, John Doerr, said, you need a coach. And I said, well, I don't need to coach. I'm an established CEO. Why would I need a coach? Is something wrong? No, you need a coach. Everybody needs a coach. So Bill Campbell became my coach and has served Google very well. Every famous athlete, every famous performer has somebody who's a coach. Somebody who can watch what they're doing and say, is that what you really meant? Did you really do that? They can give them perspective. The one thing people are never good at is seeing themselves as others see them. A coach really, really helps. So you might have guessed it. That's Eric. Oops, that's. Sorry. So you might have guessed the final piece. You got to have a vision. You got to know the financial freedom pillars. You need a financial freedom strategy and of course need a financial freedom coach. Why do you, why do you need A coach. Well, the CEO of Google needed a coach. Why do you need a coach? All of these successful people, all of them here at some stage or other had a coach. This is something Angela said, Look, Dave's always been there, always patient, never dismissive, highly recommend. This is a young guy, Charlie. Look, Charlie's a lawyer from Canberra. Look, it's actually not. This is Charlie Hunman. He's actually a famous actor. Just Charlie from Canberra didn't want his photo up there for legal reasons. But Charlie said, like, look, recently completed Dave's eight week course. I got real value from the program, save money, clarity. But he says, look, Dave's a passionate, dedicated coach. Recommend to anybody who wants to grow their financial wealth and build the life they dream of. Now if you want to build something magnificent, and let's be honest, if you're here wanting financial freedom, you probably do want to build something magnificent. Get that stage of having all that stuff we've been talking about, you know, maybe even leaving a legacy for those you love or being able to contribute. Now if you want to build, make something magnificent, this to me is a magnificent picture of the Burj Khalifa. But you may not realize what used to be there beforehand. The point being is you need to have a vision. And not that long ago, just under 40 years ago, that that's where the Burj Khalifa was, it was just desert. Now I don't know what's going in your world with your finances or not, whether you maybe feel it's a bit of a desert or impossible. But simply speaking, if the Burj Khalifa can come out of desert, it, all sorts of extraordinary things can happen. You just need to have a vision. You need to have a vision to build something magnificent. It's pretty simple. Now when I've asked your money to grow your wealth, these are the four steps you need. Any financial freedom. Coach, is this for me? I don't know. But if you're the type of person that wants to be able to have the holidays you want, if you're the type of person that maybe wants to have the choice of upgrading your house or buying a fancy car or just having that freedom to spend time with the people that you love, or quitting your job, starting a dream career, I'm not sure what it is. But if you're more time to spend doing the things you want or get that stage of contribution or giving back, well then yes, this is 100% for you. But the question is, who is this for? It's for anybody who really Wants financial freedom. If anybody who wants to start at the beginning with a solid foundation of getting a vision of clarity and know that they're taking the right steps and building a foundation for sustainable lifestyle with a debt free vision. If anybody wants to be debt free, anybody wants to curious about investing in property, it's for people that you know, maybe just wants to set up and start their buying their first home. People want to start an accelerated debt reduction strategy. It's for people that want to maybe find out how much do I need to retire. It's for anybody, it's for business owners, it's for employees who want to pay less tax. Essentially this is catered with such malleable that it could really work for anybody. Anybody that's passionate about making a difference for themselves in order to maybe start making a difference for others, will it work for you? Well, is it the right time for you? All I can say is what Julie had to say. Look, Julie says even if right now is not the time for you having Dave on your side. Look, you've heard from all these people, look, all these people have said it's been incredible changes. So I don't need to too any more about that. But have you gotten some value? I just hope you've gotten some value so far. And would you really like some more value? Look, I've got a limited offer. Look, I did tell you I've got an eight week program. It's called the bulletproof wealth breakthrough program and I'm not here to sell it to you. I'll just tell you a little bit about what it is and I like to have that conversation with people, people off topic. But really as a special bonus, it's an eight week, it's an eight week wealth coaching program where people get breakthroughs. We talk about your financial freedom vision and get clarity, action and results. That's what it's about. What do you actually get? Well, you get to unpack your financial freedom vision. You get to really ultimately discover your lifestyle vision, get to discover your cash flow vision, work on your debt free vision. You get to remove the three main types of resistance that we're talking about before yet to eliminate self sabotage and procrastination and essentially starting gain clarity and taking action, get results and be professionally supported every step of the way. That's the outcomes and there's a whole bunch of tools that we can pull out from time to time and don't have time to get into it. But trust me, there's tools and there's strategies and there's limited time offer. Normally you get on a call and just have a chat with me, it's 395 bucks. But really as a thank you for being here, if you want to get on a call, the call's free and what I'm going to do is just put a link in the chat box here and if you want to get on a call, because if you're curious about this, I just suggest you just jump on a call and follow the link that's in the chat box. I only want to stress, I only like to work with people that I'm aligned with. It's a very relaxed conversation. It is not a high pressure conversation. It's purely seeing out, hey, do you think this program and some of this stuff makes sense to you? That's all it is. There's an opportunity. What I would suggest though is if you're keen to maybe having a chat with me and taking a bit further, well, I jump on quick because when you follow the link you'll see there's not a lot of space and a lot of spots. And there's another bonus here. There's a this limited time offer. I have this action take a bonus which is actually value it $660 now. What's the. Rabbiting on for so long? How terrible. Don't know how much you missed there. Basically the bonus is this. There's a coaching program but often find that people actually need to take action specifically and there's a coaching process that I don't want to interrupt and so I can be often people charge, I charge or people want me to consult. So there's an action taker bonus. I don't know what you want. The initial action on that might be outside the scope of coaching. It might be you want to make sure your home loan structures are right. You want to get the debt down quick. You want some income, I don't know, it could be tax. Setting up a self managed super fund, advice on investment property, but we'll work that out. But really essentially the bonus is you get the eight week bulletproof wealth breakthrough. But I'll also include two bonus wealth consultations and they'll be based on these pillars. Whereas the home loan hacks accelerated debt reductions, no questions asked. Super cycle other people's money. Look, let's find out how to develop IPAs, CGAs, I don't know. So there's a money back guarantee. Look, if anybody comes on board and it's not working for you, look, it's a money back guarantee and I say that with 100% because never, I've never had to refund anybody. So that's, that's why I'm very happy to give a money back guarantee. And really the third little bonus is just for fun. Anybody who goes ahead with the program. Yep, you get the eight week coaching thing, the two week bonus, consult consultations and I will send you a personally signed copy of the book. And there is that link in the chat box I just put in there again for you in case you missed it. And I can't even spell now, I got so thrown by being on mute. It really, really threw me up. Just shows you how professional I am. So there's only five spots that I offer the action taker bonus to. So really if you wanted to tap me up on the extra bits to get the book and the, sorry, the hundred dollars is not in the book. That's only if you're in the competition. But that's it. So really I think you get it. I already offered this eight week thing that all these people have said they've got incredible results and I know that you too will get incredible results. If you want to find out, if you're curious, just jump on a call. It's a low pressure situation. Forgive me, I just rushed rush, rush, rush because I'm seven minutes over already. So just if you don't mind just finishing this saying, look, if you're curious, put a C for curious in the chat box about that or if you got value, just put a V for value. If you got curious and got value, put a V and a C in there. But either way, I just like to say thank you for joining me. There is that link in there. There the oops, there's the bonuses again. You get all that, you get this, you get the idea. I try to be, I try to be generous with all of this thing. So there we are, that's what it is. And I just want to say thank you. So I really hope you get that link. The link will come through. Please just do whatever you can to jump on board because I limit my eight week, I actually limit my private coaching to 20 clients. So I do have space at the moment. But the bonus for five to get the extra two consulting sessions, that is just the first five people. So it doesn't matter when you book in, whether it's later this week or early next week. The way the process works is when you click on the link, you'll apply and I will see who got, who were the first five are. It doesn't mean you necessarily have to talk to me tomorrow to be the first. It's the first people that take action in terms of booking a call. So that's all. We just need to put us out about half an hour. It's a very low pressure situation. So I just want to say thank you for, for joining me. Thank you. I've seen the messages from, from Thurston and Navin and Matthias. So thank you for joining me. I won't be sticking around to answer questions today and unfortunately there's no recordings ever made available of these for privacy reasons. And I just really hope you got some great value. Please jump on the call if you're any curiosity whatsoever. That is the best way, really. You should have questions. You should have questions. So jump on a call and let's have your questions answered and see where we get to from here. If. If it's not for you for now, maybe it's for you for another time. And look either way, I really hope, hope that whatever you do, you continue on your journey towards financial freedom. Never give up hope. It is possible. All things are possible. If the Burj Khalifa can be built in a desert, anything is possible. So until, till we next meet, I want to say thank you for joining me, for giving up some time. I hope you got value and just please do whatever you can to make sure you're heading towards living the life that you love and loving the life life that you live. So enjoy and hope to talk again soon. Thank you. Bye bye. Bye bye. Goodbye. Thank you. Thank you. Thank you.