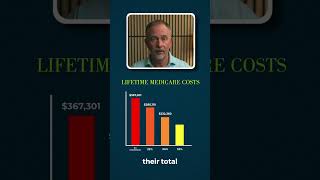
Craig Wear shows that Roth conversions actually save money on Medicare premiums over a lifetime. A retiree avoiding conversions pays roughly $367,000 in premiums, while converting to stay in the 32% tax bracket cuts that to $213,000. Early premium spikes from conversions are offset by larger increases later from Required Minimum Distributions.
Chapters
So many people we talk to say, well I'm not going to do the conversions because my Medicare costs are going to go through the roof. Well, in my opinion that's stepping over thousand dollar bills to pick up dimes. Let me show you what I'm talking about. If they did no conversion at all, they wouldn't pay hardly anything in Medicare premiums in their early retirement. By the time the RMDs kick in, their Medicare premiums part B and D are going to increase anyway. So you can see under no conversion over their lifetime, they're going to have about $367,000 of lifetime Medicare prem premiums to paid. If they just convert to the top of the 32% bracket, their total Medicare costs are going to decrease from $367,000 down to $213,000. Now it's true that in the first few years their Medicare premiums are going to balloon. They're going to go really high and that's not going to feel very comfortable. But at the end of the day, what's going to happen is they just saved $150,000 of Medicare premiums because they optimized their strategy and got things happening a whole lot faster for them.