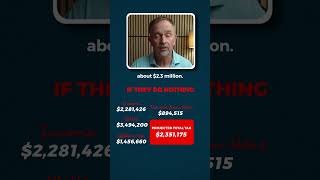
A couple in their 60s with $1.3 million in traditional IRAs faces $2.3 million in lifetime taxes if they do nothing. Converting the entire balance to Roth before RMDs begin cuts that to $500k and leaves their heirs with tax-free money, saving roughly $1.8 million.
Chapters
So the question is, hey, we're in our 60s. We got about $1.3 million in IRAs. Should we convert and how quickly? If that couple did nothing, they were going to have about $2.2 million of other income and their IRAs were going to generate about $3.5 million in RMDs over their lifetime. Put those two together and the estimated tax over their lifetime was about $1.4 million. When they both died, they were going to have enough left in the IRAs to pass on to the kids that the kids were now going to have almost $900,000 of taxes to pay over the next 10 years. In a best-case scenario. So that means their projected total tax is going to be about $2.3 million. So the best game plan for them got everything converted up until the year that they started RMDs. So they had RMDs of just $3,700. Their estimated lifetime tax dropped even further down to just $500,000, and it totally eliminated all the tax to their heirs. Their heirs are going to get all Roth IRAs with no taxes to it. That estimated tax savings is $1.8 million. And if you want to see how this kind of strategy could maybe line up for you, schedule a call with one of our rothologists and maybe they'll be able to show you kind of how something like this could work out, what kind of money you're talking about being able to avoid in taxes for yourself and for your family.