0:52

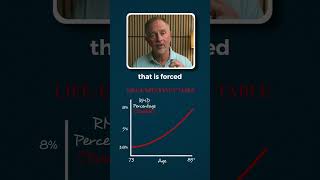
In this concise explanatory video, Craig Wear, CFP® outlines how Required Minimum Distributions (RMDs) from traditional IRAs are not static but increase each year as a retiree ages. He explains that the IRS uses a life‑expectancy table to set a withdrawal percentage that rises from about 3.8% at age 73 to over 5% in the early 80s and can exceed 8% in the late 80s. Because RMDs are taxable, a larger balance and higher withdrawal percentage mean higher tax bills. Wear highlights the counter‑intuitive trap: the better an IRA’s investment performance, the larger the RMDs become, which ultimately inflates the lifetime tax liability, potentially costing millions over a long retirement.

Chapters

More from Craig

7:35
youtube.com

The Smart Way IRA Millionaires Avoid Millions in Taxes

3d ago
1:18
youtube.com

The Best Roth Conversion Strategy

4d ago
10:42
youtube.com

3 Steps To Future-Proof Your Roth Conversion Plan

6d ago
0:58
youtube.com

Don't Blindly Trust Software to Plan Your Roth Conversions

2w ago
3:34
youtube.com

The Tax Trap Every IRA Millionaire Will Face

2w ago
1:44
youtube.com

Break Even Analysis for Roth Conversions Isn't Good Advice

2w ago
3:02
youtube.com

Over 70? Use This Charity Loophole to SAVE BIG On Taxes

2w ago
1:03
youtube.com

Free Roth Conversion Advice Isn't Free

2w ago
2:46
youtube.com

The Biggest Mistake People Make Converting to Roth

3w ago
1:19
youtube.com

Plan Ahead For Widow Taxes With Roth Conversions

3w ago
3:41
youtube.com

The Real Cost Of Waiting To Roth Convert

3w ago
See all content