Why IRA Millionaires Shouldn't Listen to This Roth Conversion Advice (and what to do instead)
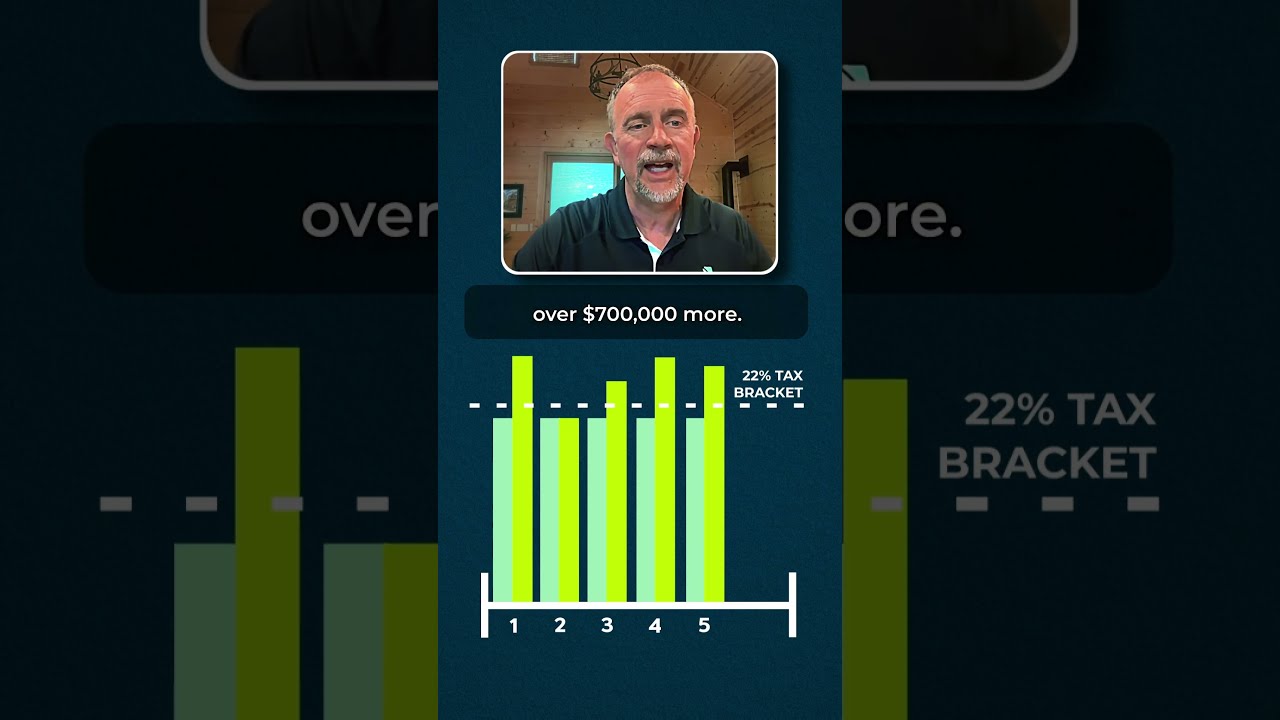
In this video Craig Wear, CFP®, challenges the widely‑circulated advice that Roth conversions should be limited to the top of a taxpayer’s current income tax bracket—or just below the Medicare‑premium trigger—each year. He explains that while this “guardrail” works for modest IRAs (under about $500,000), it can be costly for high‑net‑worth accounts of $1 million or more. Wear walks through two illustrative scenarios: (1) converting each year up to the 22 % bracket, which after nine years yields roughly $7.4 million for the family (about $400 k more than doing nothing); and (2) a calibrated, multi‑year conversion plan that looks ahead 30 years, varying conversion amounts based on the family’s long‑term cash‑flow needs. This second approach produces about $8.1 million—over $700 k more than the fixed‑bracket method—and reduces lifetime taxes to $443 k. The key insight is that paying a bit more tax now, deliberately, can dramatically shrink future required minimum distribution (RMD) streams, turning a large future tax hit into a modest, manageable one. Wear frames the smarter plan as “what does the family need over the next 30 years?” rather than “what bracket am I in this year?”








