The Money Habit: How to Become Financially Independent - Virtual Presentation with Mike Michalowicz
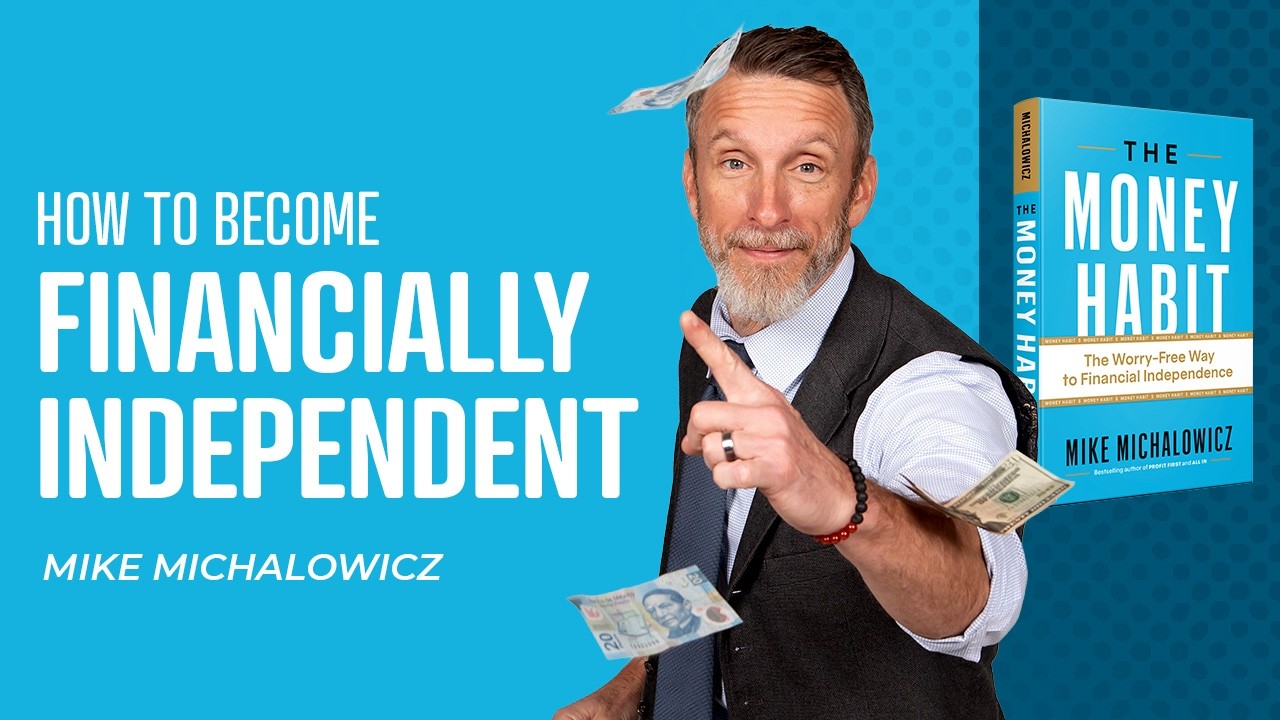
In this virtual presentation, the speaker (Mike Michalowicz) explains why most small businesses are financially fragile and how personal and business finances are intertwined. He uses a basketball "granny‑shot" analogy to illustrate that reducing variables leads to consistent results. Drawing on behavioral economics concepts such as container size, Parkinson’s Law, optimal foraging theory, and the primacy effect, he argues that people consume more when resources are abundant and that constraining cash supply changes behavior. The core solution is a modern envelope system implemented at the bank level: six checking‑style accounts named Income, Needs, Wants, Dreams, Fix/Future, and Emergency. Money flows from a depository‑only Income account into the other five based on percentage allocations tied to income tiers and personal "financial seasons" (Recovery, Fund, Activate, Balance). He provides practical steps—starting with a single purpose‑named account for the most pressing financial worry, allocating each paycheck, then expanding to the full six‑account system. Throughout, he shares personal anecdotes of debt, failed wealth, and client expectations, reinforcing that financial independence is about managing more of what you earn rather than earning more.
Chapters
Here's what I noticed around most small businesses. Now, small business defined by the SBA is a company that does $25 million US in annual revenue or less. That's absolutely my company. And I suspect it's some of us, many of us, perhaps all of us in this virtual room here. Most businesses are financially struggling. Uh, the SBA identified 83% of small businesses are in check-to-check survival, and the only way to offset it is by leeching off of home finances. And even if you've been so diligent about saving and preparing for the future at home, if the business isn't performing well, it starts sucking the blood and life out of the home. And, and the vice versa is true. You may have a business that's doing super well, but if our lifestyle, we're not managing our finances there, it can leech off the business. Our business finances will only ever be as healthy as our complete financial management, not just our business, but managing our home. And I'm happy to say it is ridiculously simple. I'm going to start off with a story around basketball. Now, I'm not— I don't know if anyone here is a basketball fan. Not into basketball. Like, I know Shaquille O'Neal was a basketball player. I think Michael Jordan may have been. Like, that's like, that's my level of understanding. And I don't actually even know which one was better. But I came across a statistic around basketball that blew my mind away. And it's just an interesting story regardless if you're into basketball or not. There was this guy who played in the NBA back in the '70s or '80s who had the highest free throw percentage. Now we're doing this camera so you can, you can see me now. There was a guy who shot 90 percent free throws, which means of every 10 he took, he made 9, while the average NBA player even today shoots around 70 to 75%. They make most their shots, but out of 10, they'll miss a couple. Well, just to give a sense of how you shoot a basketball is, is usually with, with 2 hands, one being what's called the guide hand. So this is my left hand, is my right hand. The guide hand directs the basketball. You're my net, so I'm shooting toward you. And the other hand, if your right hand, for example, more often you'll shoot with your right hand, is the power. So it pushes the ball. This one guides it. To do it also, though, you put spring in your legs. So you need to be moving your legs and moving your arms. You have to articulate your elbows. There's all these different actions you need to take to make a basket. Even move your wrists because of the forward roll, and you try to snap your fingers back to get a backward spin. And if you nail it, you'll, you'll make that basket. So there was this dude named Rick Barry, never heard of him. I suspect you haven't either, who shot 90% and did it consistently throughout the league. Was, was famous for being the best free throw shooter of all time in the NBA. How did he do it? He shot granny style. Like under, like, let, let's give us context here. He shot granny style. Now, it wasn't exactly like this. What he did was he actually put his hand on top of the ball. So So he would put his hands like this and shoot the ball. So you can see me from the side here. He'd shoot like this. And what happens is, you'll see, I don't have to bend my elbows. They actually stay locked in their position. The wrist automatically— that's the natural tendency of a wrist— automatically goes up, which causes a backward spin. It increases your odds of making the basket. The lesson here for us is the less variables, the fewer things we need to do The more likely we're able to do whatever is consistently. So lesson 1, remove variability. Lesson 2 is you don't have to be cool to make a lot of baskets. What we're about to learn when it comes to managing money is surely in cool. There's not tons of spreadsheets or not like some fancy app. We're going to do this at a very basic and simplistic level. I guess my fear or my concern is as we go through this, It may be so simple, you may say that won't work, or it's, it's, it's, it's not cool. So if you feel skeptical or resistance as we go through this, I totally accept that. Actually, I kind of expect it, um, because I resisted this for myself, but I, I did it for myself because I was desperate. Um, here's the last thing I wanna show you around basketball, and then we're gonna start kicking into things. I, oh, I don't like to use, I don't like to use PowerPoints. Instead, I use the old school. I don't know if you went to school in the '80s or '70s like I did, but we had these overhead projectors. So I bought one and now I use it. So this is my— I, I don't call it a PowerPoint. I call it a paper point. So here's the statistics that are super interesting. Rick Barry, like I said, shoots 90%. Like, that's— I'm going to zoom in one click— has a 90% free throw shooting percentage. While the average NBA— I may have said 73 or 75— it's actually 78%. So this is the norm. This is the average. This is the Rick Barry standard. I'm just going to put RB. Now, in the NBA, they— a team takes about 22 free throw shots. So once you get fouled, there's a penalty. You walk to the free throw line and you shoot your basket. Each team on average per game, depends on the fouls, gets 22 shots. Well, if you get 22 shots and you shoot 90% versus 78%, there is a 3-point difference of how many baskets you'll make. So you'll make plus 3 points if your entire team can shoot 90%. Now, the average point difference, not to belabor too much, is 12 points in a game. So you won't win tons of more games. But on average, if you can shoot— your entire team can shoot 90% instead of the average, and you get 3 points more per game. You will win 8 more games. So 8 games per season. And this is where it becomes interesting for me, at least. The average frequency of games or number of games a basketball team plays is 82 in a season. So an average team, I mean, total average will be 41 and 40 to, you know, 41 wins and 41 losses. If you have a team that shoots average, you have a 45% chance of making it to the playoff. Now, the playoff is where you make your money. So if you're an NBA team and you have a winning record like the Chicago Bulls did for such a long time, where Michael Jordan did play— I didn't know he was a basketball player— Michael Jordan played, or the Boston Celtics were very famous for a long period of time. They made gobs of money because of the team's performance. They were considered the exception. People want to buy the memorabilia, the clothing. They get more games. And if you're a player, For the NBA, you get paid significant bonuses the closer and closer you get to the championship, but you got to get into the playoffs. Plus, you can get TV deals, you know, commercials and all this stuff. The money is in the championship. Now, here is what's crazy. The average team wins 41, loses 41 games, and has a 45% chance of going to the playoffs. If you simply win 8 more games a season, so This would go from 41 to 49. That means 49 wins versus— hey, what's that? 3, 30, 33. Is that minus right? You would be 41 and 33 losses. You now have a 97% chance of being in the playoffs. I mean, you're virtually guaranteed to be in the playoffs if you simply shoot 3 more baskets, Make three more baskets per game, and the secret to making three more baskets per game is to shoot like a grandma. Granny, listen, and I'm not bashing grannies. Clearly, they got something figured out. Shoot underhand. I mentioned Shaquille O'Neal. So the logic is, why aren't these basketball teams all shooting underhand? Because it guarantees it. Why aren't the coaches forcing it? Why aren't the an average NBA player makes $10 million. I think it was $10 million a year to do one thing, make baskets. So why aren't they doing this? Shaquille O'Neal gave the most succinct, most appropriate answer I've ever heard about this. He was interviewed and he was, just to give context, a 50% free throw shooter, meaning he was not so good. The interviewer, she says to him, because why don't you shoot underhand, granny style? And he goes, because it ain't cool. And in that one line, he said exactly what everyone else is thinking. And it's unbelievable. All these players would make millions more. The NBA teams would be served so much deeper. The coaches would be so much more prolific if that's what they desire, because they have winning teams. They simply abided by simplifying things, but because it's not cool, they don't do it. And while statistically it's absurd, that's, that's human nature. I, I believe our challenges with finances is because we have a hesitancy to do the uncool things. Uh, we, we frame ourselves or see ourselves a certain way and say, this is who I am. So I'm not, I'm not good with numbers, therefore I'm not going to be good at finances. I'm not going to do this. And there, there's all this framing of who we are, like Shaquille O'Neal's, this is who I am and I won't do that one extra step. So I just want to challenge you as we, we go through this process and, and teaching the system that it's, it's wildly simple. It's not cool at all. It's very basic. And it may be a little bit different than what you've done, but if you're willing to simplify actually the steps in the finances, you may see big progress. Last little kind of pre-matter I want to share with you why I'm so— you probably feel the energy already. I'm like ready to come through the screens like we gotta make you money. I have a question for you. Of all the people in your life, who do you feel most wants you to be profitable, to be wealthy, either personally or in your business? Likely both. Who wants that most from you? And I'll give you, it could be a spouse, it could be a parent, it could be a loved one, it could be a vendor. It could be yourself, right? It could be someone else. So I would say there's someone who wants to be more profitable than even you, and you'll be shocked when you hear this, I think. The person who wants you to be wickedly profitable, but they'll never say it to you, is your clients. Your clients want you to be profitable, and I would argue they probably want it more than you even want it for yourself. And I know that sounds like totally absurd because my clients say, oh, I can go shopping elsewhere. Can you sharpen the pencil a little bit? They will never say, can you charge me more? Are, are you rich? Because I want you to be rich. But they feel it. Let me give you An analogy. Now, I wish this upon not a single person in this room, but imagine right now one of us has a major health event. Let's let's pick me. I have cardiac arrest of some sort. 911 get raced to the hospital, and in this bizarro world we're making up here, two doctors come out to perform the procedure. But before they start, they both explain their situation to me. Doctor one. She looks at me and says, oh, you're having a heart attack. You know, it's kind of funny. I'm financially having a heart attack myself. I'm, I'm, I'm not making any money. I'm, I'm, I'm deep in struggle. We're, we're barely scraping by. Actually, I've missed my mortgage the last 3 months and really need to get more work in or, or we're going under. Are you, are you ready for your procedure? That's, that's doctor one. Oh, and by the way, she'll throw in a 50% discount. By the way, she's like, you know, I really need the, I need the money. So half off, a special deal for you. And Dr. 2, I get wheeled out. She comes out of the OR and says, it's nice to meet you. I understand you're having a heart attack. Before we get started, I want you to know I am very wealthy because of the work I do. I am the world's best at this procedure. In fact, the exact situation you're having is what I solve, and I have a 99.9% success rate. I'm extremely confident we can get this done. I charge a massive premium for what I do. And that's why I live a life like I do of wealth. Um, are you ready to start? Just be brutally honest in the chat. Do you choose doctor 1, 50% discount? Doctor 2, premium, massive premium. Who would you choose? Angela's doctor 2. Doc, if anyone types in doctor 1, I'm coming through this camera and, and, and, and just gonna shake you. Yeah. 2, premium. 2. Of course. Of course. The client, all of us, want the doctor to be redonkulously wealthy. Now listen, we don't want to be rich jerks. It's not like we hope you're a total, you know, whatever. I'm thinking of profanities. I got to stop that. You know, just we don't want you to be this super rich jerk, but we do want you to know, we do want to know you're not worrying about money when you're worrying about us. Now, as a dance studio, I strongly suspect you are not saving lives, but I strongly, strongly suspect you are altering lives. You are giving your clientele, and I believe it's mostly children, an opportunity to express themselves. Thank you. I actually get a little emotional. That's amazing. It was transformative for my daughter who experienced dance. There's a fella I know, Ian. He's a ballet dancer. 18 years old. The most important thing he's had in his life is an outlet of dance. He actually is the son of one of my colleagues here. We were just talking about it yesterday. I'm not saving lives. I intend to be altering them. And I know you're altering them. And imagine us going to your client and saying, hey, Ian, I know you're really interested in ballet, but here's the truth. I'm barely getting by. I'm really struggling. I've missed the mortgage. Um, I'll give you 50% off. I just need you as a, as a student. Versus the studio says, we are very sustainable, we're very profitable. Um, we are 100% available for you because I don't have any financial worry. And that's what the client wants. Our clients want us to be 100% present for them. And that's the words they use. They don't say, I hope you're making tons of money. They say, I wanna be your number one client. I wanna be taken care of. I don't want you to be distracted. That's why this is so important. This is just one last part of my story. So that's why I want you to be very wealthy as you define it. I'm not saying to be a jerk. I'm not saying that money is more important than anything else in your life. I'm saying it is a vital factor that we all want for you. Why I'm so visceral on this is my own life experience. I've been an entrepreneur. My entire life, never thought I would be, but I became one, and never understood how to manage money. I thought the solution was to make more. Oh, when I started my first business, when I get to a hundred six figures, when I get to $100,000, I'm probably making $100,000. And I know you've been there, my friends. You get $100,000; you've lost like $50,000 to get there. Like I ate through all of my savings I had. I borrowed money from my parents. I refinanced my starter home, um, 2 times just to cover payroll. Um, there was no equity and it was actually upside down, meaning it was worth less. I mean, I had more mortgage than it was worth if I sold it out. I also remember mismanaging my money so much that I started to get collection letters. Um, I built some businesses, I sold them. I never made money running them. I made money when I sold them and assumed, oh, we have to sell our way to success. Yeah. And, um, I was so ineffective in my day-to-day management of cash. I was, I remember distinctly getting, um, letters in the mail from debt consolidators saying, you know, we, we professionally consolidate your debt because you have all this credit card debt and so forth. And sitting there going, holy crap, my financial struggle, our financial struggle, if you are experiencing it, is, is on public record. This is the least private, private thing in the world. And I thought I was the only one who knew. And it's, it's everywhere. I was afraid to walk to my mailbox because I thought maybe my neighbor would see me getting these bright red envelopes that says debt consolidation or debt collection on it as I walked out. And I knew my mailman, he definitely knew. That's why I'm so vehement about this. My life financially turned when one particular night in 2000. 9 or so, I was watching television and on came a fitness instructor, very similar space to that you're in. And she shared that there's some basic principles that we can use to change our physical fitness. And I, as I was hearing it, I'm like, oh, this is all about fiscal fitness. So, uh, we'll go into some of those basic principles. What I'm just going to share with you applies not just to your personal finances. If you're familiar with my other work, Profit First— so we're talking about this book, by the way, it's called The Money Habit— but, um, Profit First is the sister book to this. That's for business finances. We're talking about the personal finances. The first concept, I don't know if you've heard of this. The average size plate in, in the United States used to be this size. So what I'm making is the size of maybe what we consider a coffee saucer or dessert plate. In the last 300 years, plates have doubled in size. Now, what's so interesting is our human behavior hasn't changed. We still eat off— we still fill up our plates and eat off our plates. And while our behavior hasn't changed, the container has changed. As the container gets bigger, our portions get bigger, therefore consumption gets bigger, and then societally our waistline gets bigger. This fitness instructor said there's a real simple solution. Reduce the size of your plates at your house, and you'll actually consume less. The container is dictating the consumption. I don't know if you've seen soda cans. I just went down to the deli right before this to get some lunch a few hours ago, and I went down there and I was looking at the soda rack. I got my little iced tea, and I filled it with water. My black tea, unsweetened. This thing is massive, by the way. The soda cans were even bigger. Soda cans, just 100 years ago when they were invented, were what we consider almost like a shot container. Then they became, I think it's 16 ounces. Have you seen, has anyone seen the newest soda cans? It's like a bazooka. It's literally, you could put this on your shoulder and like launch a missile outta these things. They're massive. And the thing is, we still consume it all because we're wired to consume what we have. What we need to do is control the size of the container. Have you noticed, and you can put this in the chat, I have a friend that's had this experience, maybe you've had, or you can say me too, whatever. But tell me this, have you noticed that over your lifespan of your business and perhaps even your personal life, that maybe your income's increased? Maybe you make more money today than you did right when you graduated from high school. I don't know, but probably, and maybe. Have you noticed that as your income goes up in your business, that it seems that expenses run at almost uncannily the exact same rate? Like, this is the breakthrough month. Finally, I've arrived. And then it's like, what? Where did it all go? Okay, so lots of absolutely yeses. Okay, if you're saying absolutely yes to that, by the way, I promise you we're going to master your money. And then our 2 hours together, there's no question about it, because you're demonstrating the natural wiring of humanity. There's a behavioral theory called Parkinson's Law. We're going to dig into it. And what it explains is, as the container gets bigger, More in that checking account, our consumption gets bigger. Um, does anyone here have teenage boys? Just raise your hand. I'm looking at the screen. Anyone? Okay. Lisa does. Nisha. Oh, you're, you're pumping your hand. Wait, you got 10 kids? You got 10 teenagers? Uh, Kirby's with me. Shanna. Okay. Okay. Melissa. So everyone who raised your hand, I am sorry. I am deeply sorry you have teenage boys because they're not called teenage boys. We all know this. They're called creatures. The food consumption, the food consumption is redonkulous at our house. I got 2 of these goons. Leech Boy, as I call him now. He's one of them, and his name's Jake. They— my boys— I gotta do this on this camera. My boys get up somewhere around the ass crack of 3 in the afternoon. They come out of their bedroom, and you can tell that for such awkward human beings, they're awfully silent. Like, it's unbelievable. All of a sudden, it's like, oh, it's Someone's next to you, except for the stink, because this smell emanates in front of them and it's disgusting. Have you noticed how much food they eat? So of my, of my boys, they'll come up at, you know, 3 o'clock in the afternoon out of their lair bedroom, come up, pour the Cheerios into their, the cereal bowl, and it just overflows. And, um, Like, oh my God, I could just clean it up at least. Then they put milk in it. It's sticky, and they go back to their lair. I'm kind of grateful because the stink is gone. Well, once I heard the container dictates consumption, clumsy dad here, I broke all the bowls in our house and had to go to the local store here and got bowls that were slightly smaller. If you do this with your kids, it works. They're smart enough to see if you get really small, like ramekins or something, they're gonna figure it out. Just get slightly smaller. Over six months, I did this four times, and the bowls were half the size, and those goons never noticed. Note, and a box of Cheerios used to go through a box of Cheerios every hour at our house. Like it was lasting now like three or four days, which if you've teenage boys is the definition of a miracle. Lesson number one financially is the container dictates the consumption. It's a subconscious response. It's called Parkinson's Law. So here's a question for you, and then we're going to go to our paper point. In your personal finances— this is a yes or no question— do you have— it's called a primary checking account— do you have a primary checking account where your income, and maybe there's other participants in your family, a spouse, a relative, family that contributes to it, so there's a collective household income— do you have an account where most of, or maybe even all your money goes in and you pay your bills from? That's called a primary checking account. If you have that, say yes, I do, or no. Okay. Wow. I think Caitlin, you're like one of the first to answer, and you have another human being on top of you, and you still bang that one out. So all yeses. If you said yes, which I think everyone did, you are primed to be permanently wealthy. And I know it sounds a little crazy, but you are, because again, you're demonstrating the natural behavior of wealth management is what's called a primary checking account, and we manage from there. We're going to make a small underhand granny shot change to that. It's going to be a game changer. But I do have a second question, and this is just as important. Even though you may have an accountant or book financial professional supporting you, maybe a financial advisor, maybe a bookkeeper, a tax advisor, maybe, maybe it's someone in your life that's told you, well, you got to have a budget. You got to maybe reconcile your Checking accounts or whatever, or prepare a budgeting thing. Tell me if you follow a system. This is another yes or no, but tell me if you follow a system. Let's make it. Let's make it on frequency. I'll tell you what my system is, and just tell me if you do this too. I want to know the frequency. Instead of reconciling my bank account, instead of running a budget, I simply log into my bank account, and if I have money, I will spend it, and if I don't, I will panic. Who here maybe have some version of that? Who here checks their bank account monthly or weekly? Or put your frequency in there. How often do you check your banking account? Daily? Never? Daily? Dailies are winning right now. Once a week? Dailies are winning. Weeklys coming in second place. Weeklies and dailies. Awesome. Monthlies, third place. Okay. So daily, weekly, and monthly is the 3 most frequent ones I saw. Weekly and daily being the most frequent. If you said you check your bank account daily or weekly, I want to pat you on the back. You are wildly primed to be profitable because you're demonstrating the natural behavior of monitoring and checking. If you don't check your bank account, you may have other methods, and that's amazing. What I'm going to teach you works. The more frequently you check your banking account, the better off you are. So how do we, how do we do this? I'm telling you, the 2 assets we need is you need to have one checking account. you put money in, you take money out. And the second thing is you got to look at it often. If you're doing that, we're golden. Um, we just have to change to a granny shot. We're going to do this at the bank level. Now, um, this is based upon concepts in behavioral psychology, but also traditional, uh, banking and financial prin— principles that go back to literally biblical times. Um, what I'm teaching you is nothing new. It's just a new application of it in a new way. But it's been around. It's been documented in In religious manuals of all types. It's been studied in modern behavioral psychology recently in the early 1900s. There's this guy, B.F. Skinner, who's researching this, and then it's been modernized by other financial experts in current times. But traditionally, at least in modern times, it's been called the envelope system. If you've heard the envelope systems, give me a thumbs up or a wave on the screen. Okay, awesome. So good, a lot of people here. I've experienced the envelope system because I was raised under it. My mother's from Germany, came here in her 20s and married my father, and we were raised with this. Well, what she would do is she'd have multiple envelopes. She worked at a manufacturing plant basically down the road from here and worked part-time, which meant she had volatile income like we all do here. Sometimes she'd work overtime and get some more money. Sometimes she wasn't available for whatever reason. Maybe she was sick or taking care of us kids, and there was less money. And she'd divide to— then cash in her check. My dad would do the same. They divide the money up. There was one for the mortgage, one to give back to the community and the church, another one for food and all these different things. When my mother would go food shopping, she'd grab the food envelope and go to the food store, and she always had enough money. But there's a, there's a key component around having enough. I'm not saying it was the same amount of money. I'm saying she always had enough, meaning that was the allotment she worked with. It was a percentage allocation, and that's what she worked with. And for Germans, at least, when you go to the food store and you don't have much money, it's a lot of sauerkraut. I mean, a lot of sauerkraut. And for any of the Germans in here, you do have a lot of money, you splurge on liverwurst, which, if you don't know what liverwurst is, the translation to English is disgusting. It's just absolutely disgusting. Liver sausage. But Here's what we need to do. This is your bank. And by the way, these are based on behavioral principles. And there's a concept called a commitment device, or I call it a behavioral intercept. And perhaps you want to write this one down. Changing behavior is very hard. So don't change your behavior. Channel your behavior. In fact, I'll tell you, if you take away anything from this, this is the big one I want you to remember. Don't change who you are. Channel who you are. Because when you channel what you already do, You can continue to do what you already do and get the outcomes you want. So can you set up guardrails or a system that, that encourages you to keep doing what you wanna do? I'll give you an example. 15, 20 years ago, I wanted to start working out regularly. I'm like, I, I better commit to this cuz I, I wasn't. And what I noticed is the first day I tried to use willpower, I woke up in the morning, I'm like, I'm just gonna work out today and crank it out. And it was a great workout that day, but the next day I was like, I am really sore and maybe Maybe I'll pass on this one, and by day three is off the wheel. What I did is I observed every morning I wake up, I'd wake up, go to the bathroom, make a cup of coffee, read the news, and somewhere around reading the news, I was I was off in la la land and off to work, and had another excuse not to work out. But in that predictable pattern, remember channel who you are. I'd wake up in the morning. The first thing I do is go to the bathroom. I said, oh, I always go to the bathroom first. I put my sneakers. On top of the toilet seat. I cannot, even today, I cannot use our bathroom without me grabbing my sneakers. And, uh, when I travel, I do the same thing. I put it on the, on the toilet seat and it's enough to kick in momentum. I have the sneakers in my hand. Well, I just put my feet, just go to the gym or go for a run, just even if it's 5 minutes. And that usually kicks into a good half hour or whatever. We have to intercept, hence behavioral intercept, intercept our current pattern. This is how we're going to do it using the envelope system. Whatever bank you work with, if you like working with them, keep working with them. I can suggest other banks if anyone wants tips, but we're going to set up 6 accounts. I call it the sweet 6 accounts at your bank. We'll all make these all checking accounts, but we're also going to give them nicknames, and I'll explain each one. But the first one's going to be called income, and I'm going to put this kind of dotted line here to separate out the other 5 accounts. Then we're going to put, uh, the next account is called Needs. Then we're gonna have one that says Wants. Then we're gonna have one that's called Dreams. Then we're gonna have one that's called Fix, or we may change it to Future. I'll explain why in a second. And the last one is called Emergency. Um, Which, if you grew up in the '70s like I did, best TV show ever next to CHiPs was Emergency. Okay. The income account starting today is what's called a depository-only account. It's going to receive money and we're never going to spend it. So the money that you have, your household income, and if you're doing this by yourself, it's great. If you're doing it with someone else in your home and they're contributing, you can all go in here. If they don't want to support the system and you want to try it out on your own and you have separate checking accounts, Just do this for yourself. Like, you don't have to have someone fully engaged. Just prove it to yourself first. That's okay. This is a depository-only account. We're going to receive money here, and then on a periodic basis, we're going to carve the money up and flow it out to these different accounts. Now, we are literally a few days away from Thanksgiving. Who's hosting, by the way? Okay, good. I'm going to visit all of you. Tracy, you were the most excited. I want to come to your place. That's going to be an amazing meal. We're hosting too, Trace. And may I call you Trace? Is that okay? Yeah. Okay. Okay. So we're hosting too. And the tradition, I assume at your house too, is when the turkey comes out, we put— we have a small group. It's going to be 10 of us, maybe 12. Comes out, everyone's going to do the silly Instagram photos like, oh my God, like no one's ever seen a turkey before. They start taking all those silly photos. But then I don't say, hey everyone, whoever wants it the most gets it. Everyone for themselves, dive in. No, you carve the turkey. And why do you carve the turkey? It's to assure that every guest who wants turkey gets some turkey. Of course, it's not just for Thanksgiving. Whenever you have people over, you apportion the meal. There's a serving tray, and then it gets served up. Angela loves hosting. This is going to work for you perfectly. This is our cash turkey. Money comes into your home and it has to carve up to serve all the guests at our home. These are the 5 primary guests. And, uh, if you have a massive gathering like Tracy's going to have, I suspect you may have more guests, but these are the ones that constantly show up. Let's go through them. First guest is called needs. Needs are for the essentials for living. Everyone needs shelter, It's based upon Maslow's hierarchy of needs. Food, water, protection from the elements, protection from imminent harm, and stuff like that. What provides for that? Well, these are the essentials. So, you know, you and I, we need to eat food and drink water. You can't get by without it, which is different than a want. This is an essential for living. A want is the small luxuries of living. So I want to eat out. I need to eat food, and that's the the difference between needs and wants. And I also understand it can be subjective already. Like well, I need caviar. Do you? So we all have our own definitions. If you have any question if something's an essential need versus a want, a mini luxury, it's always the higher level. So when you're like I. I need caviar because I love it. Um, it's a want. So if you're categorizing how you're spending money, um, it's always the higher level when you don't know which one it is. Other needs are like utilities and paying the, the mortgage and so forth. And all this stuff can become subjective. Well, I, I need a roof over my head and it happens to be a 7,000 square foot house. I need it. Yeah. Do you? So we're gonna play with that a little bit. Um, So that can become subjective, but that's the difference between needs and wants. Dreams are the longer-term visions and luxuries. So a dream, let's go back to food. I need to eat food. I want to eat out. I dream of having a personal chef. Like, that's kind of the breakdown. Dreams are usually the most aspirational, perhaps bigger luxuries, but it's all subjective. based upon your life's circumstances. So these are very personal things. The fix and future account. Fix is if you have debt from the past, we have a responsibility to eradicate it. So we're going to devote money to the eradication of debt on a consistent basis. So that's called fix. And future is if you've eradicated what's called unsecured debt, which means Non-asset-based debt. So a home, the asset-based or secured debt, and a car, which are also— is also an asset-based debt. Yes, cars usually depreciate over time, but they retain value for a period, a long period of time. Homes usually appreciate and they maintain value for a long period of time, and they are essential for living. You need some kind of shelter and you need some kind of mode of transportation. So those forms of debt we don't need to eradicate. We just need to be on a plan of managing it so that they become possessions of ours and that they don't bury us. But unsecured debt could be like credit cards and personal loans and student loans, all these other things that just eat away at us. So we're gonna devote our times to addressing that unsecured debt. Future is once the unsecured debt is addressed. Future is preparation for future events, typically oriented toward a slowdown in our financially productive periods. So this could be what they call retirement, which retirement is a very nebulous term now. And the last thing is emergency. Emergency. If there is one predictable bill that I can guarantee all of us will experience, it's an unpredictable bill. So We don't know what it is, but we— I can guarantee it's gonna happen for all of us, and you've already had it happen, the unexpected expense. So we are gonna deliberately prepare for that because it will happen. This system is the envelope system, but we're gonna do it at the bank level. Money's gonna flow in. And what I'm gonna do when we're doing kind of Q&A, I'm gonna give you some charts. Our— my company and my team here We ran an analysis of, um, well over 1,000 individuals in different income brackets and so forth, and determined what percentage of money should be allocated to each account ideally based upon your income bracket. And this concept I'm going to share in a second called a season, because we're in different financial seasons. But let— first, I want to explain why the envelope system works. You know, this is based upon What's called optimal foraging theory. So optimal foraging theory is the understanding of how humans consume perishable things like food. It's a survival mechanism. So back in, you know, say, the Neanderthal days, traditionally the males were hunters and the females were gatherers. But research indicates that both parties did whatever was necessary to get food. What would happen is, let's pretend we're all out on the hunt for food. Like, we're like, and what we, what we do today is like, hey, where do you want to go out and get some food? Do you want to go to supermarket and pick up something, or do you want to go out for dinner if we have the means? You know, but back then it wasn't like, hey, you know, you want steak tonight? No, it was like, we need to hunt. Ugh. Um, let's get a woolly mammoth. Ugh. And they would go after the woolly mammoth. What you did is you devoted tons of energy and resources to the capture of what you needed, and you'd capture mass, and you get this big bulk of stuff, a woolly mammoth. And then you were in a, in a, a situation here of having something that's perishable. Well, you can't consume it all. In fact, that would actually weaken the tribe. It puts you at risk because you're just in this digestion mode. So what they would do is very quickly go into preservation. So you first hunt or gather, then Then you preserve, and then you consume. So humans, we are wired to hunt, collect, actually en masse, then preserve. And the way you— they used to do it is through smoking meats, burying fruits and vegetables. And they did their different techniques depending on where they live. They could put it under snow and stuff that would preserve it. And then you would consume in small pieces. Fast forward to modern society. We hunt in batch. Chances are you don't get your income every 4 to 5 hours, a little portion of it, because that would be optimal based upon our need for consumption to get paid every 3 to 4 hours. Chances are you're getting paid once a week, more likely twice a month, in some cases once a month. That is the hunt. And all of a sudden this woolly mammoth comes in and our mind says, that is rotting food that must be consumed. Because I am not preserving it. The, the Neanderthals understood that if food was left out, um, and they couldn't preserve it, you have to consume it because you're gonna lose those calories. So you start consuming it. Modern society is set up with no preservation. So money comes in. If you have one bank account, primary checking account, it's not called income, it's just called checking. Our minds are wired like, oh, you better use this quick because this is gonna be gone soon. Yeah. If I only have one checking account, our mind goes to, I have enough money for an immediate need. It's, it's a perishable item. Fungible is the modern term for it, but it's a perishable item. There's only a certain lifetime. I got to use it in some application. I'm going to use it right now fast. I'm going to buy that couch. And that's the trap we get into. And so why the system works is now we have ways to bury or preserve our money, carving up these different accounts. Then when it's carved up, we can pull the money out as we see fit. That's the basic principle. So principle 1 is set multiple accounts, reduce the size of the container. Remember the teenage— any teenager, quite frankly— smaller ball, smaller consumption. Set the preservation. But the next thing we have to understand is a concept I promised to share with you. It was just called Parkinson's Law. So let's get into that. I'm going to flip the slide here, my slide deck. Oh, stuff's see-through, so I'm gonna put this under. So Parkinson was a theorist in the 1950s. His full name was Northcote Parkinson and was studying how we consume resources. And what he noticed is traditional training tells us, and you've— I'm sure you've heard of this, is that as demand increases for something, That supply will increase to meet demand. The more students that want to come to your dance studio, that's more demand, the more classes you will offer. And if you don't, competition will. You make it to a certain size where you expand your studio because there's so many people coming. And that is only partially true and actually is rarely the case, according to Parkinson. Parkinson said it's rarely the case that this happens. He said, in fact, more often it is supply that is indicative of demand. He goes, the more available something is, the more we consume it. Now, I'll prove this to you right now. Have you? Can you reflect on a part of your life, and you can speak on behalf of a friend. You guys know the rule. I have a friend, so I have this one. Have you ever, or do you have a friend who's ever been given time to complete a project? Maybe back in the school days where you're like, I gotta prepare for an exam or something. Have you noticed the more time you're given, the longer it takes to get ready for something? Like, okay, Kirby gave me the bingo. Yeah, Kirby, you are living Parkinson's Law, and that is amazing. Because it means you are perfectly wired for wealth. Um, so there's some I-haffers. Courtney's guilty. Yeah, totally. Um, I, I've noticed that, uh, the, the larger a closet is, holy crap, the more stuff that can pack our closet. And, uh, we moved to a new home, uh, about 10 years ago, and we got— for the first time in my life, I had a walk-in closet. And I was like, we will never fill this. And it took us a week. And we've— I can't unfill the thing. And I'm not— listen, the person accused of this is me. I have a propensity to like guitars. I even have one sitting right there just in case we want to jam out there. I have a propensity to like guitars. And so this closet is jammed with Yucco's guitars here. Well, what Parkinson pointed out was that as we constrain supply, meaning if we reduce the availability of something, make the closet smaller, That demand reduces because there's less available. And so you just shared that, you know, if you're given a lot of time to prepare for something, an exam, it takes a long time to get ready for that exam. I also suspect you were really good at cramming for exams. Like, we're like, oh, the test is tomorrow. So now you have very little time. What do you do? You pull an all-nighter, you know, toothpicks in the eyes. You'll do anything to get ready. And that is also Parkinson's wiring. Yeah. When we have less time, we become far more efficient in using that time. Parkinson's research also identified we become far more innovative. So I won't belabor this too much, but next time you brush your teeth, watch Parkinson's Law. Make, make it conscious. When I was just returning from a trip, I had a, sometimes I have a full tube of toothpaste and you put that long bead on there. You put it on there. The bead I, and I suspect you do too, that you put on your toothbrush will be significantly more when you have a full tube of toothpaste. But when I was on this trip, I forgot to get a new tube of toothpaste. I had this shriveled up prune-like tube. I got through a full week's travel with an empty tube of toothpaste, and it's because I'm twisting and turning and rolling and push, you know, pushing it. That little turtle pops out of toothpaste, like the whole thing. And I was able to keep using it. And if you've experienced that with toothpaste, that a full tube lasts, you know, a month, 3 weeks, I bet you you can make an empty tube of toothpaste last like a month or 3 weeks or something. That's Parkinson's Law. Our behavior will change based upon its supply. And therefore, since you've experienced that, that's why the system works. What we're doing is we're serving up small tubes and our behavior automatically adjusts. The supply of cash for its independent, uh, needs is reduced and our behavior changes. What's also fascinating is we become more innovative when we have less supply for something. We find ways to, to extract value out of it. This system, I'm telling you, and I'm not trying to be pluggy here, and you probably can't even see it, but that endorsement right there on the front of the book is from someone you may know. Has anyone heard of the Savannah Bananas by any chance? Okay, so Jesse, so Jesse and Emily Cole, they're personal friends of my wife and mine. We met with them when they were starting the Span of Bananas, and I taught Jesse and Emily this system. And so they endorsed, they use this in their home. What one, and actually I subsequently interviewed him, Jesse and Emily, actually both of them talking about this. What they experienced is when they allocated money toward essentials. So they had, in this one particular story, they had a charger between 2 of them. They had one phone charger. And shockingly, you can get by with one phone charger. It was hard for me to imagine with my 50 phone chargers. They had one and it became frayed and wasn't working. You had to bend it in a certain way. They had to duct tape it. But they were using that, they needed a phone charger. They were using the needs to pay for other essential things and they would never break out these other accounts. Their dream was to start a baseball team. And so they found ways to stretch that, charger for months, just getting by and leaning in a certain way and put the phone on a certain way. That's Parkinson's Law, that when we intentionally constrain the supply of cash, you become innovative and you still can extract value of what you have, or you find alternative solutions. And life ain't that bad. And I suspect, going back to our story, we, we said, are you making more money today? Or are you making more money, you know, right when you still got your first job? And I think for all of us, we're, we're making perhaps more money today. And, um, the thing is, it wasn't so bad back then, you know, really in retrospect for some of us maybe, but for most of us financially, it was still like life was still pretty stinking good. And then you, the way we strung things together, that's Parkinson's Law. It's wired into us. So lesson 1 is we need to set up multiple accounts, small planes, the containers dictating consumption. Big lesson 2 is When you constrain available cash, you become more in charge of how you manage the cash. So how are we going to constrain cash? We're actually going to hide some of it away. So I started the system for myself back in 2009, 2008 actually. I started the system. So this goes back 17 years. I didn't, by the way, start this because I believed in the system. Actually, it seems silly just thinking about this, but I was desperate because I had those collection notices coming and stuff. I had to find a way. And so I started doing it. Well, one thing I noticed is very early on, I stole from myself. I'll do it on my overhead here. I remember wanting to go out to dinner. And by the way, we were going to go to a— my wife and I, I think arguably one of the most fancy restaurants, and you maybe have heard of it. It's called Olive Garden. That was our big stop. You know, I'm like, We're going to Olive Garden. And I was so pumped about that. But there wasn't enough money because an Olive Garden for 2 back then was probably with tips $75, maybe. Maybe we could do for a little bit less. And there wasn't enough money in the wants account. So what I did is I said, well, you know, we, we are looking to buy our first house. So we had a little bit of money saved here. I'm just gonna take it from here and move it there. Now, here's the power of this, this system. We are all working at a subconscious level of making money decisions. And another behavioral concept's called the primacy effect. We put more significance in an immediate desire or need than a longer-term one. And I mean, this works in, in, in days. Like, I want something today. We discount what we need perhaps just the next day. Yeah. So you may have done this yourself. You say, you know, let's go. We deserve to go out to dinner. Let's go out to dinner. And maybe, maybe that bites a little bit into your mortgage that's 2 weeks away. And then when mortgage comes, like, oh gosh, we're running tight. Well, if I didn't go out to dinner, maybe we would've been able to cover that. So we, we are playing this at a very subconscious level because we have multiple accounts. This system, what this does is it forces subconscious thought To become conscious. So when I take money from a dream and cover a want to go out to dinner or whatever, I can't— listen, I can still do it, but I can't deny it anymore. It becomes conscious. And with consciousness comes control. Here is the key to financial independence. Financial independence is not making more money. It's not getting rich. Financial independence is getting rich in clarity. And once you have clarity, you can assert control and authority. And once you have control and authority, Then you can dictate a life of wealth. We have to master the financial basics first. In fact, talking about that, when I interviewed people for this book, I— this took me about 5 years to prepare the book in its entirety, but I've been living this for a long time. The vast majority of people, and you may have a friend who feels the same way, I asked them, I said, if you can get one kind of magic wand, fix your finances, what would be your biggest desire? And 80%, I was going to say to the person, but probably 80 to 90% of people said, if I could just win the lottery, if I could just win the lottery. And I was like, oh, that makes sense. Well, what would that do for you? Well, gosh, I'd have, you know, a couple million dollars. You know, the average lottery win, by the way, in the United States is $2 million. Just to give context. There's, of course, these Powerball ones you hear of $600 million and so forth, but the average payout is $2 million and the Frequency. Most people take a 20 or 40, you can even take a 40-year plan. It gets, I think it's a 40-year plan. You get an installment. I said, what would that be? What would that do for you? Well, I'd have $2 million. I could do all these things with it. These same people, maybe you felt the same way, have observed other people that already have won the lottery, either just the lottery of, of life itself or the actual lottery, and see how they fizzle out and mismanage their money. And, um, They say, well, if that was me, I wouldn't do the same. And, uh, I would argue we would do exactly the same because the context, the framing that we all have is our current lifestyle, whatever that is financially. And when we add a lot more money to it, um, our current frame and, and the way we manage money just continues on. And, um, when that kind of wealth gets inserted so quickly, um, the current frame doesn't work. That's The part of my story I didn't share with you, 2 years prior to getting those collection notices, I also lost my house too, the same time. 2 years prior to that, I sold my second business to a Fortune 500, became a self-made millionaire. And I said I would never be that guy. I didn't become that guy by getting a place on— if there's anyone from Hawaii here, there's a private island in Hawaii called Lanai. So, I got a place out in Lanai. Larry Ellison, whoever owns Oracle, bought that island now. I moved into New Jersey, into a town called Mountain Lakes, old money town. And I bought the cars. I needed to show my new life standard because this is now the life I was living. I had no financial acuity whatsoever, and I blew through that money, even though the whole time I vowed I would never be that guy. And I was exactly that guy. I consider now one of the biggest blessings because it forced me to reinvent or re-understand everything I know about finances. So back to the lottery winner. The irony of this is when I interviewed all these people and said, you know, I wish I won the lottery. Average lottery is $2 million. Do you know all of us have effectively won the lottery? The average US salary, maybe you're there, maybe you're above it, maybe you're below it. Uh, is $50,000. $50,000 a year is the average US salary. Uh, if you work for 40 years at $50,000, you, and that's the average lifespan of work, is from your 20s to your 60s, uh, you will make $2 million. So you're already making millions, literally. And if you make less than that, maybe you're not there, or maybe you're making more than that, you're making multimillions then. So the, the funny thing is it's not about making more, it's about managing more of what you make. That's actually a pretty good line. It's not about making more money. It's about managing more of what you make, because then you've set the frame up to be wildly successful as more money gets inserted into your life. But we need to have that cash control in place first. 2 more things I want to share with you, and then Lisa and I were talking about going like through a Q&A. There's this concept called seasons. I promised I'd tell you about what I found when I was interviewing people. Including my own, my own self, asking myself about this. I'd ask them, tell me about your finances. And some people would say, well, I'm in debt. And maybe some of us here experiencing that. I have debt, or I'm retired, or, you know, whatever it is. All these were static states. And in all of the, my understanding of behavioral psychology, and listen, I'm not professionally trained in this, so take it with a grain of salt. Is when we have a I am statement, it becomes identity. You know, I have debt is I am in debt, and I'll prove it to be true and stay there. I suck at math. Listen, if you feel you stink at numbers, you will likely prove you stink at numbers by not trying to get better at numbers. Like that to see that that's the human nature is when we have a frame of who we are in our identity, we feel subconsciously. compelled to be consistent with that, to prove ourselves right. It's, it's part of the ego. Um, so when I started, when I saw people saying, I have debt, I was like, oh, this is a problem. That's the worst way. The hardest way to get out of debt is by saying I have debt, or I, uh, I am a debtor or whatever. So that's when I was like, oh, we need a better framing. And that's when I was like, oh, seasons will do this. Right now in the Northeast here in the US, well, actually in the United States, I was just in Australia 2 weeks ago. They're, they're entering summer. We're entering, uh, we're entering winter now. Fall's upon us. And, um, so we know after fall comes winter, and we know after winter spring will come, and then summer will be here again. There's seasonality. There is no permanence. There's constant change. So in our finances, I want you to use the term season. I am in the recovery season, not the debtor season. We— positive framing is good. So recovery is a positive tone, and season means it's non-permanent. Yeah. So I have a concept called seasons. There is a recovery season. There is what's called a fund, F-U-N-D, fund season. This is where we're preparing for a future event. I don't— all the research I'm doing doesn't indicate that there is a magical retirement age of 67. Quite frankly, for people, that is the worst thing you can do. Not just financially, just emotionally. Some people go into a an offseason when they quiet down, you know, for, for a decade of their lives and say, listen, this is the prime of my life. I'm in my 40s and I want to do all these amazing things. I'm going to get back to work. And that's cool too. So this concept of retirement happening at a certain trigger date is becoming more and more questionable. But we do want to fund or prepare for those type of events. There is an activate season. Activate is where we intentionally spend more than we're earning. I did this when my kids were turning 18. My wife is a huge Disney Disneyland, and that's the one in California. To be clear, Disneyland. I mix them up, and that is like the biggest sin for Disney folks. Disney World is Florida. Disneyland is California. And God forbid I mix those up all the time, and I do not stop hearing it. So we went to Disneyland, which is the better one apparently in California, for my kids' 18th birthday. And it's like it's we're doing the whole thing. We're going big. Enlarge the whole families going. That was definitely an activate season. Now, the interesting thing about seasons, and when it comes to finances, they don't roll through in 3-month increments. They're not like nature. They don't necessarily even go in sequence. You can, you can go into the activate season for a very short period, a couple of weeks if you want, and then change back perhaps to the fund season. Maybe you are in recovery and you exit it, and maybe, and hopefully for none of us, you go back through that season. But it Seasons do change. It happens again. I was literally in summer 2 weeks ago in Australia, and within a 24-hour flight, and it was a monster flight, I landed and it was the winter. I felt like it. It was in the low 30s Fahrenheit here in New Jersey. So, um, these seasons can change very quickly. The 4th and final season is called the balance season. Balance is where we intentionally are saving for future events, but also living in the now. And using our funds that way. Now, I will give you the charts. Like I told you, we conducted this analysis of all these different individuals and found that based upon your income tier— do you make $50,000 or less as a household? That's, that's a tier. Do you make $50,000 to $100,000? $100,000 to $300,000? You know, all these different ranges. Um, and you match it up to your season, and we tell you what the optimal percentages are to allocate this. Help too. To remove temptation, by the way, I told you how we can naturally steal from ourselves. You may even want to hide some of these accounts. So some banks allow you to do that. We, my wife and I, went a step further. We have our dreams account in a different bank, which I don't— and my wife doesn't have access to, but collectively we do, because my wife has the username. I don't have it. I have the password. She doesn't have it. So if we're gonna go into our dreams account, It's like, it's like, you know, you're turning the nuclear keys apparently. Like they gotta say 3, 2, 1, release. Like same thing. My wife enters a username, puts a sticky over, I enter the password, and we're opening up our dreams. This is an intentional mechanism to protect us from our own selves. In our worst moment, we're like, we need that money. We're forced into deep thought and consideration around it. So back to basketball. Maybe you're now a little bit of a fan. Learning this, this Rick Barry underhand granny shot. There is one basketball player in, in the history of professional basketball who scored 100 points in a game as an individual. That's unfathomable. Like, it doesn't happen. And this player, you may have actually heard of this name. The guy's name is Wilt Chamberlain, and he played like in the '80s. Uh, he played in Hershey, Pennsylvania. That is where they make Hershey chocolate. In a game there, and that was the game he famously did 100 points in one game. Uh, and he is an uber athlete. I mean, he was one of the most remarkable players of his time and of all time. Uh, but he was never able to achieve 100 points until that one game. And you, do you know what he did? He shot underhand. One game, he decided to shoot granny style and crushed it. Now, it's funny, crushes finance. I mean, he crushes his numbers, um, and then reverted back to the traditional style and could never repeat the greatest feat of all time. That's the other kind of interesting thing about the system. This is the granny shot. It's super simple. There's less movement stuff. You will see a transformation very quickly, but there is a compulsion wired into us to revert back to the old way because, hey, we're comfortable with it and this new way's not so cool. So I want to give you one departing thought, and I promise you, if you do this by tomorrow afternoon, if you do these few steps, I can promise you the first massive step to financial clarity. You'll have more financial control than you've had in the past, and perhaps the rest of the system— so quite a few steps. Maybe you take weeks or months, or maybe a few years. But you can then roll it out at your speed as you feel comfortable. So here's the big call to action. Step one is in the chat, and you can do this on behalf of a friend too. But what is the one financial concern that comes up most often? So this is something that you worry or wonder about. So do you worry? You know, can we cover the mortgage each month? Is that the one that kind of plays in the back of the mind? Or for some of us, it's like you know. For me and my wife, it was like, can we pay the groceries this week? But it could be a wonder. Like, I wonder, I wonder if we can do vacation this year. Like, we haven't done a family vacation and we want to do it right. And that sits on your mind. In the chat, what is the one financial worry or wonder that you think of most frequently, or a friend of yours thinks of most frequently? And put in the chat. And this is a great way to survey each other. So A lot of wondering about retirement. Yeah, what's your worries or wonders? Not having enough of an emergency fund. Yep, that's a very common one. The trip with the vacation with our kids. Yep, I'm with you, Marissa. Retirement. So retirement is a big frequent one. Okay. Yep. Okay, retirement. So retirement clearly is number one, but the emergency fund— The more specificity, the better. So balancing of living and saving. So Kirby, that's great. And I'd even challenge you a little bit more. Like, what's the one thing you— what would be most important about balancing the living and saving? For me, it's— I want to do a family vacation, and I wonder about— because my kids now are all adults, we want to— I want to be able to pay for their entire vacation. And this is our kind of family reunion, and that's a big Ticket. I mean, that that's probably a five-figure expense doing that, and so I wonder about that a lot. Okay, now that you identified your worry or wonder, step two is this: at your current bank, set up simply one account and give it the nickname of that one worry or wonder. So if it's retirement, say it's my retirement account. I would be more specific about it. It may say. 1 year's retirement funds, or maybe the $10,000 or the $100,000, whatever the retirement dollar, the million dollar, whatever retirement fund is. If it's, can I take the vacation with the kids? It'll be the beach trip. Or for me, it'll be the all-in family vacation is what I'm calling— what is literally what I called mine. The more specificity that you give the name, the better, because then there's no denying what it is. And now you've introduced another member to the table. Actually, we're not even inviting these guests yet, but the new one is the all-in family trip. Okay, so this is at your bank now. Now the last step is whatever income comes in, allocate on that basis. If it comes in weekly or Biweekly or whatever it is with the frequency, allocate enough money to this account every single time to assure that when this event is projected to happen, it's covered. So if it was groceries for me, we, my wife and I go grocery shopping about twice a week. And I wish I could say groceries were $150. I'll tell you what, with my kids, it felt like it was like $500. But now that everyone's out of the house, between the two of us, still, it's still like Like $300 a week on groceries. It's kind of crazy. But we make sure there's $300 in that grocery account. I get paid. I own my own business, but I'm on a— it's an S corp, so I got a paycheck and it comes every twice a month. So $150 the first time, $150 the next time, and it's always $300. That envelope is filled. So for this all-in-family vacation, you know, say it's $15,000. Every month I gotta be putting in about $1,250 into this account, which means every 2 weeks I gotta put in about $675. In fact, that's the exact number. So here's the power of the system. When you do this just for that one account, you have guaranteed that biggest wonder or worry you have is being addressed. It's guaranteed because you're addressing it. But that's not even the magical part. The magical part is now that you've guaranteed that, you see the consequence for the other elements of your life. If you have that one primary checking account, we're taking apart out the biggest, most important financial piece that you feel right now, hiding it away, and then you see what's actually available for everything else. The clarity is in what's left over. You've started to do the optimal foraging theory. You're starting to preserve money. The, a missing element in modern society is the preservation of cash. You've actually started the first big step and watch how your behavior changes according to Parkinson's Law. All this stuff we discovered, you'll see that you start behaving differently. You observe that money differently. The primacy effect no longer works against you, stuff we've all talked about. And then it's just a matter of time that you're like, oh, let me set up one more account and one more account. Maybe 3 months, maybe 6 months, maybe 2 years later, you have the system deployed. Last thing I want to share is I met with— I'll see if I can pull it up. I'll put it in the chat. I met with Jesse and Emily Cole again, and this was only a few weeks ago. I sat down with them. They still use this system today. Their business is generating— I'm sorry, it was valued at $700 million, almost $1 billion 7 years ago. The company was worth Nothing. It was just a brand new startup. They still use the system today. And I would— I'm not saying their success by any means is attached to the money habit system you just learned, but I would argue it was the most important first financial step they took that allowed them to have a company that has that kind of impact and size. If when you're interested, you can click on the link now and save it for later. That's the sit-down interview. We talk about their money. And we talk about the system, we talk about our story together. So when you get a chance, maybe you want to watch that video and you'll get a kick out of it, but you'll also learn about more about the system.