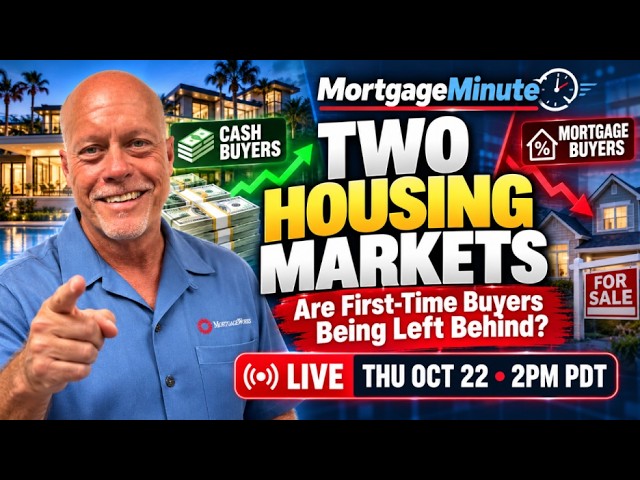
In this Mortgage Minute episode, host Art Alvarez (MortgageWorks) and guest Jeff For Local Marketing discuss the emerging split in the U.S. housing market: a cash‑rich segment that can act quickly and a financing‑dependent segment of first‑time buyers who face affordability challenges. Citing a recent interview with real‑estate expert Josh Altman, they explore whether the door to first‑time homeownership is truly closing or if viable financing strategies exist. The conversation covers a range of topics—including low‑down‑payment loan programs (conventional, FHA, VA, USDA), seller‑contributed closing‑costs and rate buydowns, the strategic use of mortgages to preserve liquidity, regional affordability differences within the Coachella Valley, and how to evaluate buying now versus waiting for potential rate or price changes. They also address common myths such as “buy now, refinance later,” and emphasize treating a first home as a stepping‑stone rather than a forever home. Throughout, the hosts encourage prospective buyers to run the numbers, secure strong pre‑approval, and make decisions based on personal financial fit rather than national headlines.
Chapters
What if I told you there are actually 2 Housing markets in America right now. In one market, buyers have plenty of cash, lots of choices, and the ability to move quickly. In the other, families are struggling to buy their first home, wondering whether they should wait for interest rates to come down or home prices to become more affordable. Recently, real estate expert Josh Altman described this growing divide in a televised interview. He even suggested that the door to first-time homeownership is getting harder to open. But here's the question I want to ask you. Is that door really closing, or are there opportunities and financing strategies you simply haven't explored yet? I'm Art Alvarez with MortgageWorks, and today on Mortgage Minute, we're going to look at what this means for homebuyers right here in the Coachella Valley.
That's a fascinating way to look at today's housing market. We've talked many times about interest rates, affordability, and buyers sitting on the sidelines. But what caught my attention about this interview is the idea that wealthy cash buyers and everyday homebuyers are experiencing 2 completely different realities. Are you seeing that same divide?
There really is a difference in the way buyers approach the market depending on their financial resources. Someone purchasing a multimillion-dollar property with significant cash reserves has options that a first-time buyer may not have. They can move quickly, they're less dependent on mortgage financing, and in some cases, they're using their investments or existing equity to structure the purchase. But here's something people might find surprising: just because someone can pay cash doesn't mean they always do. Many financially successful buyers still use mortgages because they want to preserve their liquidity, maintain their investments, or use their money for other opportunities. And that brings us to an important point. A mortgage isn't necessarily a disadvantage. It's a financial tool. What matters is how intelligently you use it.
That's interesting, Art, because I think a lot of first-time buyers hear that cash is king and immediately feel they're at a disadvantage. If someone doesn't have hundreds of thousands of dollars sitting in the bank, how do they compete?
First, Jeff, I want people to understand that they don't necessarily need a 20% down payment to buy a home. Depending on their qualifications, there may be conventional financing with as little as 3% down, FHA financing with 3.5% down, or even zero-down options for eligible VA or USDA borrowers. Of course, eligibility, property requirements, mortgage insurance, and other costs all need to be considered. But the bigger opportunity is understanding how the loan is structured. For example, some sellers may be willing to contribute toward closing costs or an interest rate buydown that can potentially make the purchase more affordable without requiring the buyer to come up with substantially more cash. And there's another advantage buyers sometimes overlook. A strong pre-approval, a realistic budget, and an experienced lending team can make a financed offer much more competitive. You may not be able to match a cash buyer on every property, but you can absolutely position yourself to succeed.
Let me bring us back to something Josh Altman said. He warned that the door to first-time homeownership is getting harder to open. That's a pretty powerful statement. Do you believe buyers should be concerned about waiting too long?
I believe buyers should be concerned about waiting without having a plan. That's the distinction I would make. We don't know exactly where mortgage rates will be 6 months or a year from now, and we certainly can't predict what home prices will do in every community. But we do know that affordability depends on more than just the interest rate. It also depends on the purchase price, property taxes, insurance, HOA fees, the down payment, and your overall financial situation. Here in the Coachella Valley, a buyer looking in Indio may have very different opportunities than someone searching in La Quinta or Palm Desert. So rather than asking, is this the perfect time to buy? I encourage people to ask, what would buying look like for me today? Let's run the numbers. Let's look at the payment. Let's understand the options. Then we can make an informed decision instead of simply reacting to headlines.
There was another comment in that interview I really liked. Josh said, your first home doesn't have to be your forever home. And I think that speaks directly to a lot of buyers who are waiting until they can afford their dream home.
Absolutely, Jeff. Sometimes buyers get so focused on finding the perfect property that they overlook a home that might be a great first step. Maybe the home is a little smaller than they originally imagined. Maybe it's in a different neighborhood, or maybe it doesn't have every feature on their wish list. That doesn't automatically make it the wrong home. For some buyers, a more modest first purchase can be a way to begin building equity through regular principal payments and potentially appreciation over time. Now, I want to be clear: home values can also decline, and buying and selling homes involves real costs. So I'm not suggesting someone buy a home today just because they think they'll be able to sell it for more money in a few years. What I'm suggesting is that we consider The big picture. If the payment is comfortable, the home meets your needs, and you expect to stay long enough for the purchase to make financial sense, your first home can be an important stepping stone.
So here's the question I know people are asking. We're getting close to 2027. Should someone who's thinking about buying a home get serious now or wait and see what happens next year?
My answer is that they should get serious about understanding their options now. That doesn't necessarily mean they need to purchase a home tomorrow. It means they should know what they can comfortably afford, what financing programs they may qualify for, and how much cash they'll actually need. And they should compare the cost of buying today with what waiting might mean. If interest rates decline, that's potentially good news, but lower rates could also encourage more buyers to enter the market, which may increase competition. On the other hand, Prices or borrowing costs could move in a different direction. Nobody can guarantee the outcome. And there's one other point from the interview I want to address. You've probably heard people say, buy the house now and refinance later. Refinancing may be an option in the future, but it isn't guaranteed. Rates, equity, qualifications, and closing costs all matter. That's why I believe a home should make financial sense based on the mortgage terms available to you today. Not on the assumption that you'll refinance later.
I think that's a valuable distinction. The big takeaway isn't that everyone needs to rush out and buy a home. It's that buyers shouldn't assume they're out of the market until they've explored their options.
That's exactly right, Jeff. And here's what I want everyone watching or listening to remember. Don't let a national headline make your home buying decision for you. Yes, affordability is challenging. Yes, cash buyers have certain advantages, and yes, the housing market is changing, but that doesn't mean your opportunity for homeownership has disappeared. You may have more financing options than you realize. So whether you're thinking about your first home, planning a move, or trying to decide whether to buy now or wait until 2027, I'd welcome the opportunity to have a conversation. Let's look at your numbers, your options, and your goals, because the right time to buy isn't necessarily when everyone else is buying. It's when the purchase makes financial sense for you. I'm Art Alvarez with MortgageWorks. Thanks for joining Jeff and me for another Mortgage Minute, and we'll see you next time.