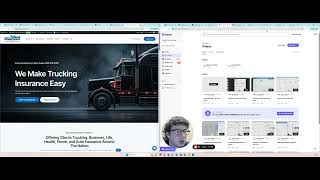
Hunter Nelson walks through a business portal that centralizes sales tools, marketing resources, underwriting appetites, training materials, and agency policies in one place. It includes customized GPT chatbots for quoting and risk management, image-generation tools, and carrier resources designed to support commercial and transportation insurance placement.
Chapters
All right, let's do an introduction to the portal here. So this portal is going to be the lifeblood of everything we do here.
Okay.
So going through this here, we've got the chat bot, which is chat GPT. And when you go into chat GPT, you're going to see different GPTs that I've trained to help you. So if you need some advice on sales, like, hey, I, my cold calls are not going real well. I've got this thing trained with our sales script. I've imported sales videos and this thing has got paragraphs and paragraphs and hours and hours of videos in it. Risk management and compliance is going to be. It's got, it's got documents from seminars, we've taken tests, we've taken everything telling us about, about everything with risk management compliance. Hey, how does the MCS 90 work? Blah, blah, blah. This thing right here is just a quick question. It's been trained to handle quoting and servicing and you can go in here and take quizzes if you want. You can, you can have it tell you a little bit about, hey, how do I quote this thing? What I do in this situation? Don't worry about.
Asking this thing like, hey, who'd I quote this with?
Because there are so many different guidelines. That's impossible. And yeah, it just doesn't work out for Chat GPT. Marketing is going to be, hey, write me Facebook posts. So it just, it streamlines our marketing process and such. Go in here about writing blogs and all sorts of stuff. Again, when you write the blog, you're.
Not going to go in here and.
Just use this thing, but you are going to or just use exactly what it spits out. But it's supposed to be giving you an outline. Don't worry about ownership. I am creating another one right now called the Risk Management Expert. This is going to be when you upload a CAB report, it is going to tell you right here, hey, here's a bit about that CAB report. Here's some risk management mitigation plans, such and such. So there's be more and more come to this stuff, but you're gonna have to take with a grain of salt. Obviously it's, it's Chad GPT. It's AI. It's not perfect, but it's definitely going to help you guys a lot out or it's gonna help you guys out a lot. It's supposed to be fuel to the fire image generation. This is just an AI that you can go type in a something and it'll spit out an image for you. This is for marketing and such call notes.
This is really just. You guys don't have to worry about this deal.
Here's our daily value or here's our values. Here's our goals. What we're hitting here are the walkthroughs. So we have our agency information. For example, private means it's only me. I can only see this. How does our agency and employees compare? So as we can see right here, here's the average new production. Here is everything. Here's the case study, you know, how and why do we fire a client. Here's our values. This is something that's very important to our agency. So we always are going to go over this stuff. You know, we're always going to follow this stuff. Ethics. We always do the right thing.
Hustle. We are. I, I'm just a competitive guy.
I, I hire people who are also competitive.
You know, granted, I compare us to the average agency.
We are right now. We're not even three years of business and we are dang near. What am I, what am I thinking here we are growing like five times.
The average agency's growth level.
So it's just crazy stuff and I want to keep doing that and I want to get to the top 10% of agency sizes and stuff. Constant growth. It is always.
This is just something important.
This is what's helped me out. It is always your fault.
That is just something you got to think about. You know, granted there'd be some things.
Out of your control, but it's how do I. At least then how do I handle that situation better?
That is something that we're always improving on.
Always reading policies, always learning. I'm only been in the industry for three years and after three years I still am learning a ton.
Culture is the most important thing.
I, I don't want anybody be coming into the office, not looking forward to it, having to worry about what, what I think of them, what their peers think of them. We are, we offer a good culture here. I do not want really to anybody dislike their job. And the culture should be. We're here to improve each other and push each other and grow together so everybody here can make a ton of money.
Because insurance is.
A very opinion. There's a lot of opportunity in insurance, but you got to kill it. And you're not going to kill it if you hate coming to your coming to the office. Integrity, you know, God is good, you should be too. Relationships, relationships are a lot in insurance. You know, you've got a good relationship with an Underwriter, he's going to help you write more business. You got a good relationship with, with a buddy who can send you business or another business partner can send you business. You're going to write a lot more relationships with big clients.
What keeps them, you know, it's, it's.
Tough going after big clients because they're dang near the term is married to their agent. Hopefully we have a lot of our agents who have clients who are married to them because then they're not going anywhere. And that, that business is going to keep growing. Your commission going to keep growing. You're like doing work with them, they're like to work with you. And everybody just wins. Reliab reliability. Nobody cares. Whatever. We deliver results. You know, if I go quote, if I go quote five people and I got nothing for them. But I told them I'm gonna take care of it and sign a bor because I got it. You better figure something out. You know, if, if we got a client and you know we can't get a hold of the underwriter for the renewal, it don't matter. Go find, go find somebody else to talk to. I bet you there's another underwriter that.
Can help with the rule.
There's always something I just, I hate.
I called the underwriter twice.
I can't do anything. So that is just something that we live by. This is what helps us succeed. We have our goals here again, where we stand, how we show up online, just branding standards is for the marketing people. You know, we market like a big agency or a big company, like progressive, Progressive logos, the same size, same color. It's in the same spot of everything. You know, their commercials are the same. They're not having a real heartfelt commercial. The next one's funny about, you know, leaving the football game. It's, it's, it's all, it is all the same thing. You know, Geico's got the gecko and it's always a joke of a commercial and yet they do really well. So it's, it's always the same thing. They're not coming around tomorrow. Advertising, like pure insurance, you know, they got two different strategies, but they always stick to the same thing. So consistency is very important with marketing. You know, we've got our associations that we're part of. So here you can go learn to get certificates. This stuff is very important. Our cyber incident response. We have cyber insurance. We've, you know, we have ENO insurance. This stuff is very important. If we ever get a cyber attack, if we ever risk we ever have an E O claim, you need to know this stuff off the top of your head. If you're wondering your commission is.
Here.
Is a cyber coalition or coalitions who they, who the cybers through. That right there is just a risk management portal. Really only the managers have been worried.
About that industry standards.
Here's just a keep track of our licenses. You're not like, hey, I don't know who, where we're licensed at. It says who's licensed and where we're licensed. You know, Risk management also with the license, the send me a license, I can put it in there.
You know, you know, risk management, everybody.
Should know this stuff here too.
So this is, this is ENO Risk Management provided by Utica. Utica offers some of the best coverage out there for eno. And we obviously don't want to have any, you know, claims and you know, claim is errors and omission. So everybody in the agency, unless you're 1099, even if you're 1099, you still, you're responsible for the whole thing. You're responsible for the deductible because you have your own, you know, policy. So hopefully you offer your, your E O is up to the COI standards or the, you know, contract standards. And then if you're an employee, if you're like a csr, for example, you do pay the ENO deductible if you're responsible for a claim. This is standard practice among every, every agency.
Don't want to scare anybody, but, you.
Know, obviously we don't want to turn it, you know, claim. And I would hate for, you know, one employee to be really, really uptight about it and really doing their due diligence, another one just kind of slacking off. And then we all kind of, we're all going to get punished for it because we can lose carriers or, you know, it could be more expensive, which means I got less money to spend on marketing, less money to pay everybody all sorts of stuff. So you got that. You're going to have your agency zoom. You're going to have binding claims, COIs, a core forms. This is going to have commercial resource for commercial lines, endorsement and renewals, marketing, hiring. And this is like if you're a new hire, you're going to go in here, which you should have already done, but creating your email signature how to do that. If you're studying for your license, here's how you do that. Here's just a walkthrough of everything. This is kind of what we're doing. But this is a little more like baseline, real quick type deal. Here's our commission, new hire documents, being successful in sales, you know. So yeah, all this stuff, scripts are cold calling. You're going to have scripts for rate increases, cold calling, claim and take. You know, here's how you set up your voicemail. And then you're going to have companies. You can go in here and you can see all these different companies. So brokers are an mga, so they're like another agency. But instead of working with clients, they work with agents.
So I go to them.
Like Amwin for example. AM's gonna have 600 carriers. Well, shoot, I can't get 600 carriers to be appointed with. So I just work with AM ones. They're gonna take 5% of my commission and then I can go place business with them. I've got commercial lines, I've got contractors. So contractors, personal lines and transportation are our specialties. Non insurance services or non insurance companies are going to be, you know, like a sin, which is a finance company for us and other other sort of stuff like our phone systems, our email, our security guys. But if I'm gonna do transportation, I've got all the lines of business. If you're not sure what the heck commercial property is or commercial umbrella, go.
Back in here, go look the resources.
And figure that stuff out. If I got somebody in South Dakota and let's say it's a general freight guy, if you have no idea General Freight versus Hazmat is again, go back into the resources. Under Trucking resources, you'll find Trucking 101 tells you all that type of stuff. So I've got all these companies here now. Now all these companies. Well, I'm just gonna make sure this real recording.
So we're good here.
So all these companies are not created equal. You know, I've got Prime and I've got Northland right next to each other.
They both pop up.
Both. It couldn't be completely different companies here. So if I go into Prime, I'm gonna see there's a carrier rating. This is how badly we want to place business with them. And then I've got an overview video telling you, hey, here's our past experience with them. Here's the kind of stuff they like, maybe just a little bit of like, like opinionated stuff on them versus having. Here's how you submit business and here's just some notes on them, you know. So as you can see, I don't have really a whole lot of information on them because they suck I don't have a piece of business with them. And you know if we really need them, great. Once I go find out a lot about them because I'm going to start doing business with them then I'll put it in here and then I'm going to go to Northland who is the complete opposite here they've got an eight. Honest to God I probably should even rate them higher. But one thing you're going to see up here is you've got AMWINS in parentheses after it. So Northland does not work directly with retail agencies.
They do have two retail contracts but they both have over $100 million books been around for about 100 years. So they'll say we are not quite there yet.
So we're in accessing through ambulance. Just like how 99.9% of the other.
Population does as well. I could see they offer commercial lines. You know they do offer general liability and cargo and stuff like that and physical damage obviously. But they, but I put those lines in as. As model line. Will they offer monoline general liability and trucking account? No, they will not. Here's the states that write in. Here's the piece of the business they write and I can see the markets. If I see markets markets is Northland. I can see other markets that Amblins has because I have their brokerage up here. So instead of having to go through.
And filter just kind of keeps like.
A quick check right there. I can see the coverages they provide. So that's what I was talking about. They offer roadside assistance. They offered a deluxe coverage which is a package add on to sounds like the physical damage because it's personal effects, diminishing deductible like or get deductible sorts of stuff. Here's the information needed for a submission. We're going to send it to Joe.
The Appetite underwriting guy or the underwriting.
Is going to be underwriters. So here's our underwriters and appetite.
You know it's going to give a little overview right here. Northland is very similar to Great West. They take about anything for cargo. You know what this is? I. I'm sorry, this is this mistake. I'm just realizing here. This is from an old carrier. They will take about anything that are more competitive on non semi commercial auto. That is for Nico. Northland is very much like Great west offering some of the best forms. Forms are policy documents. Forms out there and right dang near all cargo types. So to write dang near all cargo types and here's the cargo that they will and will not take. So they might take dump trucks but again I'm not sure and I don't want to put anything in there Household good movers. This stuff's not even hardly trucking related. Taxi, limo. The only thing they do not take that I'm aware of is hazmat. So they require two plus year for cdl. Two plus years in business for most meant to be states. As you see there's a little bit of this that's work in progress. The guys who we use more often are more dialed in. Will take new ventures with a minimum age of 35, 6 years of CDL and the owner is the only driver with one truck. States like Texas, California, Florida will require additional years of business. They will consider one to two. So they will not take the new ventures. Will consider 1 to 2 with a minimum age of 356 years CDL loss free and one truck. I have a loss for here because this new ventures tough states require three years of business some even being five. They want absolutely very little losses if not any. And so there is how you're going to choose those guys there yet the websites right here so you can hop in the website start quoting keeps it very easy. Tells you the. Tells you the lines of business and everything. But everybody you're going to get that pops up. You'll want to check the underwriting guidelines because there are so many differences. I can't, I can't put a filter in there for Northland where in this state they require two years CEO experience with drivers. The only or truck is only driven by the owner and blah blah blah blah. It just gets to be a nightmare. I'm going to put one final thing in here too called other markets. This can be for trucking but other markets as in guys that we don't want to use. I want to keep this simple. I want all of our business be in place with a couple key carriers. But if we had a 500000 account that walks in the door and Tip national is gonna be the most competitive on it. Well shoot, I'm not gonna pass that thing up because I want to Write it with 104 and they won't take it. So I don't have no, I have no choice or they're just not competitive. So I'm gonna put other markets in here so we can AOR it. We can you know, use them if need be. But they are, they do come in handy for once a while. Intake forms. Don't even worry about this. I Will probably delete this mortgagee lien holder and coi. Here's just a bunch of information here. So they're like oh yeah, I'm with homeowned serve. Okay, perfect. So here's Homeland service information intake form scratch. This is just the dashboard up front here. Training and creative proposal. I will get more into this but this you can create a proposal, client can accept it and do such and such on that end. Here's the now that's the back of the website. The front of the website we will use too. So just so you guys know, here's how you get to the portal. Here's a client center so they can log in and hop into.
Now certs.
Where they could pull cois, ID cards and everything on those lines. So as I can see my account, I've got all my stuff here, my documents and it's really pretty dang slick. I can go in here and report a claim if I need need to. And then you got get a quote which is what I'm going to show you guys. Our team, you know you can schedule appointments. We have our partners, our partners. We do get paid commission on these guys. So we're here to sell insurance. But if you got new venture, I mean heck yeah, every new venture go in there and sell them factoring a fuel card, get them a dash cam, get them an E.L.D. they need loads. So go get them referred to Truck Stop if it's an ugly account, any risk management great, go send them to Synergy Solutions. This is. We don't get paid commission on MVR check but it is just like an added service where they get a 10 discount for using our code. So it's just something that you can kind of say like hey you know if you use us you get some extra discounts, home warranty and then your BMC 84 bonds, they can go buy this online. You can get, you can start right there. They have a broker list. So if you had a new venture you can send them a broker list. Just hey guys, if you need some people, here's a broker list. MVR request our blog Frequently asked questions. Here's our products page. But the main thing I want to show you guys is get a quote. So if we had a new client coming in, we want to quote them through the front end of the website because it is time spent on the website which helps our SEO. SEO is search engine optimization which means more people are going to come to our website, it's going to pop up more and they could find a website easier. You go click on trucking application, ignore fast trucking inquiry. If you click on it, you're going to see that it's just phone number and email. Business, contractors, personal lines, trucking, you know, hop in here. This is 10 pages to it. Start filling out the info. It's going to keep it nice and easy. This is all the information that's needed for a quote and I'll get more into that later. But that is an overview of our website, the portal, whole shebang. So this be the lifeblood of everything you're using. Go in there and use this stuff and get rolling.










