Q1 2024 State of the Market
Q1 2024 State of the Market is a market briefing (video) covering New York City commercial/residential investment-sales activity for Q1 2024. Citywide dollar volume and trades improved quarter-over-quarter (e.g., ~20% increase in dollar volume; annualized ~$12B; 476 trades), though still below 10-year averages. Borough-level: Manhattan saw large dollar-volume gains; Brooklyn showed increased transaction counts despite lower dollar volume (Brooklyn annualized ~$522M; 46 transactions annualized to 184/year), Queens had notable trade increases, Bronx/upper Manhattan remained low-dollar but active in counts. Themes include cap-rate movements, development pipeline disruption from 421A expiration, good-cause eviction legislation uncertainty, financing/CMBS liquidity returning, and several highlighted property trades (multifamily, industrial, retail, conversions).
Two or three presentations just because there's so much information to go over. Now you can see that Pat is remote today. He's got something that he needs to attend to shortly thereafter. So we're going to actually going to jump right into the Brooklyn state of the market. Well, actually you know what, Pat, if you've got a little bit of time, why don't I give the big picture New York City so people can get a big sense of the number and then instead of jumping right into Manhattan, we'll go to Brooklyn and then we'll come back to Manhattan. I'm sure Brooklyn will be more than happy to not have to play second fiddle to Manhattan. So we're happy. Take the lead here. Okay, great. So what happened? And now I'm going to go ahead and share screen so hopefully you all can see this. Does that look good, everybody? Okay, we're, we're in business. Okay, so what happened in the first quarter of this year for New York City sales? We love green arrows, especially when they're. Yes, pointed up. We had a 20% increase in the number of dollar volume quarter over quarter. So you can see here that we are now annualizing for 12 billion of sales. Yes, we are still well below the 10 year average of $31 billion. But we are at least headed in the right direction. You could see strong quarter over quarter growth from Manhattan. And Pat, we're going to have to talk to you about these Brooklyn numbers because the dollar volume here was down. But I know you've got a positive story within that as far as the number of trades. Queens actually having a big quarter and that's certainly our intention to cover that borough next with its own dedicated report. Have Joe Moran here, who's a senior associate on our team who's helped preparing the information and we'll, we'll step in if we need any commentary from him. And then we, we do see Bronx, upper Manhattan again, not a lot of dollar volume up there, but traditionally that, that hasn't been what's driving the market. So let's talk about what's happening with the number of sales. Again, some positive lift here. 476 trades. And here it is that Brooklyn saves the day with 37 trades representing a 37% increase year over year. Manhattan did have a slight decline of 9% less transactions quarter over quarter with 50 trades. Queens again. And this is a trend we're gonna be talking about where dollar volume in some cases might come down. But we're also looking at the number of trades that are happening so here we see an uptick of 40% of trades. Now if you look at annualizing New York city sales for 2024, we're at 476, still below the average of 874, the 10 year average, but again headed in the right direction. So now with that we're going to flip. Well actually let's go ahead and take a look at the, the year over year changes and maybe we will ruin the end of the movie here for Manhattan. But yeah, New York City again looking at 2023 and annualizing that first quarter of 2024, we see a 24% uptick in the dollar volume. 20 Manhattan, huge uptick, 42% annualizing, $8.66 billion in trades. I'll circle back on why that happened. Number of trades here, again, Brooklyn really helping out. So annualizing to 476 trades across the city, that's a 3% increase. But Manhattan here, the number of trades actually went down. Now I think this would actually be a good time before I introduce Pat to give the Brooklyn numbers to also remind you all that what we are tracking now, and this is actually changing for retail as well, is that we are only tracking $5 million in plus sales. So when we talk about total dollar volume, number of trades, we're talking about the major food groups, we're talking multifamily, we're talking retail, we're talking office development. Right. $5 million and up. And then you're gonna see in Brooklyn, we're actually tracking quite a bit, few more trades. Okay, so Pat, you're on. Tell us what happened with the dollar volume and number traits here in Brooklyn. If you want to come off mute.
Sure. So far this year, Q1, we've seen a dollar volume of $522 million annualized. That's about 2.1 billion. It is easily the lowest dollar volume since 2018 when we began tracking these statistics. Tom, it's less than 50% of the 10 year average. What's interesting, and James, I think you touched on this, is that the, the transaction volume is actually up. We have 46 transactions annualized at 184 for the year. If we, if we keep on this Track, it's a 31% increase from the previous quarter, still below our five year average, which should be up around over 200. Tom, this tells us one simple thing and that is that the middle markets and lower middle markets continue to trudge along, are picking up speed actually, while some of the larger institutional transactions are, are less active than we've seen unsurprisingly, Multifamily represented about 35% of the trades. I would chalk that up to not only the, you know, multifamily assets tradition share in the building stock overall, but also to the assets performance. We're no strangers to the fact that we've had incredible rent growth in the boroughs specifically in the last two leasing cycles, really the last three leasing cycles coming out of COVID I think people are bullish that that will continue. We see in the news rents leveling off in the winter months. But this spring will be a real, a real telltale as to whether we continued that, that story. You know, I think we could dive into some of the comps to go over them specifically if you want to.
Let's, let's talk about the number of trades and, and by the way, anyone who wants to ask a question, feel free to pop it in the Q A. And Sam, you asked the, thank you for joining. You had asked when we talked about the quarter over quarter increase, what are we referring to? And that's a great question because sometimes we can look at what was the similar quarter of, you know, the year before. But no, we are comparing fourth quarter to the first quarter. So you can actually see quarter over quarter, hopefully how we're building some momentum here. So the number of sales here. And Pat, this is really where you saw a big boost here as far as the number of trades, right?
Definitely. And so that uptick again, representative of many smaller transactions than we would typically see in a given year. No surprises there but, but we're happy to see an uptick in that space for sure.
Great and multi family leading the way with 21 trades and then industrial with eight. We don't, we don't see a lot of industrial trades in Manhattan. So we're going to be looking forward to talking a little bit more about some of those. So let's, let's talk about some of the top trades in Brooklyn that took place and I know we got a lot of them. So we're going to kind of speedy.
I'll give you, I'll give you the Cliffs Notes. So 97 Grand Whitnick purchased from Madison Realty Capital. That was an expiring 421A with just a few years left. I think we're actually going to see more and more of these deals hit the market. Possibly trade becomes very attractive from a basis perspective to acquire assets. Assets like this well below replacement cost. That was a $457 a foot, about a 7% abated. Cap but again expiring for 21 with a little bit of a rising tax Burden to contend. 269 Henry was a Carlisle purchase I believe that was in contract for a long period of time. Low cap rate representative of you know great opportunity as they saw it. On the development side there's no real. It shouldn't come as a shock that there are not a ton of multi family ground up development sites trading with the lack of 421A. I'll skip to the end which is 962967 Bushwick was a 40,000 square foot buildable square foot site traded for about $170. ZFA was a vested 421A site. Again a lot of the bigger vested 421A sites not trading people concerned about hitting their timeline completion date in June of 2026. And so smaller deals like this still do hit the market. We are seeing them trade but fewer and fewer.
Yeah and I believe Pat just because it's a big one. The 2731 W. 12th St. I remember this one had been kicking around for a industrial land National Grid kind of challenging site to get to but. But really sold as an industrial type play. Is that correct?
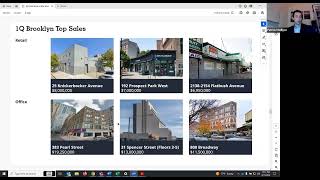
Absolutely. So I think the point that I was making is that in a normal year we would see a lot of multifamily in this development pipeline. And here we're seeing one very large industrial piece that sold to Prologis from National Grid. Again a very long contract. The Moore street assemblage is a commercial opportunity that was a stalled site. It was purchased by Bungalow Projects and Fortress from Abe Lifers Co. And then of course the Bushwick app deal that I mentioned here. But in a normal year you'd expect to see many more multifamily lack of 421A being not a shocker there. On the retail front we saw a lot of some user activity and some investor activity. 25 Knickerbockers was purchased I believe by a user an Art Gallery 192 Prospect Park West. This curved looking asset here was a anchored by triple net lease with Chipotle. Very nicely located piece of retail. So happy to see those deals go through. We move on to office. 383 Pearl street was the largest office transaction in the borough. Again this was another user Brooklyn Friends School actually purchased this and it was previously occupied by ASA College. So almost a user to user type of transaction. And then if we move on to industrial we can next slide there. Yep. So these were all vacant assets, which is kind of surprising. 69th street traded vacant, possibly a bit of a covered land play transaction there. 24th street also vacant, as was Lombardi. So I think there's a recognition in the market that you can get into these assets, tenant them. Well, it's still a very, very solid business plan and one that people are eager to get involved with. On the conversion front. We had three deals that were all sort of pretty interesting in their own right. South 6th street was a previous theater and that will be a conversion to residential. 232 Delphi obviously was a church. We can tell by looking at it was a rental. Is going to be potentially converted to a condo purchased by KSR. And then the last and final one here, 657 Fifth Avenue was a long time IMD asset encumbered by law. Flaw tenants finally vacated, delivered vacant, I believe, free of any IMD tenants. And that will be a conversion to, you know, a residential project in the hands of a local developer.
Pat, well done. You. You wrapped up 18 sales in the seat of the Brooklyn market. And I, I think under 10 minutes. So that, that was impressive.
So I think as a closing, I couldn't agree more, that Brook deserves its own report here.
All right, well, thank you. And, and you're. I know you gotta run, so. So feel free to sign off.
Okay, thank you.
All right, so back to Manhattan. Sorry if I'm getting you seasick going through these slides like this, but Brandon, so this is kind of interesting. I know we were talking about in last year, if you see that 70, almost 70% of the sellers were private. We saw a lot of private activity, high net worth, foreign. I know when there's not a lot of trades, we don't want to read into these things too much. But this is kind of interesting that private is kind of swinging back to kind of what its historical range was of sellers. And look at this. The institutional sellers more than doubled and so did the cross border sellers. So this is kind of. Could this be a signal that maybe some of the bigger institutions are willing to transact now? And if so, I think maybe a lot of our listeners would actually think that that's good news because I think everybody's kind of waiting for the floodgates to open here.
Yeah, it's possible. I mean, I definitely would like to keep tracking it. I mean, I think you're probably potentially looking at a situation where loans are coming due and rather than pay down the loans, it's. It's a decision to sell. To your point earlier, It's a little bit, the sample size is pretty small so I'm hesitant to read too much into it just because we only have a quarter of data. But, but that's very possible. And then in terms of private sellers, you know, maybe some people that, you know we're going to sell no matter what in 2023, in 2024, first quarter we're anticipating rate cuts, decided to maybe hold off. Now that seeing treasuries creep back up, maybe the decision changes. So it is a little bit early to decide what that data means but all potential options I would say.
Okay, now let's talk about what's happening in multifamily and Brandon, before the Q and A blows up, I think I'm surprised you're not up there in Albany trying to figure out what's happening here. So a lot of talk about good cause a lot of talk about 421A and trying to cut a deal with the state budget being worked on today. So what, what can you share with us so far? We can maybe talk about the 421A piece as we talk about development but just for good cause, you know what, what are we thinking here? What, what can we expect?
Sure. So the, the two ideas and again I want to preface this with it's so early and we don't really know much of anything. We just have heard things float around would be you know, good cause eviction with you know in terms of rent growth it would be capped at the lesser of 10% or 5 plus inflate or 5 plus CPI and then in terms of IAIs would flip over to 30,000 instead of 15,000. The real estate community is going for 50,000. So a compromise of sorts I would say my biggest concern and I talked to you about this earlier is seeing, starting to see a fraction amongst multi family owners. So you have the owners of call it rent stabilized product and you have the owners of luxury product and it appears as though agendas have kind of diverged and I don't think that's good for the real estate community because everything needs to kind of align. So that's one thing I'm sort of tracking. But yeah, it's early. Let's see what happens. I, I, you know, I don't want to, I don't want to make any guesses but those are kind of what's being floated out there. I, I think any kind of legislation is.
Yeah. And Brandon, I was even going to say that revenue is even saying that they're still reviewing. I mean this is happening live right now as we speak. So it's, it's evolving. You know, revenue certainly needs to weigh in. If we're talking, we'll talk more about, you know, their thoughts on 421A and what's happening there. Brandon? The only thing, and again, just that I had had read is that maybe there's going to be an exclusion. If there is good cause, will certainly luxury units be cut out. So we don't. Doesn't sound like we know at what, you know, monthly rate that would be, but that maybe that, that would be some kind of.
Yeah, and that was the divide I was referencing because I think any exclusion is a positive for real estate, in my opinion because there's no benefit from having more groups put under legislation. I think the, the biggest thing that's. Sorry, there's no negatives adding workers. I think the biggest thing, if it were to go through, I think it has a much bigger. My guess is in the short term, I think things freeze just while people digest everything. I think in the long run it has a much larger impact on value add buildings because it's impossible then to time your investment. That is where I think it's going to be interesting to see how that eventually settles. Less so than the, the renovated apartment buildings where, you know, if you get 10% rent increases or 8%, it's more of like a California style. I don't think it's as impactful in terms of, you know, the numbers and the metrics. I mean, you can see here it's such a small sample size. There just weren't that many. There's only 20 sales, which is on the low end. You know, dollar per foot is down 25%. Cap rates up there. I mean, I think this gives a good barometer. I think every sale is so different. But yeah, I mean, to your point, we had the, you know, the dollar volume jumped because the air sold, which was like the first big apartment building to sell in a while. So I can quickly run through these. I'll be a little bit faster than that. So 200 West 67th Street. That was a private family that owned it. For a variety of reasons, they elected to sell. There was debt, there was family dispute. The buyers, Carlisle and Gotham generally can view Carlisle as a low cost of capital buyer. There's ways to implement some light value add strategies. I mean, there's a lease up in general, management efficiency, potentially charging for amenities. You know, I think at the end of the day this will look like a great investment. Great location, great Asset. So that East Village portfolio, that was Kushner to Penn South. I think just for everyone's, you know, pronounce. I mean that was well into, you know, mid six cap with assumable debt. IO for another call, five years. So again that, that came with assumable debt, which led to a high cash on cash. And that was something that the buyer was excited about. You know, potential cap rate compression makes that deal look like a home run. 120 and 125 Riverside. So that was Benthold Green Oak, heavy rent stabilized component that was purchased by an Israeli buyer who has been very active. They took a major haircut on the sale. I want to say off the top of my head, it was 64%. So just again, I think it just drives home the point that unstabilized housing has taken a beating on. In terms of cap rate compression or sorry, cap rate expansion combined with higher interest rates. It's just, you know, it's a recipe for, for losses. Unfortunately, if you have to refi that that property unless you're willing to put a lot of cash in.
Brandon, do you have any cap rates to report here on these trades?
Yeah, I can pull it up. I should probably have it in front of me. 200, 167. There was a lot of data floating around, I think depending on whose numbers you can look at, you know, because their noi had a lot of. There was a lot of vacancy in the building at the sale. Assuming fully leased. You're north of a five for. For air.
I can pull up while you're looking for that. I, I can talk about the land sale market, which is, you know, again, this, maybe this is kind of a theme. When you have less than 10 sales, it's. It's tough to read too much into these. But here you've got a price per buildable of 464. This is an interesting slide. This actually shows in Manhattan the land sales, how much total buildable square footage that these sales produce. So, you know, going back to 2007, you know, peak, peak market, you know, almost 10 million square feet of development sold now, you know, next peak 2015, 9 million square feet. I mean since 2019, certainly since COVID I mean there was a little bit of a bump, but you know, 3 million square feet now less than 2 million square feet that these sites are representing. Again, this is a far cry and obviously this is just, you know, Manhattan. But you, you talk about kind of the type of demand that was out there before and a lot of these big a Lot of the square footage, a lot of this was geared towards multifamily development, rental development. Now without the 421A as we've been saying for a while now that it's really been the barbell where in Manhattan, it's for condo development in the boroughs, fully affordable. So the kind of trades that we're seeing are all, you know, the one on the far left and right, these are both condo developments. The one in the middle believe will ultimately be condo. But that, that was a distressed sale that was kind of worked through. Brandon, I don't know if you want to say anything more about the first two. I have some more insight on 1128 Madison if you want.
Oh sure, yeah. I mean 252. 258 Third Avenue that was, you know, same same purchaser as Madison Avenue. So venture Segura Legion. North of a thousand available. High end condos, you know, projecting sellouts. North of 4,000 a foot that was sold by a private owner who's exchanging into triple net properties. 616 11th Avenue. So that was also, you saw 175 Spring. So this is an old Bob Gan site. Metro Lumber taken back by Extel and Princeton Holdings. So they sold the site actually to a developer out of Brooklyn for like 222 available, I want to say. So you have to imagine a rental project over there, you know, maybe betting on abatement coming back or just feels good about the fair market rents at that basis.
Yeah, now.
Now, yeah, we just give the metrics on that at the Kushner stuff. So the Kushner six and a half cap going in 11 rent stabilized, slash rent controlled. It was 966 a foot. But the biggest thing is the buyer assumed the seller's 3.77 interest only loan through 2029. So that was the big driver there. There was also, we talked about what was Riverside Drive. Yeah, yeah, so Riverside Drive. So this one I have here, it's. I just, that was just in front of me. Sorry about that. Oh, Here we go. So 281 a foot, 63% rent stabilized, slash rent controlled. I would say of note. You know, again, just there was a massive reduction in value over the years since it was purchased. And then. Yeah, that's about it.
All right. And I, I know Scott's got a lot to say, so I'm going to breeze through retail which averages 7 cap the price per foot coming down to low thousands of foot. But as we see this really, you know, is, is pretty volatile in the sense that a couple large sales can really skew the market. Being said, we did elect to take out the one, the largest sale which accounted for almost half Manhattan's dollar volume. 715719 Fifth Ave. Purchased by Gucci, not to be outdone by Prada. So Prada pays $800 million last quarter. So Gucci 9 $963 million. And the parent company Caring I believe also just acquired a property in Milan for over a billion dollars. So luxury retail definitely seems to be on a spending spree here. We have a retail condo at 401 East 60th Street. Brandon, I don't know if you hopped off, but I think you had the. This was Gazit holdings with the trade there and then the Last one at 110 West 32nd Street. This was a distressed sale that was purchased. The entire building was purchased for 35 million and the buyer of that just spun off the retail for 30 million alone. So is into upstairs the office for I think it was actually six, seven million dollars going to convert that office to resi. So that, that seems like a pretty smart deal by that buyer. That was Tony park who executed on that. So Brandon, any More thoughts on 401E 60th street on that, that trade before we we move on? You're on mute right now.
Yeah, so that was a 5.5.9 cap. It was occupied by Home Depot and Starbucks. I mean great space. It was previously occupied by Bed Bath and Beyond. You know it was, it's fully occupied. Just strong retail. Great.
Okay Office. And I've already told our, our research team I, I want this four and a half cap rate to, to basically disappear from the chart because there's so few cap rates that we're reporting now. Most of the office that's trading is either you know, mostly vacant, significant vacancy. You don't see a lot of core office fully occupied long term. Walt. So what happens is one or two of these sales will kind of keep this four and a half cap average alive. But I think this is going to be something that we're going to put in the history books here in a while. We also promise you for next quarter that we're going to actually bifurcate the price per foot on trophy A B and C office because 659 a foot. Sure we can sit here and say that it's, it's kind of held since the previous quarter. But what you see is huge variances in the price per foot. Again this trend of end users buying office, I mean that was definitely the story for last year. Still continuing. A tenant in 211 Center street buys the property for $51 million. Actually all three of these trades. How telling is this? These are all end users. So Brandon, I know you reported on these as well, but you want to give us the, the user groups that were acquiring these properties?
Sure. So Center Street, I mean that was just over. That was just over close to 1100 a foot. So that was the Museum of Chinese in America. They were in the, they were tenants in the building and they purchased it. 545 Broadway. That was the Brandy Melville purchase. That was 11. Just over 1100 a foot. 25 East East 22nd Street. Well done by our old colleagues over at CW. So that was purchased by a Japanese publishing and comic book company. It's going to occupy the building. They paid 1571 a foot. So that was a big boy.
Wow.
Yeah.
Perfect. Okay. Yeah. But all, all three office purchases are users. So obviously no cap rates assigned to any of these transactions. You can look at this historical pricing which continues to looks like kind of adjust downward. Although nothing with the exception of retail as we mentioned before is uh, you know, as volatile. So looking at cap rates you're seeing some serious expansion and certainly for retail now looking at some cap rates north of 7%. Pretty remarkable. But you know, Scott will tell us where the borrowing costs are and how that that correlates multifamily now to five and a half percent. And you know, as we start breaking up the fair market and fully rent regulated multi trades. Sure you'll see a huge discrepancy there as well. Not too similar with the different types of office buildings that will report on. So you know, the question is, I mean end users have really been the saving grace for a lot of these office purchases. How deep is that? Well what happens in some of these larger assets trade where maybe they're, maybe they have long term leases or you know even some Walt that would make it difficult for an off user to take over. Obviously we're watching very closely with what's happening with good cause eviction 421A. We will certainly let you all know as we get some feedback. And then you know, these loans coming due, are these going to continue to force a lot of these sales that are taking place? So we did Brooklyn. So with that, Scott, you're up. We managed to cover everything in 30 minutes. I know Brandon was scrambling a little bit for his notes, but that's okay. Okay. We're still, you know, maybe we're at 1232. So we apologize for a two minute delay.
No worries, I will roll quick, quickly as well. So I think James, you can go right into the next, right into the next. And these first couple slides, for anyone who's been following these the last few quarters there, I'm putting the same ones up just to say we've been in this dislocated period since 2022 when you know, 5% sounded high and then 6 and then there was 7. And when we put this slide together towards the end of last week it was more six and now, you know, suddenly treasuries are up 40 basis points in last month. So we remain volatile. I think, James, if we go to the next, this is a slide where we look at where the 10 year treasury has been since this one, since 1962. And I think the question has always been what's coming next and where are we? And within this slide the average, and we showed this on some prior ones, has been about four and three quarters for the 10 year treasury over the last 60 years. And so we had this period of time in the 70s and 80s when they were much higher and we had this period of time which was more limited in the last 10 years or so when they were much lower. But we still remain below the historical long term averages. And for anyone or everyone who saw Jamie Dimon's note last week, this is really what he was pointing to as well. The fact that we got used to very low rates doesn't mean that they necessarily will return. James, if you go to the next one, this is our comparison we've shown before between treasury and sofr and what I always pointed to here is that the, so the purple line that's more moderated is the treasury and the blue line with the quick ups, short peaks and often quick downs was Libor and now it's sofr. And within this, the question on everyone's mind, when will the Fed start cutting the short term rates? I think there are real pressures, competing pressures on them now and the talk of higher for longer and whether there will be any cuts this year and when they will start, I in my mind makes a lot of sense. My own feeling is that cuts are not coming soon and are not coming fast unless outside forces require it. James, if you go to the next getting into the forward curve, which we did show the last time, so the forward curve is, is created by traders who, you know, make their living by betting on SOFR and Treasury rates and the interactions between them. And I think this is a really Interesting slide again to look out here. The SOFR is this blue, navy blue line that starts out high at the top left in the five and a half, five and a quarter range and does drop. And so that's the projection of the cuts that the market believes that the Fed will take. But if you look at it, it takes about a year and a half. It's hard to see at the bottom but, but that spot where the SOFR line hits the three and a half is 20, 26. So two things on that. One, that's a couple years out and two, that's only three and a half as opposed to, you know, the zero percent that we all got used to before. And then it's, there's no more decrease that the people who bet on this every day are expecting. Similarly with Treasuries, the blue line is the 10 year, that's a little bit, they're basically equal now. And in fact over the weekend we could bump both of those up to the 450, 460 range. So the expectation before the weekend, even without that raise was that there was very little decrease coming in Treasuries and that we were staying here at a level that's 300 basis points, 250 basis points above those all time lows. And we seem to be moderating back towards the long term historical average. All right, James, if you go to the next. So you know what's happening now, what we've seen and especially in the last three to four weeks is a massive uptick in activity among borrowers for refinancings, among developers who want to get started projects that have been sitting and being talked about. Suddenly there just seems to be far more activity. And I think it is, I think it's FOMO to a certain extent. Maybe that's, you know, a catchy way of saying it, but, but more a belief not only among interest rate traders, but among real estate participants that rates are probably not going to drop dramatically. And they, and the worry that existed and created the lack of transactions from the late 22 into, you know, farther into 2023, the concern of how high rates would go, we may have moved off of that as well. And so we've seen that, that, that there's capital available for any transactions that make sense. All across the risk profile, we're getting some very low spread deals done on, on low leverage assets. We are seeing a lot of interest from higher risk, higher return money. Just really overwhelmed with, with a supply of that money that wants to get put out. But hasn't seen enough deals yet. And it does seem that we're moving towards the middle with that so that deals can get done. Cmbs. I think probably for the rest of this next couple minutes I'm going to talk about cmbs in that we've seen CMBS come back very strongly, especially in the last few weeks and even for office. And so we just pulled over the weekend. This is seven trades, mostly CMBS on office buildings. And there's a variety of, you know, some are lower leverage and some were not. But I think the fact that had we been talking about this, we were talking about this, you know, a couple months ago, the likelihood of doing a, an office loan in a CMBS pool was very, very low. Now if you go to the next one, James, I took just a look back. So you know, CMBS was created for a market like we've had over the last 18 months. In the early 90s there was a vacuum in capital available, there was a banking crisis, there was a liquid. I've probably said this before here but my first day working in 1994, the group of brokers who had, who were in the business already had had the assignment over the weekend to look to make a list of all the lenders who were in the market for anything in New York. And it's a really short list, it's about 12 players. So there was no liquidity then. And the CMBS market was a creative way that Wall street came up with to bring supply of capital back into the market. And I think we're seeing the same thing. We've seen the same thing happen that as things really slow last year CMBS got creative. A five year treasury five year fixed rate CMBS market emerged. The SASB market is back and that group on Wall street is really, really smart at figuring out how to bring capital into the market. And the great thing about CMBS for this market is that the supply is essentially unlimited when the demand is there and the demand is there. So I think my last slide is just the next one showing historical C CBS volumes may be a little hard to see. The right side is full years going back to 2024 and digging in the average sort of normal year of CMBS volume has been in the 80 to $100 billion range. And there was only 40 billion, less than 40 billion last year. Virtually all of it was in the fourth quarter. There's 17, $18 billion already in the first quarter. And I have to imagine given the volumes that we're seeing and what we're hearing that the second to be dramatically higher. So you know, in summary I think we're in a period of relative stasis in index yields without any real big drops likely except as a result of outside forces. There's no obvious organic reason for borrowing rates to drop dramatically or necessarily to rise. So this may be self serving but I think it's a time for borrowers and developers to act when there are deals that make sense to do. Now's the time. That's as much as my voice can take.
Thank you. That was even tighter than what we put forth. So that was really great. And it's interesting to me the parallels between the investment sale market and the CMBS market because when you start looking at those historical averages, I mean I was looking back to what was it, 2015 when there was over $220 billion of CMBS. So you look at last year, you say well that was only one fifth of peak and we could do the same thing for the sales market. But you look and historically about what kind of appetite has been out there and again if we could even get back to kind of a more 10 year normalized rate, there's a lot of appetite out there. So I thought that that was great. We did get several questions about yes we the deck for those who sign up for this. So Savannah, who's been fantastic, who does our marketing will make sure and Julia will make sure that you all get copies of this. And then John, you asked the question about have we seen any resi conversions of office buildings? Not in this past quarter. Again those three significant office trades were all acquired by end users. I just got back from the ULI conference. Well I didn't get back was here in New York but sitting in on the ULI meetings and talking about resi conversions and I saw GFP's presentation on 25 water, saw Van Barton's presentation on 180. A lot of these were already in the pipeline. We know that there's some other, you know, large resi conversions plan but again what they all have in common is that most of these buildings were purchased at sub $300 a foot. All of those office trades that we just shared with you, 1000 a foot, 1100 a foot. You know again when you have users willing to step up at that basis, it's not going to make sense to convert it to resi unless if we're talking about a super premium location where you can sell condos. I think there was also a question about have we seen any commercial development. Once again the answer Is no there. I certainly, I haven't seen any spec office taking place recently. If you were referring more to hotel development, I saw the stat that since the city put in place a special permit to build hotels, which I think most would say is kind of a requirement to build a union product, that there's only been one new hotel built. That could certainly be a whole other webinar on the state of the hotel market and opportunities there. What I would tell you quickly is that the number of keys in New York have been substantially reduced not just from resi conversions, but from migrant housing, which I've heard estimated at between 15 to 20,000 keys, which brings the New York City hotel stock from about 100,000 keys down to call it 80, 85,000 keys available. So as a result you see ADRs going up as well as occupancy rates. So again, if you have more questions, put it in the Q and A. Scott I actually want to bring something that your father told our group which is, you know, yes, the 10 year treasury is up, but you know, maybe some good news, at least for multifamily is that the spreads are tightening. So maybe talk a little bit about why we're seeing that in the multifamily space.
Yeah, I think it's competition. I think that the lack of deals and the lack of has caused there's a need to get money out. I think where he's been seeing that is on some deals that are quite attractive. And we're seeing spreads pushing down to again, what's been historical norms. I think the lowest spread I ever did in my career was 12 and a half basis points over swaps at a time when swaps were about 50. So that was 62 basis points over Treasuries. That was a total outlier. But a normal, you know, normal range of lowest spreads has generally been in the 125 to 175 range in a normal market. And there are no 125 spreads out there, but there are, there's 150 and there's below for the, for the best deals. And so that is again, I don't see a lot of downward movement in spreads for lower leverage deals. And CMBS pricing is, you know, CMBS I think is winning deals by being the source of liquidity now, but it's not at exorbitant rates. So if CMBS deals are getting done in the low, you know, for the more challenging deals or for the office deals in the 2002 and, and certainly in the, for for multifamily, well south of that. Then, then again, that's a time when, when it's from an, from a historical average perspective, it has become a reasonably attractive time to borrow again. Now if you're selling, if you can sell deals, if you can be selling deals at three quarter cap rates, then this is a problem. But I think that we've seen that change, that the market adjusted and cap rates adjusted to the higher rates as well. And 3% cap rates were not a historical norm either. So I think we've come much closer. If anything, I think the cap rates now still are well below long term historical norms.
Great. And that's a good segue for Brandon. And this is coming in from an anonymous attendee. Brandon, this might be Joey Kosum asking this question. He wants to know what is the difference in cap rates and price per square foot for fully rent regulated and majority fair market. And I would just caveat that by saying we don't see fully regulated buildings in Manhattan. I mean that would be pretty rare. I think, you know, if we want to talk about in, in the boroughs, we certainly see some of that. But Brandon, if you want to come off mute and tell us, you know, what you would say to cap rates and price per foots on regulation and, and price per foot.
Sure.
I think the first thing I would say is that we spend a lot of time, we have our own internal reports for that, you know, track every single sale in the city, percent rent regulated, cap rates, information about those sales that we share with clients. So if you are one, feel free to reach out. We can go through it. Generally speaking, for price per foot for the multi family product that has, call it 70, like 65 to 100% rent stabilized, you're generally seeing, you know, again, it depends on the situation, but you're generally seeing price per foot somewhere between 250 to 350 is where I've generally seen those trades. Once you're looking at majority fair market, I think something else to consider is what tax class is it? Right. Because as the, if you're looking at a tax class 2A, 2B property, the taxes are very low. The price per foot organically gets pushed higher, you know, but you're seeing these value add properties trade anywhere between, called 500 to 700 a foot is kind of generally the sweet spot for majority fair market value add. And then I mean, ourselves included, I mean we're going to close on a majority fair market 24 to 25 elevator building renovated in Manhattan. I mean candidly and we've done a number of these not it's hard but you know, that'll be a, on real numbers, a sub 5 cap. It's a 5 cap on our numbers, you know, approaching 1200 a foot for a tax class 2 building. So you know, it's just, it's so dependent. It's a very, I've said it a million times, it's a black and white market. So for the value add stuff it's challenging because there's not many people out there with equity. So it's a pretty small buyer pool. There's a lot of people that want to buy, but can they actually raise the equity? It's, it's been challenging. And then on the renovated stuff, it's, it's a lot of buyers from overseas. Almost entirely, very few, 1031 buyers, but there's some and they're willing to Pay, you know, a 5 cap. It's just that there's, you know, I always used to say there's. For every one renovated buyer there's 15 to 20 value add buyers. So take that and then shrink the buyer pool more. It's just a needle in a haystack. That was already a needle in a haystack. So it's just a lot of work. But if you find them, you can still be successful.
Yeah. And I know that the Japanese buyers who've been incredibly active as of late really want to see that majority fair market building. But since we have Joe here and Joe, I'll put, I'll put you on the spot here. Fully regulated deal. I know we were looking at one in Queens and kind of the buyer appetite, I mean if you want to say the bid ask spread that a lot of what the buyers were looking for to buy a fully regulated building. What kind of cap rates were they generally looking at? Or is it price per unit?
Yeah, I think the biggest thing, the biggest driver with these fully rent stabilized deals is your, is your top line which is your gross rent multiple. So you know the one in the story that we had just sold, 2519 30th Drive, this was a low rise building, very little capex that sold for eight and a half grm. Whereas you know, if you find, you know, if there's a lot of day one capex that has to go into it, that number can go as low as below 6 where you see sometimes in upper Manhattan in the Bronx. That being said, you know, a lot of these rent stabilized buildings with little capex are trading at, you know, neutral leverage. You know, the One we sold, you know, if not negative leverage. The one we sold I just mentioned in the story was a six cap and the buyer told us, you know, he got debt at six and a half percent. So he's you know, long term view, they're not looking to, you know, buy and flip and wait for cap rate compression in a few years. It's really, you know, holding for 20, 30 years. Like their, their parents may have bought a building, you know, in the 90s wherever else. They're seeing those opportunities today at low basis.
Great, thank you Joe. You, you nailed it. And I will say that the types of buyers for these fully regulated buildings of course are taking a longer term view and you know, hoping that the pendulum swings back. And obviously not a whole lot of great news coming out from Albany. But Brandon, as you mentioned before, if there's an increase on what the AIA's did, I just reverse that. IAI's AI. That's the architecture thing. Yes. The reimbursement for improvements, they're talking about in increasing that. So Scott, did you want to have some closing words? I have one last thought before we close, but if you had something else, feel free to chime in. Not really.
I think I did it. James, go ahead, bring us out.
So the closing thoughts and the one thing that we did not talk about was the Blackstone acquisition of Air Communities. And although that wasn't, you know, an individual asset that we would, you know, talk about in this format, but certainly a huge vote of confidence for those of you who read the Journal article and you know, the way that Blackstone was viewing this, the Air portfolio and some of you might recognize the name aimco more at a point there was a split between the aimco assets and Air. Air being the higher quality, you know, newer construction assets, fair market, and those were mostly in gateway cities. So there was a lot of chatter last week at ULI about how positive of a sign this is for the gateway markets for multifamily that Blackstone getting off the sidelines, if I'm not mistaken, was it a $10 billion acquisition looking at what that cap rate would translate to based on the takedown price, the premium on that stock price. I've heard reported between a 5 and a 6 cap, but somewhere in that range. But again a huge vote of confidence for multifamily in the gateway markets because we know over the last couple years a lot of the institution appetite has been focused in the the smile states. So with that I think we made it a little bit early. What we'll give you all seven minutes to go onto your next meeting or next thing. And as always, we really appreciate the opportunity you're joining us. We had a great turnout for this. We'll have this deck for you. And as Brandon and Scott said, if there's any individual questions or things that you need our help with, we're here to be of service to you. So have a great day, everyone, and look forward to being in touch.
Bye, everybody.









