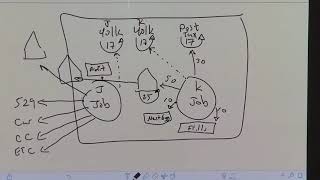
Jeff, a physician, outlines his family's five-year plan to retire by aggressively buying rental properties. Starting from 15% of their retirement target in 2014, they now own 18 rental homes generating 25% of needed income. His strategy: pay off one mortgage every 8-10 months while buying new rentals, allocating his wife's income 50% to new properties, projecting 120% of required income by year five.
Chapters
Hello, my name is Jeff and this is our five year plan for retirement. We're actually the Joneses next door. Let me introduce you to them. Here we are on the left is my son Harrison, then Nathan, then my beautiful wife Christy. Myself and Grace. We are the Joneses next door and we're planning for retirement because we've spent a lot of money over the years. We have to get a plan going. Let me tell you first about my experience with money. I was raised by a father who was a schoolteacher and a landlord. He invested in small houses and in commercial real estate, the 70s and 80s. And even though he was a school teacher and had all sorts of time off to raise us, he was able to pay for my medical school because he didn't spend anything. He was really the millionaire next door and he was my dad. But the other influence I had was my wife. She's beautiful, but she likes the good life. We send our kids to private school, we have a big house, we have a fancy car, and we enjoy finer things. I'm a little bit conflicted because of my upbringing, but when it comes to my wife or my dad having the most influence in my life regarding money, I must admit I've sided with my wife. So we have a lot of expenses and a few years ago we started getting serious about looking at the bottom line and how are we going to ever retire. We've always put money away in 529 plans and we even paid off our primary residence. Additionally, we've had money going to 401s, we've maxed out our 401s and we've invested in our post tax account. Even after 15 years of working as doctors, we aren't even close to meeting our goal retirement number. In fact, if we were to retire right now and just went through our post tax account, we would only have 15% of that number. Actually, that was in 2014. Now it's up slightly, but we needed another plan to get to retirement early instead of just Keep working another 15 years hence, we had a plan to buy rental homes just like my dad did, and to use the cash flow to help fund retirement. I started listening to Jason Hartman's podcast and after doing so and pulling some money out of savings and refinancing our cabin, my wife wouldn't let us touch our home. But refinancing our cabin, we were able to start making income from rental income. In fact, after two and a half years, we now have 25% of that goal number for retirement coming out each monthly by cash flow, because we bought 18 rental homes and I purchased an office where I practice. Our post tax account, it's gone up a few percentage points and the 401k has gone up a few percentage points. Those percentages, the 17s up top, are basically what we could expect to make from those accounts if There was a 4% yield each month. So now we're at the point where it's 2017 and we are thinking about what we're going to do the next five years to get to retirement or at least an option of retirement. Right now we have 42% of that money available. 25% is coming from rental homes and the post tax account is yielding 17%. So that produces money that's available of 42%. So that's up from 15%, which isn't bad, but we're not yet close. Our future money, if we wait until we're 59 and a half and start taking 4% yields from our investment accounts would be closer to 76%, which doesn't sound bad, but we're not 59 and a half yet. So our next plan is this. And that is to pay off one mortgage every eight to 10 months and buy a new home on mortgage every eight to 10 months. Will pay extra mortgage to our cabin to have that paid off in five to seven years. We'll stop funding 529s in five years and Christie will be given the option to retire in five years and maybe me as well. And this is how we are going to institute that plan. Basically from my job on the left, I will fund all of our expenses from my job. I've actually made a profit account in my business. And from that we're going to pay extra towards the cabin, our second home, so that in five to seven years the cabin will pay it off. And then Christie's income we're going to use for investments. And I've broken down the percentage of her income every two weeks we'll take 50% of that money and put it towards rentals. 30% of the money will still be going into investments in the stock market. 10% will go to our nest egg and 10% will go to go to a frills account. We have extra savings other places. Our nest egg is. This is a nest egg that we use just for emergencies on a month to month basis. By doing that over the next five years, this is what we hope to achieve. And that is the following. 50% of our goal income will be coming from rentals and 26% will be coming from the post tax account producing now money of 76% which isn't bad and probably will be able to cover our expenses. I may still need to work part time but I won't have to work full time at that point. If we look at future money however though and include our 401k plans, we'll be able at 59.5 have 120% of our income. Additionally, shortly after five years our mortgage on our second home will be gone and our 529 plans should be fully funded to cover college for three kids and at least one if not one and a half graduate school educations. The car lease will probably be gone and our credit cards may be higher for travel and or etc. But I think we'll have enough money by that time. It's exciting for us and if we go back and think about five years on where we were in 2014 with only 15% of our money coming from our post tax account, it's hard to imagine after 15 years of working that we'd only have that amount needed for our goal retirement. But I think this shows that rental investing has been so far good to us and it is a good option for us to supplement our retirement money and it gets us to our goal much faster than if we were to continue investing in the stock market alone. I want to thank Jason Hartman for all his insights and helping us. Even though we've had some bumps in the road in Chicago, we're going to weather the storm come out ahead and I also want to thank everybody else who's helped us get to this point. Hopefully in five years we'll be at our goal. We'll see. Thanks a lot for watching. Bye Bye.