Strategies to Minimize Duty Liability in the U.S. Heightened Tariffs Environment
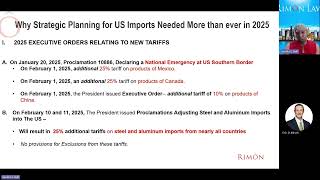
In this presentation, Sandra Bell – a former U.S. Customs and Border Protection attorney and current customs‑law partner – explains why U.S. importers must urgently reassess their supply‑chain and customs strategies amid a rapid series of new tariffs. She outlines the recent executive actions (Proclamation 10886, Section 232 steel/aluminum adjustments, Section 301 China tariffs, anti‑dumping and countervailing duties, and Section 201 solar duties) and then walks through five practical mitigation tactics: (1) tariff‑classification review and tariff‑engineering; (2) alternative import‑entry methods such as temporary import bonds, bonded warehouses, and foreign‑trade zones; (3) import‑valuation and first‑sale transaction‑value planning; (4) country‑of‑origin restructuring via substantial transformation; and (5) drawback refunds. Throughout, she illustrates each approach with a hypothetical global supplier, “Company A,” showing how a multinational can shift production, redesign components, or restructure contracts to avoid the 10‑25 % extra duties now imposed on goods from China, Mexico, Canada, and other countries. The talk concludes with a call for companies to revisit traditional customs tools, document contracts early, and consider follow‑up questions.
Chapters
Good morning. I'm Sandra Bell, partner at Ramone PC. I'm working out of the Washington, D.C. office. I spent most of my career at U.S. Customs and Border Protection, having joined there since law school. And in the last 8 years, I've been in private practice. I practice in all areas of customs and administrative law, the details of tariff classification, country of origin, customs penalties, border enforcement. And I've seen both sides of the, of the game in terms of the government perspective as well as the private sector's perspective. So I think I've been able to combine those two experiences to serve my clients in a variety of areas, mostly international trade companies, mostly international global supply companies. And so I've seen the benefits of being able to have a free trade environment as, as well as to support the various issues of the respective domestic countries in which these companies are located. Thank you for having me. The topic that I'm covering is strategies to minimize duty liability in the U.S. heightened tariff environment. You may wonder, you know, why is that needed today? Well, In today's environment, international trade between countries is common. We've had the proliferation of negotiations of free trade agreements which have been encouraged over the years, and so for many global companies, you know, importing into the US and elsewhere, it's really no easy way to stop sourcing products from other countries. So in this particular circumstance, as well as the environment where we're having more tariffs being issued by the United States, one of the largest markets in the world, we have to look at developing strategies to minimize duty liability in this environment. So let's take a look at a technical company called Company A. Its global supply and trade structure, which is pretty common when you're talking about a global company. They have affiliates in Asia, North America, as well as Europe, major— the large markets. This company develops and sells products and services worldwide, you know, to customers who build other products from the products they're selling, as well as customers who are just consuming them. Company A's affiliate companies sell their own products in those markets, and that is in the Americas and Europe as well as Asia. You'll see that Company A sources primarily through unrelated contract manufacturers. These are companies that are design manufacturers called ODMs and CMs. These are companies that are only sourced to develop the product from materials that are supplied by Company A and Company A's affiliates, as well as companies that are only retained to develop certain designs, you know, which they would own the trademark and whatever intellectual property rights, because in those circumstances, those are, you know, work for hire, but they're separate from the affiliate companies, but they're unrelated and they're unrelated to Company A. That these processes happen in, in 3 large regions of the world. The US, China, Southeast Asia, Mexico, Germany, and other parts of Europe. So just taking Company A, for example, it has extremely difficult challenges in the wake of the, the very recent U.S. executive orders. So let's take a look at some of these executive orders, because as a result of just a month of having so many changes in the United States trade landscape, it's all the more reason why any company that's importing goods into the United States must develop strategic planning for those imports and exports in the United States before they get started, if that's at all possible. On January 20th, the president issued Proclamation 10886, which is a declaration of national emergency at the U.S. southern border. That declaration of national emergency at the U.S. southern border, however, established the foundation for three successive executive orders, um, resulting in the additional— the imposition of additional tariffs in the amount of 25% on all products from Mexico, Canada, and then 10%, an additional tariff on products from China. The reason for the tariffs on Canada was because it was perceived that Canada was not doing enough to stop the flow of illicit drugs across the border from the northern part of the United States. And of course, with Mexico, the reason was that Mexico was not taking enough actions to stop the flow of drugs as well as undocumented immigrants over the border from the south. The reason for the 10% tariffs on products coming from China— and these are not products just coming from, but they have to be products of— that's the They have to be sourced as being the origin of those countries because it was, it was determined that China was the source of the synthetic opioid supply chain that would come in through these other countries. China's duties were only assessed at 10% because, as you may know, there are several assessments of duties already on products of China. You have some, some products coming in with a 25% added tariffs, some products coming in with 10%, some products coming with 7.5%. It's not across the board, but this, this 10% would apply to all products of China across the board in addition to the product, the tariffs that they're already experiencing. Then about a week later, on February 10th and 11th, even though they're both dated, I think February 10th, the president issued proclamations adjusting the steel tariffs and steel and aluminum tariffs on products coming to the United States. These are called Section 232 tariffs. They were in existence since 2018, but many countries through separately negotiated agreements had those tariffs abated, either removed completely or substantially reduced. This, these proclamations pretty much voided all of those agreements, and those agreements with the EU, the UK, Brazil, Japan. Korea and some other countries that, you know, might not, might not have been identified. But these tariffs now will apply across the board, and most significant, this, the process now is not going to allow for any particular request for an exclusion. That was one of the biggest, what some folks would consider a loophole under the last assessment of these tariffs and back in 2018. Because not only did you have these separately negotiated agreements, you had domestic companies who were able to appeal to the Department of Commerce, the US Department of Commerce, for an exemption of their particular products on the basis that the US just doesn't source these products or doesn't have enough steel or aluminum. Because when it says steel and aluminum, it's not just the raw materials. It would be articles of steel and articles of aluminum. For instance, pots and pans. They would be covered by these extra tariffs. So, and then many companies in the manufacturing business, that's what you're probably hearing about some of the complaints from the car industry here in the United States now, because they probably did have an exemption for the steel that they would be needing and aluminum they'd be needing to produce, to manufacture cars in the United States. But that exemption is no longer going to be possible. And the US just doesn't produce enough steel and aluminum currently to keep those manufacturing facilities going. So that's another hit that people will be experiencing. But on top of the, the new tariffs that came out just in the month of February, we already had escalating what's called trade remedies tariffs already in place as a result of the anti-dumping and countervailing duty laws. The anti-dumping duties would be imposed when the Department of Commerce would conduct an investigation with respect to particular products coming from particular countries and would find that those products are being sold in the United States at less than their fair value. That finding alone would not be the basis for assessing those duties. The International Trade Commission would then then have to take that finding into consideration and find and determine as a result of their separate investigation whether a US domestic concern, the US domestic industry as a whole, is being materially injured as a result of those imports into the United States. We also had— we always see— I would say you would normally have parallel to an antidumping duty investigation, a countervailing duty investigation, and this is an investigation as to whether or not the government of some of those companies is unfairly providing subsidies for the goods being exported. And then the ITC would again have to make a finding that those subsidies would cause material injury to a domestic consumer. And this sounds like a very difficult process, but we have thousands of anti-dumping duties and countervailing duty orders in place, and many of those orders already cover the countries that would be subject to these additional duties. We have orders involving goods from Mexico. We have orders involving goods from Germany, orders involving goods from Japan, almost everywhere you can think of. But most of them, as you might expect, cover goods coming from China. And recently, 2018, again, we had the for the first time in a long time, the use of the Trade Act of 1974, Section 301, to conduct an investigation and define whether or not as a result of that investigation, you know, products were being sold at sort of an unreasonable, unjustifiable basis that caused a burden on the US commerce. This is something that would be conducted separately by the US Trade Representative at the time. And those are the tariffs that we call the Section 301 tariffs that were mostly assessed on products of China because this investigation involved China's actions with respect to intellectual property rights. Of course, the products that were chosen, you know, were not necessarily the products that were involved with intellectual property rights. So the products chosen, I guess, to impose the most economic impact on China at the time. But of course, this is a statute that has also been used for products coming from Europe. These— there may still be some duties being assessed on alcohol, wine beverages coming from Italy and Spain using this tariff, but under a separate investigation. But most of those products covered by the Section 301 duties still in place, initiated by President Trump during his first term. And maintained by President Biden are still in place. And so for the most part, for goods coming from China, you have the duties that were already being assessed under Section 301 being capped off with the new 10%. And in some cases, some of the very same products may be subject to antidumping and countervailing duty duties. So companies for the antidumping countervailing duties, most companies would be involved and would be aware of that because either they might have been involved investigation in terms of responding to it. But if not, they would get some notice about that coming out just through, you know, notices from Customs and Border Protection generally. So either they were— they were— would have already made plans to incorporate that additional cost into their operating budget or avoid sourcing products from those countries. But then, you know, here we now are bounding with some— we're now dealing with tariffs that would apply to all products from certain countries, regardless of whether or not there was a dumping investigation. By the way, so I did not put it up on the slide, but there's also another section involving tariffs. It's called Section 201 of the Trade Act of 1974, which results in a lot of tariffs being assessed on solar products. You know, from anywhere in the world coming into the United States. They're still in effect. And, you know, there are lots of exceptions to them. But if you're bringing any kind of solar panel products or inputs, anything that's made from the crystalline poly— I think it's crystalline poly photovoltaic cells, silicon. Those are products that would be likely subject to tariff rates, which would be an extra tariff on top of the regular tariff for those products. And under the circumstances, most of those products aren't free in the first place. So against that backdrop, I wanted to just, I guess, let you know that this is not new in terms of— it's just new in terms of how fast this has been happening. You know, prior to 19— I would say 1992 when NAFTA was negotiated, you know, there were tariffs on pretty much everything coming to the United States. Instance. And of course, you didn't have all the other free trade agreements that followed NAFTA. So companies were using the traditional tools available to minimize their duty liability. My recommendation is to companies to go back to those tools because of the fact that they never change. They just never— they just haven't recently been needed to be used because tariffs have been lowered so much, in many cases to a zero rate, you know, as a result of the World Trade Organization, uh, GATT agreements with various countries, with the free trade agreements with certain countries. And so companies just really haven't needed to focus on tariff rates. They're more focused on duty rates. I had a situation involving that global supply chain we talked about earlier where the client said, well, you know, We were concerned about duties, you know, we— and I said, well, you can deduct the duties from your taxes, you know. He said, well, there's nothing to deduct. We've got this tax cut. It's cut to the bottom. So the duties being assessed, you know, under the Section 301 provision would just have to be an extra cost without any tax benefits whatsoever. Anyway, back to strategies. One of the first strategies is the tariff classification strategy. Every product coming into the United States and anywhere in the world has to be classified under the Harmonized Tariff Schedule, which is— and I say harmonized because, as many of you know, that's the same provision applies to all countries that are members of the World Customs Organization using the Harmonized Tariff Schedule up to the 6-digit level of the tariff classification. After the 6-digit level, when you're going to the 8 and 9 and 10-digit, the product classification will not be the same. Those are the domestic extensions, and those are the extensions that actually provide the duty rates for the particular product. But in terms of where it should fall, fall fall within the tariff schedule, the country should be uniform. So, you know, I think one of the first things you want to do is review all the products that may be subject to these new tariffs. And one of the things that you keep in mind, all the tariffs that are being assessed and the executive orders that we discussed earlier, they're tied to an import's particular tariff classification. It's not a generic tariff. So when somebody's bringing something into the country, it has to be classified under the Harmonized Tariff Schedule, that 50,000-page document which is online, and you will know it will be determined based on that particular tariff classification for that product. What is the actual extra duty that would have to be assessed on that product pursuant to one of these executive orders? Sometimes a classification can change just based upon one of the components of an article. A product that can be made with aluminum extrusions may not be needed to be made with aluminum extrusion, maybe could be made with another metal or a hard plastic. To the extent that that's something that could be done, that change could possibly take it out of a tariff classification that's now subject to the new tariff on aluminum or an existing tariff under the anti-dumping investigation. That is not illegal. That's called tariff engineering. It's legitimate to modify the design of a product for purposes of lowering the duty, your duty liability, as long as it's legitimate, as long as it's something that's transferred back to where it was right after importation. That's considered to be fraud and artifice. So those are the things that you can do in terms of looking at all of your classifications to see whether or not for those products that are now subject to these higher duty rates, whether or not for the future— you can't, you can't remanufacture the products already made— but whether or not for the future, looking at those design, having your design manufacturers, you know, that we looked at in that scale as being one of the contract manufacturers, change it in a way that would take it out of the current tariff classification for the product. When you're talking about a company, global companies that, you know, are involved in importing and exporting to various countries, you can also look at altering your import, your import strategies. For instance, if you're bringing products into the United States just for quality control, and I've seen this a lot, companies importing products from Asia into the United States for review, then they're shipping those products on to South America or Europe, Caribbean, or even Canada. but they want to make sure the products are meeting their standards. Well, I've seen companies where they were just importing them as if they're going to use them. It's called importation for consumption, as opposed to importing them in a, in a, under circumstance where they would not be paying duties. And there's several ways to do that. You can import something into your premises, the company's premises in the United States, under what's called a temporary importation bond, for a time period where you're allowed to inspect, repackage the product for whatever purpose, and then the product has to be exported. You can also import the product into a U.S. Customs bonded warehouse where you can do the same thing, but you don't have to export it. You can decide to bring some of the products into the United States after that measure. But in the meantime, no duties are paid. And of course, you can do the same thing into bringing the products into a foreign trade zone. You know, those are considered to not even be within the customs territory of the countries in which they're located. And you could do the storage and you could do the manipulation and you could actually do some further processing to the product there. But then before it's actually shipped abroad, or, you know, if you want to eventually bring it to the United States. But those are, you know, situations where if it's coming under these special tariffs, however, most of those tariffs have provisions that whatever status, whatever duty rate applies to the products when they're imported into a foreign trade zone, they maintain that duty rate when it's coming out of the foreign trade zone. So an example would be if the tariffs on, say, because you actually have some foreign trade zones making vehicles. So if the tariffs on certain products, say steel, coming into a foreign trade zone, 25% steel, then that product is being used to make a tire rim wheel in the foreign trade zone, it's going to have that high 25% rate tariff when it comes out, even though duty rate on that, that wheel will maybe only about 4.5% because these special tariffs have provisions that says that they have to actually— you're entering into the foreign trade zone, what's called foreign privileged status, which means that that status that it comes into, that duty rate that applies, will be the duty rate applied to the finished good, even if the classification is totally different from the product entered. And that's just something to keep in mind when using the Foreign Trade Zone option. But, you know, that's not the situation for the manipulation in the bonded warehouse for exportation, and that's not the situation for the changes for temporary importation bonds. Because in both of those scenarios, when you're manufacturing in a bonded warehouse or you're bringing something in under temporary importation bond for doing the same process on your— on the company's own premises in the United States, that finished product has to be exported. So that's the second strategy. First, you're talking about trying to see whether you can keep— make sure the tariff classification you're using are correct, and to the extent that you may be incorrectly classifying the products, as I've seen, in a provision that has a higher duty rate. And if possible, you know, see whether or not you can change the product through what's called tariff engineering. And then secondly, see whether you can alter your production process. I mean, the other thing I didn't mention is the fact that in a scenario where we're talking about that global supply chain, involving Company A, Company A can decide that those products that are being made, you know, by the manufacturers in China, be shipped to the customers in Europe or South America. And the products that are being made by contract manufacturers may be in Mexico or the Caribbean, and maybe even in Europe, can be shipped to the United States. That's something you can consciously do to avoid paying a higher rate. Whenever possible. And it's just one— it's just another toolkit to consider. So continuing along the 5 strategies that I would recommend that you use for minimizing your duty exposure in this current environment, the import valuation is one of the ones we'd like to take a look at. And this is one that global companies sort of in terms of for customs purposes really don't pay a lot of attention to. They pay a lot of attention to transfer pricing between related parties for tax purposes and not really because duties have been so low, they're concerned about the impact of that transfer pricing for duty purposes. Well, now if you're talking about duties being a whopping 25% at the minimum, some in some cases and maybe even higher in other cases, You need to take a closer look at that. So, you know, one of the things you may want to do to the extent that you are having your products produced by an unrelated contract manufacturer, why not turn that into a supplier contract into a sales contract where you're actually having a sale for the finished goods being negotiated with the company that's actually manufacturing the goods. And to the extent that we're talking about supplies being provided, that's something that would still be negotiated as part of the full price of the good. And if that's an unrelated company and those products are being manufactured to come to the United States, and it's called a sale for exportation to the United States, which is one of the fundamental components of having what's considered to be transaction value for customs duty purposes, the most preferred method of appraisement, that would be a lower price than the price between the actual final exporter and seller to the US importer. More importantly, if that sale between the final exporter and the US importer is a sale between related parties, there's a good chance that CBP Customs will not accept that price, you know, unless the company can— the exporter and the importer can show that that price was not affected by the relationship. And there are specified ways to provide that proof. You have to show that the product is being sold to unrelated parties, that same product in the United States with the same price, or you have to show the fact that that price represents the recovery of all costs and profit of the overall company, not the US. So most companies really don't want to give up that information if they don't have to. So we recommend looking to having the first sale, the first sale between an unrelated party and the US importer, and that price can be documented. That would be a much lower price and a lower value for purposes of duties. And those are things that— that's something you'd have to plan for well in advance and making sure you have contracts that would show that. This all comes down to the important— Sandra, we're a little bit over, so can you wrap it up in the next couple of minutes, like 2 or 3 minutes? That's it, I'm wrapping it up. Okay. So the final 2 strategies is country of origin and drawback. Country of origin is one where you're trying to change the origin of the product from a country that has the highest duty rate to a country that has either no or much lower duty rate. And how do you do that? You're going to make sure that the product that's coming from the country with the higher duty rate can be processed into a new product. Let's call it a new and different article of commerce under the substantial transformation standard. If that happens and you can do that, then you're not concerned about the first country's high tariffs. They have no impact on the final product coming to the United States and the country of origin of the last country of origin would be the country it was last produced, and that country's tariff would be the tariffs that would be applicable. The last strategy I call a backup strategy because it's not something you can use that much for these additional tariffs. They're not allowing it to be used for those tariffs under the executive orders based on a national security declaration, and it's not, it's not allowed to be used for the tariffs that are on aluminum and steel. Imports, but they can be used for the regular tariffs as well as for the Section 301 tariffs on China. And this is a, this is a process where you are able to get a refund. It's called a drawback, which is 90%— getting refund of 99% of the duties that you paid on the importation of goods. And it's upon exportation of either the same goods imported or similar goods. And the good thing about it It doesn't have to be the same goods. It can be any good that is classified in the same tariff provision of the products that were imported. And that's a simplified process now as a result of Customs recent amendments to their regulations in 2019. So I think under the circumstances, we have several strategies to look at for purposes of Company A, and I think we look at all of them, the tariff classification strategies. You look at the country of origin strategies, valuation strategies, energy, as well as I think maybe first off, if it's a company, a company like Company A, where we have a global network, alter the methods of importation to the United States. You know, make, try to see whether you can have the products made in other countries brought into the United States and the products brought in from products being made in China and the other countries that are subject to extra tariffs shipped elsewhere. But, you know, I think that's what we have to do at this point in time. And I would be happy to have follow-up questions taken from you. Since I know I'm not able to take them at this time. Thank you so much for your time and attention. Thank you, Sandra. Thank you very much.
More from Jessie
Non-Competes and Confidentiality Agreements & What to Consider When Closing a Merger or Acquisition
Coffee Talk: Navigating Leave Laws: Ensuring Compliance and Managing Employee Absences Effectively
New Year, New Laws: Significant Employment Law Developments in 2024 and What to Expect in 2025
Coffee Talk: Workplace Conflict: Why It Happens and How to Address it Effectively