Redefining Venture Capital with Kanyi Maqubela
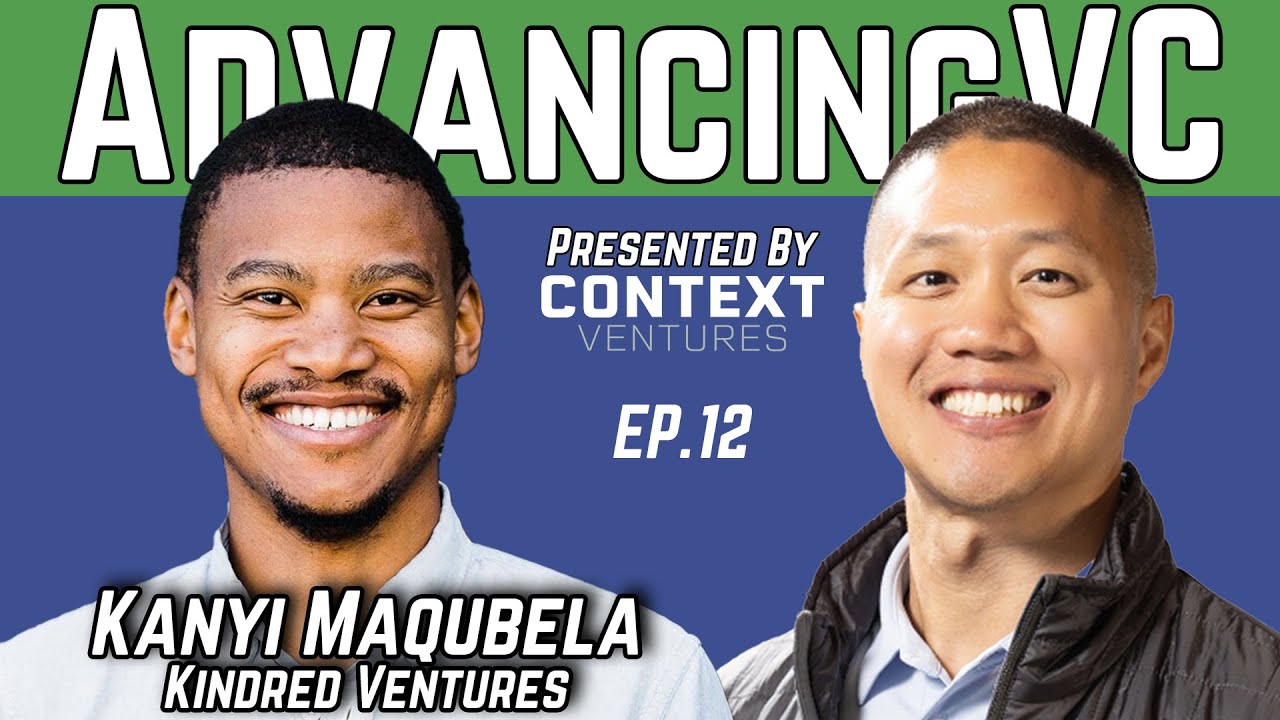
In this Context Ventures Advancing VC podcast, host Tim interviews Kanyi Maqubela, co‑founder of Kindred Ventures. Kanyi recounts his early life as a refugee from South Africa, his Stanford education, and two founder experiences – a modest exit and a $120 M lead‑gen exit in solar – that taught him the value of operational failure. He explains why modern venture capital now rewards operators who can sell money and de‑risk founders, and how his stint at The Collaborative Fund shaped his view of seed investing. Kanyi describes the founding of Kindred Ventures with Steve Jiang, their focus on being the first institutional check, flexible capital sizing (from $100 K to $8 M), and a utility‑centric thesis that looks for deep end‑user value rather than hype. He discusses the importance of deal flow as strategy, the “concentrated portfolio” model enabled by strong networks, and a nuanced view of AI valuations as price outliers versus value outliers. The conversation also covers Kindred’s board‑observer approach, cautious company‑formation practices to avoid adverse selection, and the firm’s long‑term vision to back utility‑driven companies across diverse sectors. The interview closes with Kanyi’s personal favorites in books, movies, and travel, underscoring his human‑centric perspective on venture.
Chapters
When we look at a startup, we think, how deep is the utility to the end user here? And how much of that utility are you driving? And if it's high, we'll fund you. And so as a result, we funded a number of ChatGPT wrappers in 2023 and 2024.
At Context Ventures, our podcast Advancing VC covers all things startup and venture capital. Primarily how startups and venture capital are changing from the emerging manager perspective. We chat with venture capitalists, limited partners, and founders who are actively working at the frontiers of our industry and are advancing venture capital. Today, our guest is Kanyi Maqubela of Kindred Ventures. Kanyi grew up in South Africa, co-founded a startup, and we met roughly in 2011 through a Stanford class and have stayed in touch ever since. He's a fantastic human being, And I'm looking forward to learning more about him and his journey and Kindred Ventures on this episode. Kanyi, thank you so much for being here.
Thank you. I'm so happy to be here.
Kanyi, can you talk about your inception till roughly 2011 when we met, when you got to Stanford?
Sure. Gosh, so I was born in South Africa. But when I was born, my parents, particularly my dad, but both my parents were in exile. And so I didn't live in South Africa. We pretty quickly, about 2 weeks after my birth, moved to Botswana, which was right next door. And we were in Botswana for a little bit and then ultimately ended up decamping to the United States as refugee immigrants in the '80s. And so I grew up in the United States, but I'm a South African citizen. And an American citizen as well. But that, I think, is the most important starting detail. I ended up coming out to Stanford in 2003, and I came to Stanford for the weather. This was, you know, at the dot-com bust, at the nadir of interest in startups and technology. And so the only people who went into startups even from Stanford were the people who were nerds and the people who were on the sort of margins of culture and the people that frankly were a little bit of outcasts. But I got pulled into the startup world, ended up doing a couple of startups. I actually originally dropped out of Stanford to do a startup and I did two. And so, when you met me, I had gone back and it was a wild journey where I had a 0.3x money exit, and then I had a, you know, a double-digit times money exit thereafter. So, you know, had some distance traveled as an operator in startups and was at Stanford sort of reconstituting, taking a break and trying to figure out what I was going to do next, which is where we had the good fortune of meeting. And I was just about to start my investment journey, actually, which kicked off from there and is now about 14 years in.
I feel in terms of venture capital, the path to venture capital these days is much more through the startup alleyway, whereas I feel like maybe in '90s or 2000s, it was like investment banking, consulting. And I think your journey shows that. Can you talk a little bit more about your startup experience?
Sure. Uh, maybe I'll just comment on that really quickly first and say that one of the things that's happened with venture capital is in part because of the returns being so amazing in, uh, you know, in the 2004 to 2010 era, in part because of social media and even traditional media like the Social Network movie and those types of things, taking startups to global mainstream, uh, it's become a much bigger industry. And becoming a much bigger industry, it's become a much more competitive one, a much more mainstream one. And in that world, the fundamental shift has been that the most important skill in the ecosystem has not— has shifted from can you really identify the financial characteristics of an interesting startup to, for better and worse, can you sell— can can you sell money? Can you persuade an entrepreneur to take your money instead of the 20 other people who are also trying to sell money? Because it's become so competitive. And in that realm, the thing that entrepreneurs tend to be the most attracted to is, well, can you help me? And do you understand what I'm doing and why I'm doing it? And can you, can you actually de-risk this business by virtue of showing up next to me? And so that naturally begets itself to the operator background being a better fit for venture. And now what's interesting about this is there's, you know, the typical operator modality, which is that you were an executive at a high-growth company, or you founded a company with, with a, with a pretty big exit. And those are the ones that were typically the lessons learned are, are the best to sell to founders. But I actually think the lessons learned that are the most valuable for founders are oftentimes the lessons of failure and difficulty because you want to help founders see around corners. You want to help founders avoid mistakes. And you also want to have empathy when you show up for founders. And so, a venture investor who has had operational ups and downs is actually pretty valuable to a founder and is unique in a way that I appreciate, which is perhaps a way of justifying the fact that my operational journey was okay. I was a better coach than player, I think, if I look back on my career thus far. When our first startup was right after the dot-com bust, just a couple years after, LinkedIn had just launched, Facebook had just launched, and we were trying to build something in the career space. And we ended up building a marketplace for jobs, a sort of user-generated marketplace where you could upload interesting listings, either that you had because you were the hiring manager or that you had found elsewhere on the web., and then people could apply to those directly through the site. And, you know, this is how a number of people got, you know, got interesting jobs at the likes of Goldman Sachs and Time Warner. And, you know, my friend actually got her very first venture capital job at Bessemer Venture Partners as an analyst through that website. But we just made, you know, a long series of pretty fundamental mistakes. We, you know, we were pretty focused on vanity metrics. We were trying to manufacture the hockey stick. We, you know, there was— this was a time where a lot of companies were trying to figure out how to use email and use these sort of emergence of social media to go viral with their growth. And, you know, and so, you know, there was just a whole lot of what I'd say now is, you know, just okay execution towards that end. But we were able to build something people wanted. And as a result, we were able to get to really relatively interesting scale. And when we sold the business, Unfortunately, it was not, you know, a big financial outcome, but it was a really great learning experience in both, you know, how hard it is to do a startup and some of the things you should never do, which was a good grounding for me and almost like a business school for me for startups. The second go-around was a more productive and a better journey. We built a lead gen business. This was right, you know, in the Groupon heyday. So, lead gen was having its moment. And it's one of those things where like business models will have their moments in time, right?, as you well understand. And, and so this was the lead gen moment and we built lead gen for consumer residential solar. We became the largest lead gen business of its kind in the United States. And, uh, you know, we raised venture capital and we got to millions of revenue and, you know, and we were cooking. Uh, we ultimately ended up merging with our competitor in Canada and then we sold the joint entity for $120 million, which is a pretty good outcome. So, you know, I saw a challenged financial outcome in a highly urgent market that still isn't solved, which is getting an amazing job online. And, you know, and then I saw, you know, a pretty good outcome in, you know, in a moment in time, which is really interesting in retrospect, which is the beginning of what has now been, you know, a 15-plus-year boom in the solar adoption cycle. Solar has just blown the top of what everybody expected it to be. Be in the timeframe. So, those are really, really great learnings, but the operational learnings and the challenges of hiring and figuring out what the right thing to build is and, you know, hitting the buzzsaw of I can't get this thing working were the sort of real fundamental lessons that I carry forward with me as an investor now.
What you shared about your experience makes me think even more about the path to venture and how it's a, it's much more the operator path. And I think the operator path not just because what you said of understanding how challenging it can be, but also the relationships you build. And speaking of relationships, the class that you and I met through Entrepreneurship Through the Lens of Venture Capital, the co-instructors were Ernestine Fu, David Hornick, Bill Coleman. But in that class, there are some of our classmates who are— who we have these relationships with. And I was, as you were talking, I was writing down Stephanie Zhan, of Sequoia, Janelle Tang of Bessemer, Stanley Tang, co-founder of DoorDash. And there's 5 to 6 others that like we just don't have time to go through all their incredible backgrounds. How much do you think that those relationships have helped you now as a VC?
Immensely. And venture capital is a funny business because who you know is so important. And ultimately venture capital And the lens of venture capital helped me really understand that startups are actually a human capital business as much as anything. And, uh, and somebody once said like one of the great, great experiments of startups is getting really, really talented, uh, typically technical people to work on the right kind of problems and the right kind of problems being the problems where you can introduce real transformation and you can have a lot of leverage with the technology that you bring to bear. And that you could take a little bit of risk and create something net new in the market. And that's a human capital thing. And even as these startups grow, you know, Vinod Khosla always says the company you build is the team you build. So being able to have these longstanding relationships and proprietary networks of really, really great people and staying in touch with them and building relationships with them through time is actually the single most important ingredient for venture capital success. Because it is the ingredient that'll help you identify startup success. And it's an ingredient that the best startups are consistently able to do. And it's because it's actually economically reasonably irrational to join a startup. And, you know, when you are a 20-year, you know, late career or mid-career expert in your field, to go work for, you know, to go work for a 31-year-old who's brand new to the field and just started a company is irrational, you know, to give up a $350K salary and go for $110K or even $70K, you know, and, you know, and move back in, you know, to an apartment with roommates to go be an engineer for something that doesn't work yet, that has no users is irrational. And yet people consistently do it. And in fact, some of the best people do it. And so having this human capital momentum and having frankly a human capital Perspective is super, super, super important. And, you know, some of the folks you mentioned have been great teachers in that and have been great thought partners in that over the years. And I frankly still feel like I'm a student in that game because every time I meet somebody, almost no matter who they are, it stands to reason that 10 years from now I'm going to be having this conversation with somebody and they're the names that are going to be brought up. And so it also just keeps you humble, right? And it gives you a beginner's mind and, oh, the future actually belongs to the unknown and the youth. And that's actually such a really, really cool thing about startups and about Silicon Valley too.
When you went back to Stanford, I would assume, but I don't want to assume too much, so I want to ask, how much different did you think about your experience? Were you like, okay, I'm just going to focus on startups, or I'm going to focus on relationships, or actually there were certain gaps in my knowledge that I want to focus on, I'll take certain classes. How did you approach that?
It was entirely different. Uh, at, you know, one of the interesting things about, you know, Mark Twain, I think, said that youth is wasted on the young. Uh, and there's, there's, there's something to that. And I apply it a little bit to undergrad. It's just like, gosh, if I knew what I know now, uh, when I went back to undergrad, how would I approach it? This idea that I've got this like clean slate and this canvas to be able to go sit and listen and experiment and meet whoever's deeply intense and passionate about the exact things that I am with no agenda and explore and see where it goes.
I would—
you wouldn't believe it, right? That'd be such an incredible gift. And so I was lucky to have just a little bit of a taste of that. Uh, and what I did, the way that I applied it was I took more computer science, uh, because I was really interested. And this is when We had just moved to Objective-C and then eventually to Swift on the iPhone, and so the iPhone development was really evolving in an interesting way. This was right before JavaScript sort of came roaring back and, you know, and took back over the landscape of front-end development. And so I was really interested in just being closer to that and being more, you know, more proximate to how frameworks were being applied and in developing software. And then I was very interested in meeting people, meeting people who were aligned. And frankly, not only had I changed, the world had changed too. You know, when I got to Stanford in 2003, computer science wasn't the most popular major. Econ was, and then bio, and then human bio, and then international relations, and then psychology. And, and so it was really interesting to be back and there were startup classes and there were people who had gotten to Stanford saying, I'm going to do a startup when I leave on the way in. It was just a very different environment. And so I was so thrilled to be like, oh, there's so many of my people here. And so I was able to again meet folks like you and folks like Stanley and Steph and all these folks who are terrific. And so I was definitely approaching it with more of a people mentality. But the other thing that I think is really interesting about institutions and, you know, these institutions of higher learning, particularly places like Stanford, is it also just gives you a really interesting lens on where the next generation of builders are going to be. And so again, this was 2010, 2011, so right in the height of social, local, mobile, and right at the beginning of, you know, what was about to be this marketplaces and mobile marketplaces, peer-to-peer collaborative, Uber for X, Airbnb for Y era. And I was able to see a lot of that. And so when I jumped into venture, it's not an accident that I worked at a place called The Collaborative Fund immediately thereafter. And we did Lyft and we did TaskRabbit and we did Reddit and all these companies that were in this peer economy because I had been so immersed in a lot of builders and a lot of, you know, a lot of young folks who were really excited about what was coming around the bend.
Collaborative Fund, my understanding was then East Coast-based. Is that right?
That's correct.
And did you move to the East Coast?
I did eventually move to the East Coast, but when I joined, I joined because my partner had wanted a, a person who had a zip code that started with a 94 to be on his team, to be, you know, eyes and ears and, and to be on the ground here and seeing what was going on here. So I went to Y Combinator Demo Day and Imagine K-12 Demo Day, and I would go meet founders at Stanford, and I was just trying to figure out what was coming, and it was an awesome, awesome, awesome time. And eventually, I did end up moving back to New York for a couple of years as we were scaling the fund, but being here was really valuable, and actually, it was really helpful to get to be a venture capitalist in both places because I was able to see some of the difference in how venture capital was prosecuted, but also how startup ecosystems were shaped from the lens of a venture capitalist in a market like Silicon Valley and then in a market like New York.
When I think about Collaborative Fund, I think of Morgan Housel.
Yes.
And I think of Psychology of Money and his content pieces. Don't get me wrong, I obviously you all have made great investments. But like, I think what an interesting combination of talents. How did that come about?
I credit Craig Shapiro. He really did a good job of, you know, of finding people who were unlikely bedfellows, as it were, you know, and having an eye for perhaps overlooked talent. And, you know, and I really appreciate that he saw something in me and was willing to, you know, to share some of the opportunity with me and allow me to be an investor at the firm and learn how to be an investor and grow up in a firm as a VC. You know, and Morgan similarly was at The Motley Fool before that. And, you know, Motley Fool was all about long-hold, you know, public securities and people who were, you know, acolytes of Warren Buffett and the like. And so it was very different to go from that to, oh, we're doing, you know, sharing economy tech startups at seed stage. But, you know, but, but, you know, we were able to convince him to join us. And he's an unbelievable storyteller, thinker, just the clarity and the simplicity and the persuasiveness of his language had a big impact on me. And so, we were lucky to have collected a good group of folks and it ended up being great training. It ended up being great training. A lot of seed investors, particularly between 2005 and 2000, call it '15, were autodidactic. They were self-taught and they were self-taught because seed itself was just emerging as a so-called asset class in a formal sense. It used to be— they called it micro VC for a little bit. They called it super angel before that, actually. And then it was just angel investors, right, who were just investing in their friends. And so many of the iconic funds that were put together in those early days, you know, Aydin at Felicis, Josh at First Round, Mike Maples at Maples Capital, and then Mike and Anne at Floodgate, Harrison Metal, Steve Anderson at Baseline, Chris Sacca were angels who became super angels and then super duper angels. And then we all realized in the whole industry that, you know, figuring out how to be the first institutional partner for a venture firm— sorry, for a company— had changed. And it had changed in a way that was really valuable. And if you could buy 10% of a company like Uber, a company like Lyft, a company like you know, like DoorDash, you know, you, you could absolutely change the trajectory of a fund at that stage. And so now almost all the firms are back to being seed stage and, you know, from General Catalyst and Andreessen Horowitz and, and Sequoia, you know, down to that original set of so-called super angels. So it's really interesting to see that trajectory. But that training of being sort of in that moment and seeing that phase change and seeing that realization as a dedicated seed investor, made a huge impact on me.
Collaborative Fund, Morgan Housel. Do you think that drives deal flow? Because like my awareness of Collaborative Fund was that. And do you think other founders like, oh, like you guys create great content and it actually will drive deal flow?
So there's top of the funnel and bottom of the funnel for deal flow, and they're quite different. Top of the funnel, the way to picture it is I'm thinking about leaving my company. I'm going to ask a couple of my closest friends who I should talk to about being my potential first investor, and then I'm going to think of some names as well. And so the job to be done on some level is how do you make sure you're one of the 3 or 4 people that my friends will mention? And then how do you make sure that you're one of the people that has unaided name recognition, right? Like, like, how do you, how do you exist in the zeitgeist where people are like, oh, I've heard this name and this person's an investor. I wonder if I should reach out to them. And if you can have a native name awareness and brand awareness and, and name recognition and, and can show up on that list, uh, it's unbelievably valuable because there are 1,000 seed funds and most investors are going to talk, or most founders are going to talk to 40, 40 of these guys. Maybe 50 if they're talking to a lot. And so you don't want to be in the 960 that don't get thought of or don't get that introduction, because it's just really hard. It's too competitive. And so anything that a venture fund does that gives them that unaided awareness, uh, helps. Now at the bottom of the funnel, it's about how can you help? How can you de-risk my business is really the best way to put it. And for some founders, de-risking the business, and for some venture firms too, derisking the business, uh, is, is best framed as give me the money and get out of the way, do no harm. And that's a real strategy. You know, our approach at Kindred Ventures and the way that we, we like to prosecute it is, uh, we want to be helpful and we want to be very clear to you about what help means and why we think we've earned the right to help in certain ways and, and where we probably shouldn't help and you should do it yourself. And if we can be very clear about that SLA upfront, then we can deliver great service if, you know, if we deliver on those things during the relationship.
Can you talk about your transition from Collaborative Fund to Kindred Ventures?
Yes, of course. You know, I was— after I left Collaborative Fund, I took a brief step back because I wanted to really reflect on where I wanted my career career to go writ large, not just whether I wanted to join a firm or start a firm or what I wanted to do. And, um, and I was still in New York at the time, and I met a cardiologist at Columbia who— he was actually just in the process of, of becoming a cardiologist. He was still at Columbia, and he was talking about doing something in the healthcare space, particularly doing something in, in cardiovascular disease digitally. And but had never worked at a startup, had, you know, had never really worked in business, uh, you know, had just been in medical training his whole career. And I said, oh, this is cool, I'll help you. And, you know, he was a very good friend and somebody I really admired. And so we proceeded to, to put together a startup. And the, the first person I called was somebody who had been a longtime friend of mine, uh, was Steve Zhang. Uh, and, and Steve came on and, and, and came in as the first check. And so Steve and I sat on the board together as a common and as a preferred for the first couple of months. And so we were on opposite sides of the table for about a year and a half. And I had an amazing experience, you know, getting Heartbeat going with Jeff. And we, you know, found a CTO who had pitched me a startup back in the day that I remembered and kept in touch with. And we went out and and raised seed investing, and it was very humbling to me to be walking into a bunch of these venture firms who I won't name and saying like, hey, can you fund my startup now? And them looking at me like, I don't know. I don't know if you've got it. It's productively a very humbling experience. But thankfully, credit to my partner Jeff, who was able to put that business on an amazing trajectory, and we now have seen a million patients, you know, we're the largest cardiovascular disease platform in the United States and, you know, in 50 states and all that. So, we've been able to get to scale. But that experience both sort of gave me a renewed sense of empathy for the founder journey, particularly the zero to one, and it gave me a boot camp of partnership trial by fire with Steve. Steve Jiang. And at the end of that, Steve and I kind of looked at each other. We were like, that was really hard, and I think we can do that again. And, and so then we decided to, to raise a fund together. And Steve had been investing since he had been an early investor in Uber, again during this collaborative economy era. He had been very productive in that era and had invested in a number of companies and had put them in a brand called Kindred Ventures. And so He said, do you want to raise a fund and turn this into a venture firm? And, and I said, heck yeah. And the reason why I wanted to do it in general was because I did think that there continued to be an opportunity for a lead investor who was truly committed to the early, who had lived experience in the entrepreneurial part of the journey, and so could bring real hard-learned lessons to bear on how to help., and who was willing to take, you know, real risk. Uh, you know, I actually think particularly in the SaaS era of venture capital, uh, and, you know, in the ZIRP era too, you know, which people talk about ZIRP as 2021, but ZIRP was actually a pretty long period. It was a very long period. Uh, and a lot of how venture capital and, you know, was employed then ended up being, in my assessment, shaped very differently from a risk standpoint. There was, it was pretty much only a go-to-market risk. And a lot of the most interesting companies in the history of venture capital had all sorts of different shapes of risk that the fund was able to underwrite and support and de-risk through partnership. And we wanted to kind of get back to that. So be willing to be on the frontier, be willing to do the stuff that is hard, be willing to be the only term sheet at the table. And be willing to be the first one. And I was really excited about that. And Steve and I were very aligned on that because Steve had been doing that himself for, you know, for a decade at that point. And so we just totally gelled over that concept and then came to market.
Fascinating. We did a walk and talk in 2019 and we kind of met here and started walking towards the Ferry Building. And this is when you said, hey, I'm going to be working on something new. And you gave the very high level. That the same time of when you were transitioning to Kindred?
That's right. That's exactly— and in fact, at that time, uh, we had very quietly closed, um, on, on, on some capital. We were very lucky to have been able to, you know, get some investors who had known either me for a decade or Steve for a decade, uh, you know, to be our early institutional backers. And then we had a lead investor who, who met us during the fundraise that that came and anchored that first fund. But we were, but we were really excited to bring a new, you know, a new brand to market and, and a new lead seed brand that, you know, was muscular about risk and muscular about help and willing to do those things early. We were really excited about that. And here we are, you know, 6 years in.
So during that walk and talk, a name that came up and a name that oftentimes comes up when we meet just because of how we met is David Hornig.
Yes.
Uh, David, I— is a mentor to me, uh, tremendously helpful. Um, we know he's in the book Give and Take. He truly embodies that. Um, can you share about your experience with David?
Absolutely. He's, he's a mentor to me too. And, you know, the— what I was saying earlier about how this business is unique because every 5 years somebody who was totally unknown suddenly emerges to become one of the most important people in this ecosystem, the economically rational thing to do is to, is to give back and to look out for the little guy. And because you never know, uh, but some people do it not just because that may make the money down the road, but because it's the right thing to do. And David is totally one of those people. And, you know, and so when, you know, I was a student, when I was, uh, you know, a, a fledgling venture capitalist who you know, who was just getting my sea legs under me. He was an awesome partner in just helping me think about partnership and thinking about portfolio construction, in helping me build relationships, introducing me to folks. And it's one of those things where, you know, when you've got incredibly generosity from somebody, it's contagious and you want to pay it forward. And, you know, and so he engenders that in so many people and, you know, folks like you who end up being so generous with your time and generous with your resources. And, you know, and I am inspired by that and I try, you know, I'm still falling short, but I try to, you know, to share that same mentality.
Similarly, I fall short, but try to follow that. And I hope this isn't too much of a stretch, but there's apparently a whole school of LPs that come from David Swenson. In Yale. And I feel like David Hornick's got a whole school of VCs, Stephanie Zhang, Janelle, you, me, and many others, Ernestine, who try to embody and live his type of ethos.
Absolutely.
Kindred Ventures, can you share more about it? You did mention seed, but now many people will ask, do you do pre-seed? And so does seed encompass pre-seed in your books? And are there certain industries you all like to focus in on?
We want to be the first institutional check, and we will do seed, we will do pre-seed, we'll do formation, we'll do soil. We have funded people to leave their companies to figure out what to work on and effectively served as a co-founder with them before. We've funded people that have been operating their companies for 2 or 3 years but haven't raised any capital. And finally unlocked something that meant that it was appropriate for them to take on some scale capital. We've written an initial check as small as $100K. We've written an initial check as big as, as $8 million. And it's important for me to respond that way because company formation is very heterogeneous. If you're building new autonomous systems,, it's very different than if you're building a new consumer social mobile app. You need different capital, you have different capital requirements, you, you know, in the AI era, if you need to spend on compute and if you need to get access to, to some, you know, to some, some R&D capitalization, that's a totally different cost model than if you're, you know, if you're able to do something at the vibe coding level and, you know, and, and ship it on the cloud, right? And so there's as a result a need for investors to be similarly heterogeneous in how they invest. And I don't think the programmatic— if it's less than a million-dollar round, it's a pre-seed, if it's a $2 to $8 million round, it's a seed— taxonomy makes any sense anymore. And some people will say it's because very, very big funds are inflating rounds, and that's part of it. But I actually think the primary reason is that startups are looking more and more heterogeneous in a way that's good. Uh, you know, we have in, in the same fund invested in companies that are building e-commerce shopping infrastructure sitting on affiliate rails, and we've invested in companies that are building alternative materials for the, for the luxury industry starting with leather. And how those are capitalized and how those get to market actually looks very different. So to your point about where we invest, We do have areas of focus and practice areas, but those evolve and they're intended to evolve because the future changes. And, you know, and the future is, is unknown. And I think a little bit about venture as, you know, we are, uh, you know, sailors on the open seas. There's a reason why they call it a carried interest, because you're carrying it across the open water and you don't know what you're going to find out there. And so I think you have to be a flexible thinker about about, uh, the sectors and about the, the themes. But you also need to have depth because that's how you win, that's how you persuade founders, and that's how you help founders. And so we have practice areas between Steve and I which we kind of divide the universe into that will allow us to move through the world with persuasiveness and move through the world with clarity and then create gravitational pull around certain areas. And those have developed and have evolved over the last 6 AI, AI, everyone's talking about AI.
We shared a deal recently, that company's pre-seed valuation was at $100 million post-money. We've seen certain deals like that, and we've also seen certain non-AI deals that were less than $10 million post-money. And so the question is, what's your take on the state of AI? Overvalued, not? Lots of opportunity, top of hype cycle?
The hardest thing about assessing venture ecosystems, cycles, markets, and networks is this business doesn't follow normal distributions. This is a business about outliers. And since it's a business about outliers, if you look at the average and build your models, your mental models, your frameworks for the world based on those averages. When somebody comes in in 2006 and pitches a Series A at a $100 million valuation with no revenue, as, you know, as a, as a college dropout, uh, you'll say no because it's so far outside of the average. And that's why so many people missed Facebook. And so what do I think about the state of AI and frankly, the state of any sector vis-à-vis prices is I don't think anything about it. I think I'm in the business of extreme outliers. And when I meet an extreme outlier, I fight tooth and nail to partner with them. Sometimes extreme outliers present as really high-priced opportunities, but sometimes they don't. An extremely high-priced opportunity is a price outlier, but it's not a value outlier. And we're in the value outlier business. Right. And so I think it's really important to separate and distinguish there. Even, you know, at the height of the dot-com bubble, there were companies that one could have made great money on. You know, I remember talking to Fred Wilson about companies like MercadoLibre in LATAM, even companies like GeoCities. Which ended up being very productive exits for, for, for his firm, you know, for his firm Flatiron Partners. And so I think that a great venture investor should be able to make money in times good and bad if they are hyper-focused on outliers, and then if they're hyper- internally consistent to their investment strategy. So if you can't make money on buying 1% of a company at a billion dollars, because even if it appreciates 100x, it doesn't return your fund, then you've got to figure out how to adjust that. But that's an internal thing, right? That's a strategic thing. But is that company overvalued or undervalued? Always depends on the company. Now, that said, the question that you're probably getting at here is that there does seem like there's a tale of two cities, right? And that tale of two cities today is so much of the capital markets. And this is even true particularly in 2024 in the public markets where if you were in the Magnificent Seven or even just if you were in the magnificent NVIDIA, everybody wanted to hold your stock and own it. And if you were in anything else, everyone was like, eh, but it's not AI. And all the way down to pre-seed, so to speak. If it's an AI thing, you're coming out of DeepMind, right? And you're talking about the right kind of infrastructure. The, the— there's a lot of competition, whereas if you're not, there's less competition. But the amount of competition, I don't think, is necessarily an input on the quality of an opportunity, and it's orthogonal. Uh, now some people think that a lot of competition means an opportunity is good, uh, for reasons that are sensible. The market is full of smart actors, and they're working really hard to identify value. And some people think that If there is competition and opportunity isn't good, I think because it's overpriced or because it's overhot or it's overchased or it's over-shopped or whatever it is. I don't think either of those is true. I think you have to have internal conviction about what you're looking for, and then you have to be willing to pay a high price if that's what it takes when you have that conviction.
Fascinating. I want to talk more about Kindred's concentrated portfolio. Which I think is orthogonal or contradictory or paradoxical given how early you go, because typically it's the earlier you go, the more bets you need to take because there's more fatalities, mortalities, etc., however you want to describe it. How do you all square that?
There's two ways to square it. The first way to square it is how do you want to spend your time? So, Steve and I have structured this firm in such a way that we would do it for free, that we would even pay to do it because we love it. We love it. And we love it because we get to go deep with founders. We love it because we get to spend quality time with founders. We love it because we get to be the principal agent in the founder-investor relationship. And a lot of people are just along for the ride. We don't want to be. We don't want to be along for the ride. We want to be the main partner. We want to be the person you call when the chips are down. We want to be the person who, who knows first when you've, when you've hit eureka. And there's only so many hours in a day, so you can only do that for so many companies at once. So that's the first input, honestly, is you have to structure your work. And this is true of everyone in life. You have to structure your work in a way that you can do it really well with a lot of joy for a long time. And if you can't do that, you're going to burn out or you're going to phase out or you're not going to bring your best self. So that's the first and most important thing, honestly. But the second is a lot of people talk about how the relationship between concentration and risk comes down to earliness. But I don't actually think that's necessarily true. I think that the relationship between concentration and risk also comes down to deal flow. If I am a guy off the street who has never met an engineer before and I'm investing in companies that are more mature and I'm investing in 25 of them, uh, or 20 of them or 15 of them or 50 of them, that's very different than if I'm somebody who has a deep network and is getting founder references and is really able to get context and has been spending a lot of time in the market. So understands how that market is changing and is just like close to the problem, right? Uh, and so one of the things that Steve and I think a lot about, which is somewhat of a, a different frame on this of this pithy quote. Most people say your fund size is your strategy.
Mike Maples.
Mike Maples coined that phrase. Hat tip to Mike Maples. Your deal flow is your strategy. Your deal flow is your strategy. And if you are seeing all of the people coming out of DeepMind versus none of them, that is a fundamentally different picture. Of course it is. If you're seeing all of the people that are working on brain-computer interfaces that have studied them at the top universities in the United States and around the world versus not, the two people who are BCI investors are going to have different experiences. They're going to need to structure their portfolios differently. They're actually going to need to, to spread the risk in a different way. And so on some level, a dirty secret that I guess is not going to be a secret anymore because I'm saying it on this pod, is we think that we can afford to concentrate a bit more because we have really good deal flow. And we think that we've been working really hard to curate really interesting bodies of people that, uh, keep us in mind and that give us an early call. And, you know, and that, and that invite us to the party. And our hope is that we continually can earn that by being really helpful, and that we can earn that by adding value to the companies that we meet.
So much insights there. I really love that line, your deal flow is your strategy, and that's actually how you should build your strategy as opposed to just fund size and number of investments.
Um, here's where it gets tricky. You don't know how good your deal flow was until 7 years later, maybe 10 years later. So you may think You are seeing the absolute best of the best. And in fact, a lot of venture investors think, oh, I'm seeing exactly what I need to see, but only God knows right now. So the nuance of your deal flow is your strategy is, well, how good is your deal flow actually? And what methods have you taken to continually refine that and to be intellectually honest about that? What are your KPIs to determine whether or not you have good deal flow? Because we don't know what the exits are going to look like. We don't know how these companies are going to turn out. And so that's where there's, I think, a level of secret sauce and nuance that, you know, I would invite a listener to think about when they're pondering that question.
Earlier, you had said that early stage is heterogeneous, and you had mentioned we want to be flexible. And then the one that I felt really dialed in on my understanding of Kindred is we want to be the first institutional check into a great startup. And you had mentioned several instances of how that might look like. Our last episode we released was with Francisco Gomez of Volt Fund, a fund of funds that invests in company creation entities like Pioneer Square Labs or Atomic. How much company creation do you all do? Like, you will co-found a company with someone, or you'll have an idea and find a founder?
Those are two different things.
Yes.
And, and the nuance is all the rub for us. We have typically done about one every 18 months. So about 4 or 5 since we started raising funds for Kindred. And, uh, and at the moment we have, uh, 4 of them, uh, or 3 or 4 of them that are continuing to grow well, that have millions of dollars of revenue, that are, that are scaling. The thing that I would flag as the most important thing about formation that one has to be wary of is adverse selection. It is, as I was saying earlier, irrational to quit your job and to go make no money and to forge something into the universe out of nothing. And it's extraordinarily hard And that's a feature, not a bug. It's a feature because that's going to self-select to people who are unbelievably persistent, diligent, creative, resourceful. And if you take away that agency and you take away that core feature, then it's people who want to cosplay startup. Cosplaying startup, you just don't win. Uh, so when we think about formation, we're very careful to not overly form, frankly, and not to give too many resources. And similarly, we're also careful not to take too much equity because the founder that is willing to give me 50, 60% of the equity of a company, even 30% of it, I don't think is the founder that I want to back. I think the founder is like, no, give it to me because I am a lion and I'm going to go become the king of the jungle, is probably the founder that I want to back. And so how do you square that adverse selection circle is one of the things that we think about quite a lot and is part of the business design of our formation. So in most of the cases where we have partnered with an entrepreneur to start a company, we've been very explicit about taking a backseat. And, and we'd rather be in a service mode for them where we are an invisible co-founder than be an overbearing, even if we're providing lots of infrastructure, because the adverse selection risk is too high.
This leads to the next question around structure, and that is board. How do you all approach boards? There are certain funds that are like too early at the first institutional round. Other folks are like, nah, first institutional rounds are actually pretty big rounds and you probably actually need some structure. How do you all think about it?
We do a board observer in every investment that we lead, or at least we ask for one, and we ask for one, and then we ask the founder to do board meeting light at the beginning. And the reason to do board meeting light is you want to learn how to zoom out and be accountable to stakeholders, to critique your story from people who have an outside perspective, but that are, you know, that are motivated to the upside. And you want to get into the habit of it because if you're any good at this, you're going to be running board meetings well into being a public company. So there's no time like present to learn how to do it well. Governance is a different matter because governance is what a board director is really about. If there's any need for real governance at the seed, in most cases the company is not going to work. And I say in most cases because sometimes in, for example, a fintech company, or sometimes for certain international investments, there's there's governance reasons that create, you know, guardrails or the right regulatory framework or something like that for a startup. And we're happy to do that, and we have sat as directors. Now, later on, being a board observer and having access to the boardroom in one way or another, it's really important for an early-stage investor because almost as soon as the money goes in, I'm aligned with the founder. I'm probably the single most aligned stakeholder with that founder, which is at the very, very bottom of the preference stack. Uh, the founder is going to eat last, I'm going to eat second to last, right? And so in that way, being able to advocate for the common, advocate for the long term for the company, not let the latest interests at the capital side dominate the conversation about where a business needs to go, is a healthy counterbalance for founders. And so we like showing up to the boardroom for the Series D because we have the observer right, and, and we like showing up and then, you know, having, having it out with the founder after and helping them think through how to manage a board and helping them think, you know, coach them. And that's an important role for us. So I think boards are very important. I think boards at the early stage serve a good purpose, but if you're joining the board as a director so that you can control votes before the product market fit point, uh, you've missed the point.
1,000% agree. And, and I really, really, really respect and totally align with your viewpoint on boards. Kindred— where do you want or see Kindred 3 to 7 years from now?
3 to 7 years from now is a really interesting time frame because we're in the midst of what some people think of as the true moment of the Third Industrial Revolution. And what some people think of as the true moment of the information era transitioning to the intelligence era. And in that, there is extraordinary, extraordinary cultural change that we're in the midst of at the macroeconomic level, at the cultural level, at the political level, at the technological level, at the corporate level. And so I don't want to be overly specific about where we'll go, But what I'll say is this: there are some things that we think of that we're religious about. And one of those things is the practical utility of technology and why to start a company and what kinds of companies we want to partner with. And so in 2021, we didn't want to partner with token companies because tokens go up. We wanted to partner with companies that were building decentralized systems or building centralized technologies on decentralized systems that would provide novel productive utility to end users. And if you could articulate that, we'd be excited to fund you. And if you couldn't, no matter how much that token would go up, we just wouldn't do it. And I would say that the same is true of today, which is that we want to fund companies that provide novel and well-articulated utility to end users. And those could be developers, they could be enterprises, and they can be consumers. And our view is ironclad on that. And it actually is a very helpful compass for us because we don't have to make an academic point about, is this just a ChatGPT wrapper or not? No, we don't actually have to address that question. And we have theses around it. But when we look at a startup, we think, how deep is the utility to the end user here? And how much of that utility are you driving? And if it's high, we'll fund you. And so as a result, we funded a number of ChatGPT wrappers in 2023 and 2024. One of those is Perplexity, which is one of the more, you know, fast-growing—
use it all the day—
companies in the market. And, you know, and today we're funding a number of companies that, you know, some other thesis around the foundation models are going to eat it all, or, you know, the agential systems are going to make the SaaS model irrelevant or a lot of these theories, which is how a lot of people will approach thematic investing. We try to swim orthogonally to those and just think about what's the practical utility for the end user. And does this founder have an ability to continually offer incrementally and rapidly incrementing marginal utility on top of what they've already added? So that's one of the pieces of religion that we have. And that's what we focus on in Zero to One and in product and go-to-market. What that means for 3 years to 7 years from now is we're probably going to be able to do that for a meaningfully larger segment of the economy. Uh, and some of that segment of the economy means we're probably going to be able to do it for, uh, property and casualty insurance in a way we've never done it. We're probably going to be able to do it for mining in a way that we've never done it. We're probably going to be able to do it for government go-to-markets in ways that we've never been able to do it. Because the technology is really flattening access to superpower capabilities at incredibly accelerating rates. 7 years from now though, uh, I don't know. It could be that we're concentrating and that the number of companies that are getting to scale, uh, has shrunk. And it could be that the companies that are getting to scale are getting to trillions of scale faster, but there's fewer of them. That could be the case. It could be the case that venture capital itself is AI agents, and I'm, you know, just supervising the supervisory model. And in those human-in-the-loop models, I am the human in the loop, right? Like, it could very well be because the intelligence age is going to be a little bit wild. And so we have to be humble and open-minded to the idea that there's no sector that is inviable. And is not liable to being totally disrupted by the intelligence age. And that's a worthwhile, both humbling perspective, but also challenge to continue to think deeply around practical utility for end users and then be courageous about what that means.
Two things that I— two words that I think of to summarize what you just said. One is utility. And I feel like if it wasn't Kindred Ventures, it'd be Utility Ventures, maybe. Or utility VC. The second is, um, uh, there was a recent clip I saw around how biological intelligence is shrinking per day and machine intelligence is exploding per day. Um, we're running out of time, so I want to run through some really friendly rapid-fire questions. Some favorite books?
Favorite books, uh, on the fiction side, uh, I love some of the old classics. Um, I love Dostoevsky's Brother Karamazov. Deeply. I love The Great Gatsby, Great Expectations, Charles Dickens. I love Chinua Achebe, Things Fall Apart. On the nonfiction side, Bill Janeway has an amazing book, Doing Capitalism in the Innovation Economy, that I think is really good. I'm reading a biography of Ibn Saud, who was the first ruler of Saudi Arabia, first modern ruler of Saudi Arabia, that has been exceptional. And, and I've really enjoyed that. I read a book called The Box, which talks about the creation of the shipping container and how the leveraged buyout and shipping and the shipping industry kind of all emerged together. And that has some really interesting analogues in venture capital.
Some of your favorite movies?
Favorite movies? Gosh, I love the Christopher Nolan series. I am a big fan of the Italian mafia movies. I love the heist movies. Heat, Michael Mann, excellent film. I'm a big fan of a German Cold War spy movie called The Lives of Others. It's a beautiful film that I think people would enjoy. Most recently, I've been just gobsmacked by Moonlight. I thought that movie was amazing. Big fan of movies.
Of Michael Mann's Heat. If you want to make moves on the street, that line, it's really impressive. The favorite travel spots.
Favorite travel spots. Oh gosh. I love going to my parents' childhood home and seeing pictures of them when they were young. And I love that because it feels a little bit like sand slipping through my fingers, and so it feels extra special because it feels impermanent in a very uniquely beautiful way. I love taking my kids to the mountains, and I love the water personally.
One of the times I ran into you was you taking care of your kids, and I could see through that interaction just how much you enjoy being around them. We've taken way too much of your time. This has been extremely delightful, just learning about your journey, learning more about your journey. Wishing you and Kindred tremendous success as you find incredible companies that provide incredible utility.
Thank you, Tim. It's been a pleasure.
Thank you.
More from Kanyi
Building with Corgi - Kanyi Maqubela in conversation with Nico Laqua & Emily Yuan
Building with Corgi - Kanyi Maqubela in conversation with Nico Laqua & Emily Yuan
Acceleration & Balance The American AI Strategy presented by Kindred Ventures

2026 will be a very important year for venture capital, says Kindred Ventures' Kanyi Maqubela
2026 will be a very important year for venture capital, says Kindred Ventures' Kanyi Maqubela


Beyond Unicorns: Kanyi Maqubela on Identity, Innovation, and the Future of Venture Capital

Beyond Unicorns: Kanyi Maqubela on Identity, Innovation, and the Future of Venture Capital

Investing in Visionary Startups: Insights from Kanyi Maqubela of Kindred Ventures