The Ultimate Guide To Renovation Course - Module 11: Building Equity & Lending Strategies
Let's Chat and a co-host walk through how to build equity after renovation, use lines of credit for deposits and work, and service debt with rental income. They cover tax deductions on investment loans, cross-collateralization risks, mortgage tools like offset accounts, and why income protection insurance matters.
Chapters
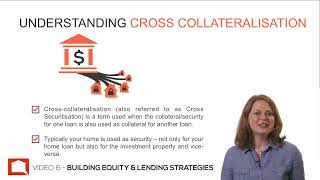
So let's talk about building equity. As you can see from our example, if you start with just $128,000 in equity, this represents quite a healthy potential deposit. In fact, once you have a 15 to 20% increase in value, you can use the extra equity to fuel the purchase of a property and so on using exactly the same formula. If you're smart with your renovations, you could, in the right market conditions, enhance the value of your property by 100% of the cost of the renovations. In order to make this work without draining your personal resources, you need income. This will come from your own salary and from your rental properties to service the debt. As you've learnt in Module five Costing and finance, if you optimise the rental income and maximise the tax benefits available, you can effectively offset most of your outlays. Not just the loan interest, but also the strata fees, rates and all the other fees. You do need to know your numbers and go and check them. And be careful. As already noted, it's a really useful idea and a risk management strategy to take out a line of credit and and not max it out so you can draw down for emergencies or even have a fund for shortfalls. The biggest issue you'll face is servicing all this debt so that you can replicate this strategy to continue to build your portfolio. Remember, that yield keeps your growing portfolio growing. Once you can no longer service more debt, you can wait for your income to grow or look at some other innovative lending strategies. In fact, for those who are maxed out, buying within a self managed super fund can be an alternative and something you may want to investigate. It will not suit everyone, but it is one option. It can be frustrating to see your portfolio grow and not being able to tap into the equity because you can't service the debt. This is when your mortgage broker really comes into their own and can show you options. And how different lenders and their different policies may might allow you to do so sooner. So here's an example. After you refinance, you then look at purchasing a property. You'll use the line of credit to provide the deposit and maybe the cost. Let's say 20% for the new property. For example, assume it's worth $300,000 and a deposit of 20% is $60,000. You could put down a lower deposit that is 5 or 10%. But remember that incurs in mortgage insurance. Now let's assume $20,000 for stamp duty and costs and $20,000 for a renovation. Hence you have spent $100,000 of the $128,000 you have available. The accessible equity can be secured by a line of credit which gives you payment flexibility. Not only do you have control over the length of the loan and how you repay it, you you also have the flexibility to pay the debt at any time without penalty. And you can control the amount of payment you make each month as long as you cover the minimum. The minimum is just the interest only, or as much as you can afford. The larger your monthly repayment, the quicker you'll pay off the line of credit and lower your overall interest costs. If minimising the amount of interest you pay over the lifetime of the debt is is important to you, then a secured line of credit may work for you. But remember, this is tax deductible debt. So if you do have additional funds available, they should go to pay your home loan off first, which is non deductible debt, that is your original loan. Accessing equity is a core strategy in building a property portfolio, but there are caveats, for example limitation on serviceability when loans are cross collateralized. Cross collateralization, also referred to as cross securitization, is a term used when the collateral or the security for one loan is also used as the collateral for another loan. Typically, your home is used as security not only for your home loan, but also for the investment property and vice versa. Many investors are tempted to go to their existing lender if they already have a mortgage on their home or in another investment property. It's natural to do this because you have an established relationship with them and they have lent to you in the past and therefore will give you favorable consideration for another loan if the numbers stack up. But there are a number of considerations. You can take out another loan with your existing lender, but it's important to make sure that your lender structures your loans properly. If you plan to build your property portfolio and your loans are not structured correctly, this will greatly inhibit you in the future. Cross collateralization is no extra work on the bank's part, but structuring your finances this way will make it harder for you to tap into equity as you build your portfolio and the lender can start dictating terms to you. That is your next loan is going to be a P and I loan. In short, cross collateralization involves using two or more properties as security for a loan instead of maintaining six separate loans for each property. The argument against using the one lender is that cross collateralisation is unwieldy, locks you into one lender, and makes you more vulnerable if something goes wrong. It's always useful to take a case by case approach and look at the pros and cons of each strategy against a particular situation.
Most investors seek flexibility in their mortgage and you can do that in a number of ways. For instance, an offset account, where you can make additional repayments into the offset account, your savings account, and against that account, the amount of the loan is deducted and that is what interest is charged on. Maybe you'd like the flexibility to be able to fix rates at your own discretion. Or having a split loan, you want minimal exit fees when you're looking at your actual loan. And then there's income protection insurance, that's.
Another way that you can obviously protect yourself.
So it's all about covering yourself and having a bit of a buffer, your own protection. Now there's a number of ways to do this. We use the term mortgage flexibility here in the context that where possible, an investor may have a mortgage offset account which they can accumulate cash in savings. Now this could assist you in times of when you need that money. For example, some investors may deposit their tax refund check directly into their offset account. It benefits them month by month in improving cash flow on interest only loans, but also gives them a bit of a buffer. Other investors take advantage of lower interest rates and may maintain repayment schedules.
Now this could help them for building.
A deposit for the next loan, for instance, or the next property. But in addition to that, it's a bit of a buffer for them. Flexibility means having the option to increase repayments, switch loans at any time, or to close a loan in the case of the sale of a property without penalty. Now let's look at income protection insurance another way to protect you and your family. Now this is often one of the most important decisions for anyone to make and that's how to protect the family in case of accident or permanent incapacity arising from an accident or a health related event such as a stroke or illness. If an investor is the principal income earner in the family, and the family is embarking on a long term plan to create wealth and financial freedom for themselves, it is the incumbent on them to consider what would happen if they could no longer work either permanently or for a significant amount of time. If you're a property investor, you need to consider protecting your continued ownership of that asset with income protection insurance. As noted earlier, income protection insurance should not be confused with mortgage insurance, which.
Is required by most lenders where the.
Loan value exceeds a certain percentage, usually 80% of the value of the property. Mortgage insurance protects the lender in the event that you default on the loan. Income Protection Insurance protects you, the investment property owner by providing a benefit in the form of regular repayments in the event that you are unable to earn the income that you were previously earning due to sickness or injury. While each of us have our own make up when it comes to risk tolerance, we few investors have the capacity to withstand a major hit to their primary source of income when they're committed to a property portfolio. There are plenty of people who have modest gearing that is around 5060 loan to value ratio in the property investments that they have, which is achieved through inheritance or high income. But many property investors are required to stretch themselves financially to get their full foot in the door for that very first property and then continue to gear up as they build equity and buy more property. This risk can be addressed by taking out an income protection policy which will provide benefits in the form of up to 75% of your nominated pre sickness or pre injury income. For people who are self employed, they can nominate a figure that addresses their income requirements in consideration of their total living costs, including any negatively geared properties. Emergency measures to protect your assets as most investments require borrowings, usually sizable amounts, there is no point pretending that life is always going to go as planned. That is a sure recipe for losing money and possibly all of your money. To avoid being crunched by a must sell event, you should consider an emergency strategy made up of a mix of of an emergency fund or at least an emergency line of credit. Many investors, for example, when taking out their investment loan for a particular property, establish a line of credit over and above the amount required of at least 5 to 10% of the funds borrowed. These funds can be used for emergency purposes to fill temporary shortfalls. How large this should be is dependent on the property investing strategy you pursue. Some investors build a pool of emergency funds by putting aside a percentage of the rents collected. The most effective and powerful emergency exit strategy is to keep LVRs at reasonable levels.
More from Let's


The Ultimate Guide To Renovation Course - Module 5: Self - Employed Low Doc Loans



Rob Flux Ambush - Convince me I should consider Property Developing as a strategy 3,2,1 GO!

The Ultimate Guide To Renovation Course - Module 4: Recognising a Property's Potential

YPS Club Mar 24: special Guest Peter Wargent describes how Australian properties are so resilient


The Ultimate Guide To Renovation Course - Module 5: Interest Only Lenders Exposure

