How to Get a Loan for Your Business with Mark J Kohler | CPA, Attorney
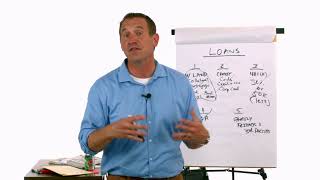
This content was created by MARK KOHLER. This content was uploaded by MARK KOHLER. This is a YouTube/Facebook Live video titled "How to Get a Loan for Your Business with Mark J Kohler | CPA, Attorney" (recorded July 18, 2019). It is an instructional live presentation and Q&A hosted by Mark J. Kohler (CPA, attorney, and author) focused on borrowing for small businesses. Mark covers five borrowing approaches (land-secured loans, credit cards/corporate credit, 401(k) loans, SBA-guaranteed loans, and loans from friends/family/third parties), emphasizes correct terminology (investor vs. partner vs. lender), details promissory-note essentials (amount, interest rate, payment terms, security/collateral), discusses corporate credit cautions, S-corp capital contributions, and practical tips for documenting loans and avoiding securities issues. The session includes live audience questions (moderated by a speaker labeled SPEAKER A and mentions of Maria/Rosalie), book and workshop promotion, and giveaways. Target audience is business owners seeking funding and legal/tax guidance.
Chapters
Two.
Hey, welcome everybody to another Facebook Live about your finances, your taxes, your legal. Today we're going to focus on legal and I want to talk about how to get a loan in your business and what type of loans there are out there that you might want to consider. I've had several texts and phone calls this week and working on a new article for this and I thought we should do a Facebook live on the topic. So don't go anywhere because if you're a business owner, you're going to need to borrow money once in a while or you may put it on your credit card or a credit line or need an SBA loan or borrow from your 401k. All these different strategies are part of that borrowing method of getting money into your business. So I'm here for the next half hour answering your questions down below. I've got some free books to give away here that are pretty expensive actually. There's a lot of value there. So I want you to stay tuned. I'm going to announce our book winners from last week, make some important announcements about some upcoming tax and legal education that'll be really helpful for you and your business. Remember people, you were the captain of your own ship. You cannot rely on your accountant or your financial advisor or your lawyer to run your business. They are only there as resources as you identify what you need to worry about. So I'm here to give you some things to think about. And today is the topic of borrowing lending. How do I get money into my business with a borrowing format? So let's dive into it. My name is Mark Kohler, I'm a CPA attorney, best selling author and I'm here for you every week. Entrepreneur Live, Mark Kohler, Facebook Live and YouTube. So please continue to tune in. Alright now the first point I want to make before we get into the types of loans is I hear people use and abuse the word investor the time and it can put you in jail. It is a bad thing to use the I word, the investor word. So let me explain what I mean by that. And my cameraman, am I okay to do this right here? We're looking good. We've got lender, partner, investor. They are three different people. And I get on the phone with clients all the time. They're like, I'm looking for an investor. I go, really? You've got a securities document, you've registered with the SEC and you're, you're allowed to go out and raise money. Are you doing a crowd fund? No, I'm just looking for Someone to put money in my business. Well, you can't call them an investor unless you filed the proper SEC paperwork, sometimes called a private placement memorandum. It's like your own little hedge fund, your own little mutual fund, and you're going to raise money from people. Think of a silent partner. That's an investor. And I know many of you want silent partners. That's an investor. And if you don't check all the right boxes, cross all the right T's, dot all the right eyes, and you lose their money. Buckle up. It is not pretty. So don't use the investor word unless you have a securitized document that allows you to go out on Facebook or Instagram and raise money for investors. That's a dangerous word. Now, what do 99% of my clients do? Because we set up these deals we do all the time. Jaron Bergerson's our guy in our office that does all this. But the other 98 out of 100 clients of ours use partners or lenders, and you can't be both. You're either one or the other. So if you say, oh, I want a lender, I just want someone to loan my business money, okay, call them a lender, not an investor. I'm looking for someone to lend my business some money. That sounds great. Let's talk terms. And we're going to come to that. But then if you say, well, I'm going to borrow money from them, and then if I make money on this house deal, they get a piece of the profit, well, that means they're not a lender anymore. That means they're a partner. A partner gets a piece of the profit. And if you do a loan document where they get a piece of profit, then they morph into a partner. And don't tell me, oh, well, that's a participating note. And I went to this guru seminar last weekend at Holiday Inn, and those guys from Nevada and Wyoming and Delaware, they were cool, and they said I could have a document that says they get 10% and then 20% on the back end. Okay? You get in a writing from them that if there's a lawsuit, your lender is not liable as a general partner, because if they get a piece of the profit, that means they're treated as a partner under corporate partnership law. Be careful. Don't listen to some guru out there. Talk to your lawyer that's going to stand behind your documents or with malpractice insurance and tell you how it really is. And just because it sounds sexy from the stage doesn't mean, it's right. So partners get an llc. Partners have a partnership agreement. Partners get a share of the profit. Partners get to make decisions. They are not silent. You have to go to them and ask for advice. And what do you think about this decision? And what do you think about this? And. And you're like, well, I don't want anybody to tell me what to do. Then go get a security document and treat them like an investor. But if you say, oh, you're just a silent partner, I'm going to promise you to make you money, and it's going to be awesome. You lose their money, they're calling the state and federal securities commissions and probably local prosecutors for ripping someone off and making promises. Just go watch America's Most Wanted. Go watch Dateline. This happens all the time. So you're going to do a regular partnership agreement. You're going to have regular meetings and run it like a democracy. This is a democracy. This is a dictatorship. And a dictatorship, believe it or not, is okay if you do it the right way. Now, we're not going to talk about partnering today, except I wanted you to know that's not a lender. We're not going to be talking about securities. I have chapters and books on this, and I talk about it all the time. But that's not what we're focused on today. Today you're going to borrow money from people or a bank or the SBA or something. And, well, an SBA doesn't really loan you money. They guarantee the loan with the bank. But anyway, we're going to talk about this lending, which means they get an interest rate, they get a term, they get a document called a promissory note, and we're going to call them a lender. They don't get any of the profit. They can't tell you what to do. They're silent, but they get regular interest payments or a balloon. Okay, so now with that said, I'm just going to throw it out there. Do we have any questions from anybody so far on this topic? Okay, good. You're hopefully soaking this up. This is deep stuff. Normally we're talking sexy regular Q and A stuff on tax and legal, but you've got to know this lending stuff. So hang with me. Hang with me. Look it, here we go. We've got five ways that you could borrow money. The first one, and I'm going to focus on number five. But I want to again lay these out. There's so many different ways. Number one is with land as collateral. If you're Going to buy land. Think of your own house. You're going to get a mortgage and you're going to borrow money from a bank. And this could be a heloc. This could be hard money.
This could be.
This could be a first trust deed. You might do seller financing, there's so many. Or get seller financing. All of these strategies have to deal with land. So if you're a real estate investor and you're going to be buying land and want someone to loan you money so you can buy the land or rehab it, you're going to be an option. One that's using land in a land secured note of some sort, even if someone else is signing on the note or doing seller carry back. Number two are credit cards. A lot of people use credit cards to kind of kick their business off and use credit cards on a regular basis in their business, but they keep them under control. They don't let them control them. They don't let the credit card balances get out of out of control and wreak havoc on their lives. You might have a credit line for your business. You might use corporate credit. I have a whole chapter in my book, the Tax and Legal Playbook right here, people. This is the newest version, second edition goes live next week on Amazon. The Tax and Legal Playbook. The game has changed. I have a whole chapter on corporate credit. I have a whole chapter on building your own personal credit. Good stuff. But I'm using a bank to build credit for me or my business. We're not going to talk about that. Number three, you can borrow from your 401k. You can borrow from your 401k at work. If you're a small business owner With a Solo 401k, you can loan to yourself. You can borrow up to 50% or 50k, whichever is less. And you can borrow that money and use it in your business or buy a boat and travel around the world for 50 grand. It wouldn't be much of a boat, but I'd be scared on the ocean. But anyway, you can borrow money from your 401k. We're not going to talk about that. We're not going to talk about this. Number four, you can go down to the bank and get an SBA loan. That's a Small Business Administration guaranteed loan and banks will give you better terms and help fast track you for a business loan if you qualify under the SBA provisions or. I just did a live podcast on this topic about a month ago. I have a podcast called Refresh youh Wealth. Just Go on to Stitcher or your itunes. Refresh youh Wealth. Mark Kohler, Matt Sorensen. We've got over 350 shows in the hopper and one on SBA loans. They're a whole different animal. They have different tracks. How much are you going to borrow? Is there collateral or not? What are you going to use the money for? Not going to talk about that today. Go listen to my podcast now. If you've got a question here, hang tight. I'm going to come to questions on getting money into your business. That's what I the questions I want. Number five. This is where it's at. This, my friends, is the most common of all these. Well, I shouldn't say a lot of people are buying homes with mortgages, probably the most common. But for a standalone business, the most common way people start a business, borrowing from mom, dad, brother, rich uncle, friends, church members, neighbors and third parties. They're going to go out and borrow money from someone to get their business going. Maybe it's a little $3,000 loan, maybe it's a $30,000 loan, maybe it's A $300,000 loan, but you're going to go out and borrow money from someone. What does it look like? How do you do it? That's the next piece of paper here. So now, before I get into the terms of what a normal loan would look like, what I want you to do in this loan and how I want you to approach it. Any questions out there? Nothing. We're good. Man. I hope some of you are watching and loving this, taking notes. Man, we should have talked about how to set up an LLC in Wyoming and everybody be going nuts, but this is so freaking important. Alright? Alone. Now, here's how the loan should look. Actually, let me tell you what it shouldn't look like. A napkin at Denny's. And you'd be shocked. How many times have clients come to me that goes. Well, we wrote up the loan on a napkin at Denny's Waffle House, one of my favorites. Maybe Cracker Barrel. Great places to eat. But not to do your note. Do not do it on a handshake. Do not do it over an email. Do not do it over green eggs and ham. Just get normal loan documents done. So what does it look like? It's one word. I'll send you a free one. If you want to email me and say I need a promissory note, Mark, send you a template and then you. And then you can start working on it. Have one of my attorneys review it. But if you want to email me. I'll put this right out here right now. This is free. If you want, just email mark@markkohler.com just email me and in the subject line say, promissory note. Mark, I'd love your promissory note template. And Maria, she's right here. She'll get an email from you in the next couple days maybe. And we're not going to play this broadcast forever. But as soon as I get that little email, I'll shoot you a promissory note. Now go over it, play with it, write it up, and then have an attorney review it. You're not going to shake hands and do a deal at Denny's and then do your own promissory note and jack it up. You do not want to get in trouble with someone. So a loan starts with a promissory note. And in this promissory note, you're going to hit several points. You're going to hit how much are you borrowing? You'd be shocked how many people screw this up. So how much money are you borrowing? And are you borrowing it in stages? Are you going to get maybe five grand now, five grand later? 50 grand now, 50 grand later. Number two, I want you to lay out the interest rate. What are the, what's the interest rate? And we're usually going to go on an annual term. Is that 5%, 8%, 10%? What is it? How much are you going to pay in interest? And then third, what are the payments? When do you make payments? How do you make payments? Where do you make payments? When, where and how. And you may even have a balloon. You may say, I'm not going to make any payments, but I'll start making payments a year from now. Or I'll pay the whole thing off in five years plus interest. Or I'll pay interest payments now, but no principal, blah, blah, blah, whatever. You agree to write it down, and then this is going to go in your promissory note and they're going to sign it, and you're going to sign it. Now, a lot of times attorneys will say, well, just the debtor needs to sign it. I always think it's good both the debtor and the borrower sign it. I like to have it notarized and then keep it because that is your agreement for this entire loan process. Okay, we got a few questions here. El Toro, what do we got?
Eldoro asked, have you ever heard of a fund and grow? They open a bunch of business credit cards at a 0% interest for a year or more. What's your opinion on it?
Okay, so El Toro says, have I ever heard of Fund and Grow? They open a bunch of 0% credit cards for your business or you, and then over a year, you kind of get your business going. Okay, Fund and Grow falls here. Sorry if that's a little loud on my microphone. Falls here under corporate credit. Fund and Grow is one of many companies out there in the country that say, we're going to build credit for your business. Now, is it legit? Yes. Does it work? Yes. Are there a lot of scams in this area? Yes. And a lot of people make promises that are. They're full of crap, or they make promises and charge way too much and sometimes don't even fulfill those promises. You've got to be really, really careful of who you use for your corporate credit procedure. Now, I'm not going to diss on Fund and May. Fund and Grow and tell them that they're great or they're bad. I'm just going to say always, always get a second and third opinion, not just a second, but a third opinion to your corporate credit process. A lot of these corporate credit companies, they want you to move fast. They want you to move hard. They want you to sign now, or else you're going to lose out. And then you end up paying three grand or five grand or ten grand for this shelf corporation and 1% of all the credit they get me. And pretty soon it cost you five or ten grand to get credit cards that you got to pay back anyway. So be careful how much you're paying for this corporate credit, what promises they're making now. Do I build corporate credit? Yes, I do. Yes, I do. Where? I've got applications, Maria and I. Actually, I'm talking tomorrow about this. We're making applications for corporate credit, whether it's at Home Depot, Verizon, Lowe's. And you start building these terms of credit, and your business can get credit lines. My business has a $25,000 unsecured credit line. I can get that inside my corporation. Sometimes it's 2%, some it's 20%, 5%, 0%. You're going to shop around. But El Toro and everybody listening, do your homework. I have a. I have a whole chapter on corporate credit. I quote to the experts in the country that I trust. If you want to call me and hire us for a half hour, we'll talk about your plan. Make sure you got the right entity and that you don't overdo it and point in the right direction. Great question, El Toro. Okay. Other questions.
What about a new business? How do I secure a loan on my first year?
Okay. Gesina says, how do I get a loan in the first year of my business when I have no history? The banks don't know me, they don't trust me. What am I doing? This is where again, I'm not trying to be too salesy here. I want you to have resources here. In my book eight steps to grow and start your business. Now, I titled it this for a reason. For people that are just starting a business, here's eight steps. For those of you that already have a business, here's eight steps of how to grow your business as well. Now in here, step two is building financials and raising capital. I have an hour and a half workshop. You just hold your phone over this and you could start watching it right now. And then I've got intro to building your financial statements so you can show people what your plans are. First year of operations. What's my fixed cost of my variable costs? You're filling out a table here. You're looking at the difference between investors and partners and lenders. Reality of corporate credit using other people's money. Corporate credit do's and don'ts. These are all podcasts and webinars and videos. It's all included in my little workbook. So Gesina, I would recommend in anybody out there, you can get this on Amazon, 99 bucks. It's freaking awesome. You, you can start watching videos immediately with a download of the PDF version and then we mail you the print version. There are multiple ways to get money for your business. Casino loans from family or friends might be your first option until the banks treat you legitimately and you can build corporate credit. You might borrow from your 401k at work to kind of get your business off the ground. The important thing I want all of you to do is make sure you've got a good strategic plan and marketing plan as to what you're doing. I just met with a young entrepreneur three days ago. She had started a one of these kind of food truck operations, selling sodas and all these different types of drinks. And she was struggling, you know, trying to make, make it work. And we started to get into the costs and the expenses and, you know, losing money making money. And we had to make some hard decisions. You want to make sure that you're making those hard decisions based on projections when you're doing your business plan. And how much money do I need to raise, even just for the first three months, or should I Test my product for a month before I go out and get a big loan. Take baby steps, people. Be careful. Careful. Getting a HELOC on our second mortgage on your home, going out and leaning your personal credit and racking up a credit card for 20 grand to get your business off the ground. So Gesina, do some workbooks. If it's not mine, do someone else's. But go through the process of finding out how much money do I really need to even see if the business is going to make sense? Be very cautious and continue to read and watch a lot of my material. Today's just a brush over the top. Mariette, what's the question there?
She's a fan and she already has all of your books. She asked if I already have all of your books. You recommend we buy new books or do we have access to new chapters? And where can I buy?
Oh, Mariette says Mark, we already have all your books. What do you mean you got a new book? Do I have to buy another one? Can't I get a free version because I bought all your other ones? Mariette. Thank you. You don't know how many nights I stayed up late working hard. The reason why I called this the game has changed is because Donald Trump and the GOP got together in 2017 and change the tax code dramatically. It took me a year of study and classes and carrying around the new code, which was 550 pages to distill it down into some important chapters you've got to read. This book has 30% new content that took me hours upon hours to write. You can get it for 14 bucks on Amazon. It's worth the investment, people. So Maria, I appreciate you asking. I think it's a great question. You never know. I could say oh yeah, for my old clients, they get it for free. But you can win it today. Anybody that wants this book or any of my other books, all you have to do is share this video. In the morning, Rosalie will do a random drawing and give out a copy of each book. So there'll be three winners. So, Marriott, this could be your lucky day. And if you want to get the book, you can get it autographed by me at my website@markjkohler.com you can go to Amazon and they're shipping next week. It's number one pre sell book for two weeks in a row on Amazon right now. So pretty exciting. Entrepreneur magazine, my publisher. Little shout out to Ryan, Shea and Vanessa, my team over there. Love you guys. And so check that out. Last week's Winners. I'm going to just say it right now. Last week's winners, Financial Freedom was Brandy Fisher. And Brandy Fisher Redder. Is that three words there? Three names. They're so important. They have three names. I love it. I'm Mark J. Kohler. So I've got a middle initial. Tax and legal playbook was Josie and Jeanette Rahes. I know them. And Eight Steps, Carlina Alva. And she gets the Eight Steps workbook, which was the big winner. So Carlina, congrats. So those have already been shipped out and Rosalie has already emailed you about it. So, people, I really do have winners. This is live and in the morning, we will give away three winners of the books. Okay, let's see. Should we do another question? Stephanie, what do we got?
This is definitely from your Facebook. Doesn't S corp owner have to do this every time they lend money to their company? I think so.
When they borrow money. Every time.
S corp owner has to do every time they lend money to their company.
Okay, so whenever. Now Stephanie said they're an S corp owner and they're putting money into their business. When you do that, it's not a loan. We call it a capital contribution. Can you bring me my drink too, by the way? Capital contribution. Whenever you put money into your S corp. What I'm talking about is when you go borrow money from other people. And so. Oh, thank you. You can come on the camera here. I had to get my diet due here. Makes the webinar go by even quicker there. Okay, so people, if you're a business owner, when you put your own money into the business, not a loan, it's called a capital contribution. Let your accountant know that in the good old days, some people would loan money to their business. In a C corporation, then they get it paid back tax free. But you're still having tax in the profit on in the S corp. I mean, sorry, in the C Corporation. Be careful with that. C corporations are crazy. I've got videos out on there and watch out. But you're never going to loan to your business. So you're good there. Okay, now I want to go back to this. You're going to have a loan. How much are you borrowing? You're not loaning yourself money. You're just putting money in your business. It's going to go on the books as a capital contribution. Interest rate payments, when, where and how. Now the last one I was saving this for last is the security. Are you going to give anybody a lien against your car, against your business? Are they going to get a lien against your home in a second or third trust deed? I don't know. Now, if you're my client and you're the one borrowing from someone, I usually don't care about that. I don't want you to give a lien against something if we can avoid it. But if you're the one loaning someone money, you always want to get security. Because if they can't pay the loan, I want to call it in. I want to make sure I can go repossess their car, foreclose on their home, or take the stock of their business as collateral. So that's how promissory note works. So everybody in summary, and I'll field a few more questions here if you got it, or else we're going to wrap this up. Borrowing money is okay. Having credit cards is okay. Corporate credit works. SBA loans are okay. All these strategies to go out and borrow money from people or companies, these are okay. Debt is not bad. Dave Ramsey, I love him. He says, get out of debt. Get out of bad debt, which means credit cards and high interest, this and that. I'm all over that. I want you to do a debt snowball and get out of debt. But if you're going to use debt to buy a rental property or debt to start a business or use it in your business, that's okay. Using other people's money to make money, okay. Using debt or credit to buy a new car or travel around the world or pay off a new water heater, not a good idea. We want to try to stay out of debt in our personal lives on consumer products as best we can. But if you're going to borrow from someone, document it, be on it, do it right, and avoid any possible lawsuit. Okay, we're going to wrap up with a few more questions. We got Lady Ty.
I'm looking for an investor in California to work with. I only have 10,000 for our cash down.
Okay, Lady T, you're killing me. Lady T said, and you must have missed the beginning, so you know, it's okay. Recreational marijuana is now, you know, legal in California. Don't be offended. Okay, Lady T, you use the I word. Investor. You're not looking for an investor, you're looking for a partner. She said she's looking to do a deal. She only has $10,000 as a down payment. It sounds like she's going to buy real estate. So, Lady T, you're going to look for a partner in an LLC. And don't freak out about the $800 minimum tax for an LLC in California is okay, because you're going to use it to make 8,000, 80,000, 800,000. You got to have an LLC. So don't try to cut corners and get around it. You're going to get in trouble. So you're going to go out and get a partner. So, lady T, be careful. Don't use the investor word. Say, I'm looking for a partner to partner with me on this deal. Now if you say, well, I'm not going to give them any profit in the deal. I just want to pay him interest, then you're looking for a lender. The first thing you can do, lady T, and this is for everybody listening, is use the right language when you're out trying to raise money, because people with money can see through your inexperience if you use the wrong language. So if you show up at a workshop or a networking group and go, hey, I'm looking for a lender on this real estate deal. I'm going to give them a second trust deed. I'm going to pay him 10%, 2 points, okay? They know what they're saying, hey, everybody, I'm looking for an investor. I'm doing a real estate deal. Anybody that has money knows you shouldn't be using the word investor. So get your terminology down, understand what you're asking for, and have the documents ready to go so you look legit. There you go, Lady T. Okay, Michael,
can you collateralize your personal assets with equity to fund a small business building?
Okay, so Michael says, can you use collateral to help get a note with someone, fund your business, and then he throws out heloc. Okay, I'm going to break that into two pieces. So first, Michael, if you need to go out and borrow 5, 10, 20, $15,000, you might have some equity on a paid off car. You might have a snowmobile, you might have a boat that's paid for. That's what we normally call collateral. You're going to use personal property collateral that you're going to pay that note back, and then you're going to go find someone that's going to loan you money and you're going to fill out a promissory note and you're going to give them a lien against your car title, your boat title, your snowmobiles, your jet skis. That's collateral. Now when you say heloc, now you're talking about land, you're talking about equity in your home. That's collateral. But it's a different type of collateral. It's called real property. So when you talk collateral, that's a big word. It might meet personal property. It might mean real estate. HELOC is a type of loan. When you use real estate as collateral, you could use seller financing. You could use a first mortgage, a second mortgage. You could use hard money. You could use the heloc. HELOC is a flavor of ice cream when you're using land as collateral. So I hope that helps. Michael, you could think big and use equity in your home to start a business and write off the interest on it as you pay it back. Any other questions? Okay, we're good everybody. Thank you for watching, listening. Hopefully this was helpful. Probably not going to be one of my most viewed broadcasts because people just don't think it's that sexy to talk about borrowing money. But a few notes. Please subscribe to my YouTube channel if you're someone shared this with you. If you ever need anything, give us a quick email. You can go to markjkohler.com or kqslawyers.com I've got our summit on self directed IRAs in Hawaii on August 10th. For any of you in the islands, it's easy. We're over on the North Shore in Kaneohe. Come on over and you can get to my website to get to a link to that. And I've got my five workshops in the fall. I've got Philadelphia, Chicago, Orange County, Seattle, Seattle and Hawaii. The last one is a live broadcast in Hawaii and The ticket is 99 bucks. Six hours of content with me for 99 bucks. You get a workbook, you can ask live questions and you get a recording of the workshop no matter which one you go to. So anyway, guys, check those out. Check out my weekly newsletter, the Social Media. I'm here for you. And next Thursday I'll be here with another topic. If there's a topic you want me to cover, just email Rosalie at MarkJ. Kohler or KKOS. Okay Rosalie Kos lawyers.com or email me mark@markjkohler and say here's the topic I want and I'll be there for you. Thanks everybody.
More from MARK




The secret to managing your family's future #financialfreedom #estateplanning #shorts



Moving Property to an LLC: What They Don't Tell You #realestate #investing #tips


