The Truth About S-Corps: How To ACTUALLY Pay Yourself
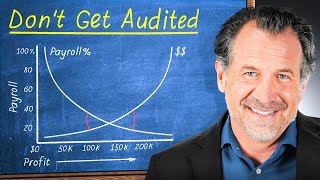
Mark Kohler, a CPA and attorney, walks through his payroll matrix for S-corps: how to split profit between W-2 salary and K-1 distributions. He uses $50k, $100k, and $150k profit examples to show potential payroll tax savings, then explains quarterly payroll and year-end adjustments.
Chapters
Welcome back, everybody. My name is Mark Kohler and we're here to talk about payroll for your S Corporation. How much should it be? How do I do it? Why am I doing this? Folks, I'm going to answer all those questions and more now. I am a licensed certified public accountant, attorney, best selling author, and owner of multiple tax and legal businesses. And I have been teaching this content for over 20 years to business owners all over the country. You're in the right place. Now, have you been confused of how much payroll you should take in your S Corporation? It can be because you talk to one advisor, they say one thing, you talk to your lawyer, they say another, you talk to your friend and they're doing something completely different. It can be very confusing and it can make us nervous because we're like, man, I don't want to get audited for taking too little salary, but I don't want to take too much and pay more in tax. Well, stress no longer. Today you're going to get the answer on how to best choose the proper payroll for your S Corporation. I have developed what's called the Kohler payroll Matrix. Taking the country by storm. Super exciting. And what it does is it gives you a rule of thumb of what your payroll should be based on the the profit you take out of your business. Okay, so let's go to the whiteboard and if you've watched any of my videos before, you're going to be familiar with the trifecta because it puts it in perspective of all of your other business entities and operations. In the trifecta, the foundation is your revocable living trust. It's also kind of where I'd like all your money to go, called your 1040 tax return. We're then going to split your life in half. And over here we're going to have operations and assets. Now over here is where you might have an LLC that owns your rental properties. That's great. And it's going to be owned by your trust. Trust owns your llc. LLC owns the rentals. And you're going to have your own checkbook over here for that type of stuff. Passive income. Passive. We are never going to put an S Corporation over here. On this side we might have an LLC that we graduate and transition to an S Corp. I have another video on when, where, why, and how to use an S Corporation. It'll be down in the description. Please go back and watch it if you, if you haven't already done so. But in this S Corp is where we're going to peg our W2 or this salary and then all the rest of the profit comes down here into our 1040. And our s corp is owned also by our trust. This is the trifecta. An S corp, an LLC split in half owned by my trust that is the foundation of every wealthy client I have and how they build more and more wealth, Boom. But a bank. Now in the S corp you're going to have gross revenue or sales, you're going to have expenses and then you're going to have your profit. Okay, so let's put some numbers to this. This. Let's say you're going to make 150 grand in sales and I'll use some numbers greater and smaller than this in a moment. And you have 50 grand in expenses, your profit would be a hundred thousand dollars. Again, some of you may already remember if you take that 100 grand and run it through just a plain old LLC or sole proprietorship, you're going to pay 15 grand in self employment tax. If you're not an S corp, we don't want to do that. We want to take salary of a certain amount and then let everything else push through on a K1, that's the profit. So you're going to get a W2 and a K1. Well how much should the salary be? Right, that's the quandary. Now to answer that question we have to look at what is your profit? And I want to take a percentage of that profit and allocate it to salary. Now let's digress for a moment. There's a lot of advisors out there that are probably already in your ear or if you've searched out on the web that are going to say reasonable comp is based on, you know exactly what you're doing compared to someone else across town. And are you old or young? How much is your profit based on how much you work in the business? And what would it cost to replace you somewhere all of a sudden it's all these factors. In fact, I want to even sell you software so that you can put all these variables in to figure out this mysterious number of your salary people. I do not adhere to that approach. I think you can use a simple rule of thumb that gives you an allocation of salary that keeps you out of harm's way with the irs. In fact, let me just tell you something. In over 25 years of practice and doing thousands of S corporations, we have never had a client audited for taking too little of salary ever. And trust me, I read every case on reasonable comp I've gone to every class on reasonable comp. I read every possible statute and rule on reasonable comp, and then I bring it to you in an easy to understand format. I don't want to make it sound mysterious. I don't want you to feel like you're searching down the wizard of Oz for some crazy way to figure this out. We're going to do it right now. We're going to look at the matrix. Now with the Kohler payroll matrix, as I said, we're going to be looking at profit. And to be more specific, it's actually draws. How much money you taking out of the business? That's what really matters. So I'll just call it profit for now. Going to assume you're going to pull out all the profit out of your business. Now, as I said, the magic of the payroll matrix is coming up with a percentage to allocate to payroll. So down here on the bottom line, we are going to put your profit. How much did you make? And I'm going to assume how much you took out of your business. For you experts out there, we're going to really be focused on draws. And I teach that in my Main Street Certified Tax Pro program where I'm teaching tax advisors how to really zero in on this. But we can call it profit for now to just make sense of it. So here would be a $0, maybe it's 50 grand, 100 grand, 150 grand, 200 grand. Now this is again profit, and it's going to keep going and going. So as you make more money, that's this line. All right? Now on this axis is going to be the percentage of payroll. Where do we want to be? Well, it might start out here at zero. It could go up to 20 or 30 or 40% or 50, 60, 70, all the way up to 100% in payroll, which is what we don't want. So if we play this out, as you start making more money, your payroll is actually going to go down as a percentage of your overall income. So as your money goes up, your payroll actually goes down as a percentage of your income. Isn't that weird? It sounds kind of counterintuitive. You think it's, I make more money, my payroll goes up? Well, your payroll go up as a dollar amount, but the actual percentage goes down. Now where do most people fall? Well, right, kind of here. So at 100 grand of profit, my payroll might be 40%. If I'm going to make 50 grand in profit, my payroll might be 50%. So that means back to an example on our kind of picture of how our S corp plays out. If I'm going to have 100,000 in profit, I might make a $40,000 payroll. So my profit becomes 60 grand. So I've got a 40, 60 split and I just saved 15% on 60,000. I saved $9,000 by doing a 6040 split. If I didn't even do an S corp, oh my gosh, my self employment tax would be over 15 grand. Now my payroll tax is only 6 grand. What? This is the savings. So by choosing the right amount of payroll, I create savings. Now let's say my S corp, if we go back to the metrics, right, if I have 50 grand in profit, maybe my payroll should be 50%. See, because you're making less, you want to stay out of harm's way with the irs, you're going to take a little more payroll as a percentage. So we go back to our S corp and let's say I bring in 100 grand, I have 50 grand in expenses and then I net 50, I might take payroll of 25. So there's my W2 and my K1 or profit is 25. Now in this example, I saved 3200 and self employment tax, wow. Now you may say, well that's not a lot, but it's a start because the more money you make, the more you save. Now in my prior video I talked about the S corp costing you from a cost benefit analysis, maybe around $2,000 a year. You got to do a tax return, you got to do payroll. So in this example, if I'm making $50,000 a year profit and I do a payroll of 25, I saved 3200, so it cost me two grand to save 32. So I'm up 1200 bucks. Oh, but I make 100 grand. Now I'm up $9000, right? So this really starts to go and that's what we want to be doing is really playing that S corp. As my profit goes up, I have clients that make 3, 400 grand a year. We might flatline their payroll at 100, 120, maybe a 15, 20% allocation. Now I want to remind you this is not high risk and it doesn't have to be complicated. But I do want you to know enough to have an intelligent conversation with your tax advisor. You don't want to leave it to them to dec your risk tolerance because I'll tell you, a lot of accounts are like, oh my gosh, you got to take more payroll because you know you're going to get audited. No, you're not, man. I was teaching a workshop three weeks ago and this couple that had a little real estate business, they were flipping properties, she was a realtor as well. They're probably going to make about 250 grand that year. I taught the S Corp concept and she goes, yeah, my accountant said I wasn't making enough because I had to take too much salary. It wasn't worth it. I said, hold it. You're making over 200 grand a year. You could have a payroll allocation of maybe 70, 80. You'd be saving over $15,000 and change. It was emotional. It was emotional for me because I knew they were getting bad advice and they were afraid to have the conversation with their advisor. People, you have got to be in this conversation. I want you to sit down with your tax advisor and say, hey, what is my payroll allocation? I'd like to look at this kind of matrix concept that Mark Kohler teaches. He's got a best selling book called the Tax and Legal Playbook. He's actually a CPA and an attorney and has been teaching this for years. Can we just look at that? And maybe we could take a more aggressive approach or maybe more reasonable approach. But if your accountant doesn't want to have that conversation, then you've got to captain your ship and get the heck out of there. Now, I've got down below in the description a network of certified advisors all over the country that speak Mark Kohler. I don't want you to feel alone here because this can be a little daunting. So you want to have an advisor that understands this and they understand you. That's how you solve this problem. I'm not saying you go out and start doing your own payroll. You have a conversation with your advisor, say, you know what? I'm not comfortable with what we're doing. I'd like to change the equation. And either they're on board or they're thrown off board. You're going to take control of your own ship, people. You're the captain. So that is the process of payroll. It's looking at your profit, finding a reasonable allocation, and having a conversation with your advisor. You're going to do quarterly payroll reports to choose that amount. A lot of times in the fourth quarter of the year, you kind of chew it up. You kind of find out, well, here's my real profit for the year. Because we don't know. I'm not telling you. You fix your payroll at the beginning of the year, you're looking in the rearview mirror at end of each quarter and at the end of the year, you true it up, you get the right number. Alright? Now in summary, I want to assure you you are on the right path. Every dentist, doctor, engineer, landscaper, realtor, accountant, plumber, online influencer, seller on ebay, Etsy, Turo owners, Uber drivers. If they're making more than 50 grand and they're a client of mine, they're going to be an S Corporation. And again, I've never had a client audited for taking too little in payroll. Make sure you have a conversation with your accountant about this. It's a wonderful way to save money and build wealth. And it's just the beginning to unlocking the secrets of the S Corporation. Now, down below, there's a plethora of information that I've provided for you, some additional links to Videos, resources, our law firm and our network of accounts around the country. Please check it out. I've got more videos on this topic and others. My podcast I'm not going anywhere people. I'm here with you. Main Street America is where it's at and entrepreneurism is alive and well. You can do this. Don't give up.
More from MARK




The secret to managing your family's future #financialfreedom #estateplanning #shorts



Moving Property to an LLC: What They Don't Tell You #realestate #investing #tips


