The Wealth Operating System Most Investors Are Missing
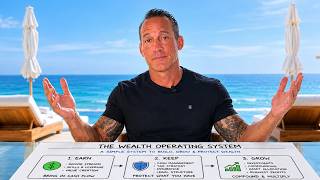
Mark Moss breaks wealth creation into three variables: capital, time, and yield. He explains the Rule of 72, how compounding works, and why a vertical multi-asset approach can generate 20-40% returns. The key is setting a clear goal, knowing your starting point, then pulling the right levers based on your age and risk tolerance.
Chapters
One of the biggest misconceptions when it comes to building wealth is that complexity drives better outcomes. If I could just find the secret, I could get the outcome that I want. But the reality is different. The reality is that most financial outcomes are driven by just 3 variables. That's it. 3 levers: capital, time, and yield. And that works out to how much capital can be deployed, how long can I allow that capital to compound for, and at what yield is it compounding at? Every investment strategy, every portfolio, everything that you're doing to try to achieve your goal is built off of the combination of those 3 levers. The problems are twofold. One, most people don't know where they're trying to go. And number 2, they don't know which lever they should be pulling in order to reach that goal in time. So they overoptimize for yield without realizing the value of time, or they fail to realize how much lazy dormant capital they have and how that can be activated. So today we're going to fix that. I'm going to walk you through all 3 levers. I'm going to show you how you can use each one specifically help you achieve your ideal goal in the fastest amount of time possible using this. You ready? Let's go. All right, now I don't want to spend too much time on this part, but I have to talk about this because I want to talk about the 3 levers to help you achieve your goal. But how do you achieve a goal that you don't know what it is? So it all starts with trying to figure out exactly where I'm trying to go. And it has to be specific. When you set a goal, it needs to be SMART. S-M-A-R-T. Google that. Figure out how— maybe we can link it down below. You'll figure out what that is. A SMART goal. Specific, measurable, actionable, right? So how much do I need and by when? Not like more money. Not like, I don't know, $1 million. No, no, no, no. How much income do I need exactly? Like $4,769, $14,700. Like, how much do I need specifically every month and by when? I want to replace my income. Okay. How much is your income? When do you want to replace it by? Your mind works off of specificity, not generalities. Just like a GPS. If you open up Google Maps, you would first put in where you want to go. And you don't say, take me somewhere cool. You don't say, take me to some beach. No, you put in a very specific GPS coordinate. Then once you put that in, Google asks you the next question, which is, well, where are you? Which again has to be specific, a specific GPS coordinate. So once you figure out where I want to go, this much revenue per month by this time, the next question then is, where am I at? How much assets do I have? What's my total assets that I have? The value of those assets, the equity of those assets, and how much income do I have? Once I know those two things, then we can use the three levers which again is time, yield, and capital to achieve our goal. So start there, understand where you're going and where you're starting from, and then let's dig into the 3 levers. Okay, let's go through these 3 levers because you need to know how to use each one of them. And let's start with the first one, which is time. A lot of people don't think about time when it comes to money, but of course they've all heard the saying that time is money, money is time. It all comes down to time. As a matter of fact, in one of my coaching programs just this last week, someone was asking me, well, I could get credit from these 2 sources, but this is what the yield is on each one of these. Which one should I choose? And I said, well, typically I would choose the lower yield, but what I want to optimize for more is the time. You didn't tell me the time. What is the time duration of the loan? Is one marked to market on a daily basis and is due in a year? Is one of them against a home and it's a 30-year fixed for 30 years with no mark to market or liquidation risk? So we want to focus on the time. So what do I mean by this? Your money is doubling as it compounds, right? Compounding is it compounds on top of the compound on top of the compound. Now we use something called a rule of 72. The rule of 72 says that I take the yield, 10% return on my asset, divided by 72 72, and it tells me how long it takes for my money to double. So if I'm making a 10% return on my money divided by 72, that means every 7.2 years my money doubles. So right off the bat, it's time. So I have $1 million, I want to have $5 million. What is my yield? 10%. Well, how much time do I have? Well, if it compounds at 10%, then I'll reach my goal. I have enough time. Great. I don't need to do anything. But let's just say that, well, I'm not going to achieve my goal based off of that rule. I'm going to achieve it in 12 years, but I want to achieve it in 7 years. Okay, then we have to pull another lever. What other lever do we have? Well, I need to increase the yield that I have. So instead of 10% yield, what happens if I get a 20% yield? Well, 20 divided by 72 is about 3.5, 3.6. That means that every 3.5 years my money doubles. So I've cut that in half. So now that means a million goes to 2, goes to 4, goes to 8, goes to 12. 3.5 years. Each clip. So now can I achieve my goal? Yeah, I can. Perfect. Then I need to engineer a 20% return. The risk that most people take here is they think in order to get a higher yield, to go from 10% to 20% yield, I have to go way out under the risk curve. So now I have to buy something that's going to go up 30, 40, 50, 100%. I got to get into venture capital, private equity. I got to buy meme stocks like GameStop, or I have to get in some crypto pumping up token or something like that. And so they're all over Reddit and message boards and they're on Twitter and YouTube trying to find the next hot stock tip, insane amount of risk and the things they don't even know about, try to increase that return because they realize they're behind. Now, a better way to do this is a wealth operating system way where we engineer the return that we need using traditional assets that we know and have edge against. So we, instead of investing horizontally like most people do using asset allocation, we invest vertically, getting each dollar to compound multiple assets at the same time. By doing something like that, we can take traditional assets, real estate, NASDAQ, things like that, and generate a 20, 30%, 40% return. If you want a whole video where I break down that entire system, I'll put a link to it down below where you can watch that in more detail. But you understand, we do need to increase the yield that we're generating if we need to compress the amount of time. And then finally, we move on to the third lever that you can pull, which is capital. So now let's say that we have gone through the time and like, shoot, I don't have 20 years. I need it done in 5. And in order to get that done in 5, I've tried to increase the yield, but like realistically getting above 20%, 30%, 40% takes an enormous amount of risk, and I don't know if I'm okay with that much risk. Well, then the third lever you have is capital. So you have to put more money in. Are you still working? Can you generate more capital, more gasoline to dump in the engine? So if I can increase the amount of capital that I need, I can take on lower yield and I can compress the time. Now, if you're 78 and you can't work anymore, that may not be an option, which in that case, maybe you have to either take on more risk to get a higher yield or you have to increase your time. If you're younger, maybe you can still add— go back to work and you can add more capital to that. But those are the 3 levers that you have. It's math, physics. Like I can go on to Google Maps, back to that example, and I could see what my routes are to get to my destination on the time that they've allotted for me. At the end of the day, there's reality. So if I wanted to get to London for dinner, well, it's not physically possible without some Star Trek teleportation machine. Like it's not going to happen. So you do have to be realistic, but you know the 3 levers that you can pull now. You can wait longer time and allow compounding to work. 2, you can increase the yield that you're generating. If you can shorten the compounding time from 7 years to 3 years, or you could add more capital into the machine, more gas under the fire, so you can shorten both of those at the same time. Now you have 3 levers, but how do you know which one you should pull first? Well, it's not about first, second, or third. You could pull all of them at the same time. So first of all, if you're still working, keep working, keep putting more capital in the machine. If you can increase the amount of capital you earn, great. If you can decrease the amount you spend, great. Continue to try to add to that faster. Number 2, the time. You can't really change the time. I guess you could change your time preference. Do you need to retire in 5 years? Could you wait 6 or 7 years? And then finally is the yield. Now, the yield really comes down to engineering the yield that I need. Now, the truth is, anytime I'm sitting outside of dollars, there's risk. And actually, sitting in dollars, there's risk too. I'm guaranteed to lose to debasement. So there's risk in everything that we do. But the question is, how much time, effort, energy do I want to put into this? How hard do I want to work at this? And then how much risk do I need to take in order to get to the goal that I need by the time I need it? So what I want to do is only push as hard as I need to push. I don't need to push harder. The goal is not more. The goal is how do I get to my desired goal at the timeframe that I've allotted for or I've desired to achieve it by? And how hard do I need to push or work to achieve that? So I use a combination of the three. If I can put more capital in, put more capital in. If I can't, I expand my time. If I can't expand my time, I need to get more yield. But I can only push so much. And at some point, maybe you need to readjust your goals. But of course, I don't want anybody to readjust their goals. I don't want anybody to settle in life. I want everybody to achieve the life of your goals and your dreams. And so if you want to learn how to build an entire wealth operating system, three wealth engines working together to build a wealth flywheel that builds wealth faster and faster and faster forever, you might want to watch this video right here where I break the entire system down. You can follow along right here, and I'll see you over there.










