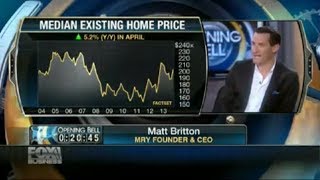Televised panel (Fox Business, June 23, 2014) featuring Jeff Taylor (Digital Risk) and Matt Britton (ad firm founder/CEO) discussing the US housing market, lending standards, regional variations in recovery, consumer sentiment about jobs, and potential short-term impacts on the stock market. Economists expected existing home sales just above 4.7 million for May; year-over-year sales were reported down ~4.5%. Panelists note banks remain conservative in lending (loans mostly to near-perfect borrowers), argue there is room for lenders to make loans to borrowers with ~650+ FICO scores, and describe a split between hot coastal markets (high demand, cash buyers) and weaker middle-America markets. The Dow recently closed at 16,947 and panelists speculate housing data could push it toward 17,000 in the short term.
Questions this video answers
Just above 4.7 million (annualized).
About 4.5% down year-over-year.
Borrowers with roughly 650 FICO score and higher.
16,947.
Approximately 62% cash buyers.
You also that housing data out at 10 o' clock this morning that could be a catalyst for either an up or down action in the stock market. We'll have that all for you. Thanks to Nicole and Katie Martin. We're less than an hour away from getting the latest read on the health of the US housing market. Existing home sales out at 10am Economists are expecting the number to come in just above 4.7 million for the month of May. With more I want to bring in my contributors for the hour. Jeff Taylor is a managing partner at Digital Risk, the largest mortgage processor in the US And Matt Britton, founder and CEO of ad firm Mr. Why gentlemen, welcome to both of you. You know Jeff, I want to start out with you first. You look at these numbers extremely closely. There has been a lot of concern that the housing market really hasn't seen the recovery that a lot of economists had predicted and many had hoped for. What are you expecting this morning?
You know, it's true. I think even the numbers are a little bit up. We have to look year over year and we're still down 4.5% from last year to this year. And the big thing is banks right now still have not come back into the housing market in a way we all thought they would. They're making loans to people who sort of had that perfect profile. But good borrowers, we're not talking subprime good borrowers, good FICO scores, people can afford those most monthly payments still aren't buying houses. On the consumer side, we're also still not seeing historically low interest rates are not taking advantage of these interest rates, locking in those houses and moving.
So Jeff, are you saying that we should ease up on the lending standards? That what caused this problem in the first place?
No, what caused this problem in the first place was irrational lending. Lending. It never should have taken place. But not everybody in the world has to have a 750 FICO score and be perfect to actually get a mortgage. There are good fundamental loans to be made at people between 650 FICO score and higher and have the money to afford the house. Affordability is a huge key.
Affordability is, is key. And, and Matt, when you look at the way Americans are feeling right now when they're pulled on the economy, they're pulled on the job situation. The latest Fox News poll show that 48% of Americans think that the job situation is getting worse in this country. That translates to hesitation to buy a home. That's why we're seeing rents are up, people are renting More than they're buying right now?
Well, I mean, the term Americans is a monolithic statement. I think the fact is that we have in essence two different nations going on right now. We have the coast where a lot of innovation is happening, where the economy is red hot, where there's a lot of jobs in the technology and media and finance sectors. And then you have other areas of the country which are very heavily manufacturing driven, where there's a lot more uncertainty. So I think you see that in the real estate market. There's certain markets that are incredibly hot and there's others that are really where the consumers are feeling the pressure.
Well, it's a great point. You know, can we really talk about the US Housing market as a whole when it's really driven by specific regions in the US that have recovered quite well and some that have held back. I bring up Texas, for example. Austin has seen this huge boom in technology and it's, it's nearly impossible to buy a home there right now because the supply has dwindled, literally. Real estate, real estate agents have been calling people up in their homes, asking them if they're willing to sell. So it's very specific to where we're talking about in the country right now.
Yeah, like we're about to set, I mean all honestly where people go, where the jobs are. So and often you have the tech sector that's booming down there. So literally jobs are going there, people are trying to buy houses. You've had huge appreciation areas like San Francisco, Irvine, Miami, literally most of these cows, these houses are cash buyers, 62%. But middle America right now, it's still a very tight inventory and we're still not seeing that kind of recovery nationally that we need for a healthy economy.
All right, so I was just telling Nicole, looking at the dow closed at 16, 947 on Friday. We've got this housing number coming out in 50 minutes from now. Do you think that that will be a catalyst for this market to top set for the dow to top 17,000?
So I've always said, you know, stock market is nothing but a public opinion poll on any given day. So yes. Could it pop it over 17,000? Is that long term sustainability? I'm not sure, but get it there.
I think it will get there. I think I'll get there this week, if not today.
All right, sounds like a lot of optimism on this desk right now. Mad Jeff. Don't go anywhere, stick around. We are now about 20 minutes away from the open.