The BIG Mistake People Make Choosing Between ISA and SIPP
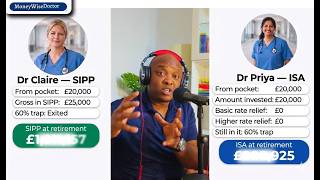
Dr. Andy Egwim shows UK doctors why funding a SIPP before an ISA can save thousands in taxes. Maxing out an ISA first wastes tax relief for higher earners. Two fictional doctors illustrate how the order you fund these accounts dramatically changes your retirement wealth.
Chapters
If you're a higher rate taxpayer investing in an ISA, you might be making a mistake that will end up costing you several thousands of pounds, if not tens of thousands of pounds. Now I know how that sounds, and wait, wait a minute, I'll explain that to you with numbers. The new tax year literally just started, and I've already seen some doctors in our Moneywise Doctor community who have maxed out their ISAs on day one, which on the surface sounds like a great plan. Time in the market beats timing the market. Act fast, no delays, money working from day one. But does that mean that maxing your ISAs is the best first step for you to take? Now I know in the UK, saying anything against the ISAs feels a little bit like financial blasphemy. How dare you? The ISA is sacred. Your favorite finance YouTuber talks about it all the time, and that finance TikToker you follow practically dances to it. And that colleague in your work WhatsApp group, you know, the one that never ever shuts up about ISAs. The one who sends a reminder every February that the tax year is ending and you need to use your allowance. Yeah, the one who makes you feel vaguely guilty every April if you've not used your ISA allowance. You can't escape ISAs. ISAs are like, oh yeah, everyone thinks ISAs are the, you know, after sliced bread, the next best thing. But is maxing your ISAs actually the right first move for you? And look, before I tell you the numbers, because I've run the numbers, before I say anything, I want I want to be clear, I have nothing against the ISAs. I use an ISA, I recommend ISAs. I mean, for tax-free, um, I have made videos explaining the ISAs. The ISA is genuinely one of the most powerful investing tools available to UK taxpayers. And with the rise, with the current rise in dividend tax in this new tax year 2026/27, the ISA even matters more. Both if you're a higher-rate taxpayer, and especially if you're earning between £100k and £125,140. Rushing to fund your ISA before you've thought about your personal pension might be costing you several thousands of pounds, possibly tens of thousands every single year. Now, it's not because the ISAs are bad, we already established that, but it's because of the sequence, okay? Which comes first? And whether you've ever asked yourself, what would putting money into my personal pension do for my tax position? Before you click that ISA button? Now, because for many higher-rate taxpayers, the answer to that question, it changes everything. And that's exactly what we are unpacking in this video. So sit tight and relax. We're going to run a bit of numbers, but to be all clear. Now today I'm going to walk you through Stock and Shares ISA versus SIP. So Stock and Shares ISA versus SIP, Self-Invested Personal Pension. I'm going to show you the approach which I've taught inside the Moneywise Doctor Masterclass. I'll walk you through the real tax impact with actual numbers and show you examples, scenarios of two doctors making different decisions with the same money and where each of them ends up. Now, this video assumes you have a basic understanding of what ISA and a SIP actually are. If you are not clear on how ISAs work, I have a dedicated video on this channel that covers it fully. Link is in the description. And if you want to understand SIPs, what they are, who they are for, and how they work, I've also covered that too in detail. Just check the link in the description or drop the word ISA or SIP in the comments and we'll share the link directly with you. Now today we're not starting from the basics. Today we are going a little bit deeper because by the end of the video you will have a clear framework for which one to fund first and how much and why. Of course, you can afford to fund both of them, that's happy days, but where should you start from? Before we go any further, drop your answer in the comments right now before you hear a single number from me, from my own analysis. ISA, first or pension first? ISA first or pension first? Tell me in the comments. What are you currently doing and why? I'm coming back to this question at the end. Let us see how many of you feel exactly the same way after we've gone through the numbers together. And then I want to know how many of you have completely changed your mind as well. Now, before we go any further, if you're new here and we've never met, I'm Dr. Andy Egwim. I'm the founder of The Moneywise Doctor. I'm the founder of moneywisedoctor.com. I'm the author of The Moneywise Doctor, the book. I'm an Amazon bestseller on investing, personal finance, retirement, planning and money management. So it launched last year. I'm a former NHS-salaried GP. I've been an investor for over 20 years, and during that time I was fortunate to achieve financial independence and left my 9-to-5 behind 4 years ago. Moneywise Doctor has helped thousands of doctors make smarter financial decisions and avoid costly mistakes that quietly destroy doctors' financial future, even when they're on a high income. Now, quick disclaimer before I go any further: I'm not a financial advisor. Everything I share here is financial education designed to help you think more clearly, not to tell you what to do. I know that individual circumstances vary, rules can change. Please speak to a qualified FCA-regulated advisor if you need specific advice before making significant changes in your pension and investing. And of course, if you're not subscribed, please just do it. Hit the bell. There's a lot more coming. Okay, take a second, hit the bell. Fantastic. So that you can see when I release new stuff. Now let's dive into it. So before you make any investment decision, this starts here. Start by understanding exactly where you currently stand. Most doctors have never had a proper financial health check, not because they're not interested, but because nobody had ever, you know, designed a tool that helps to make sense for the specific complexity of doctor's financial life. So I made one. It's called the MedScan Financial Health Score. So it takes about 3 minutes. It helps you to look at your overall financial position across 7 key areas including tax efficiency, pension, investing, debt management, and financial protection. It gives you a clear score, a breakdown of exactly where you are, where the gaps are, and it's completely free. Takes 3 minutes. So if you head over to moneywise doctor.com/medscan, or you can check the link in the description to get it. It's 3 minutes, real clarity, free. The most important concept in this video is tax-efficient investing. Not just investing, but tax-efficient investing. When you invest money, any money at all, in any vehicle, there are 3 moments when tax can touch it. Stage 1, putting the money in. Stage 2, while it grows. And Stage 3, taking the money out. Obviously, more tax, less return. Most people only think about Stage 3. They say the ISA is tax-free on the way out, the pension is taxed when you draw it, therefore ISAs are better. Is it? And this is where many people miss it without even checking. Stage 3 is only part of the story. Ignoring Stage 1 is exactly where the costly mistakes are made. Let me walk you through all the 3 stages with both vehicles, ISAs versus SIP. With a stock and shares ISA, Stage 1, you earn money but tax is taken first, PAYE, 20%, 40%, or 45% via PAYE or self-assessment. You then invest what is left. Stage 2, everything inside the ISA grows completely tax-free. No income tax, no dividend, no capital gains tax on growth. Stage 3, you withdraw, no tax ever, whatever amount, irrespective of how much you take in a single year. Completely clean, straightforward. 3 stages for ISA: tax going in, grows free, comes out free. With a personal SIP, with a personal pension or SIP, stage 1, you invest first, and then the government adds tax relief on top. This is the critical difference. The pension starts bigger because HMRC contributes money before you have even taken any market risk. Stage 2, everything inside the SIP grows completely tax-free. No capital gains tax, no dividend tax, exactly the same as the ISA. Now, Stage 3, you withdraw. 25% of the entire pot comes out tax-free. The remaining 75% is taxed as income at whatever rate you pay in retirement, which is often significantly lower. Than what you pay while actively working, 40% and above. Um, yeah, I'm running a free masterclass. Basically, we're going to look at investing, look at SIPPs, ISAs, NHS pension, how to combine them. It's going to be a free investing masterclass for doctors. Now, over 1,800 doctors have already attended previous masterclasses, and we've had hundreds of testimonials. If you want to attend, you want a free ticket, I've got one for you. If you check the link in the description, you can click to get a free ticket to attend my next free investing masterclass. It's 90 minutes. We're going to learn what medical school didn't teach us and what many doctors have spent so many years trying to figure out. If you head over to moneywisedoctor.com/masterclass, you can grab a ticket there or check the link in the description. To get one. Now, 3 stages for SIP: invest it, you get the government top-up, it grows free, and then partially taxed on the way out. Now, when people hear partially taxed on withdrawal, that's where most people stop thinking about it even to understand and just think, oh, ISAs are the best. But that's where you miss something critical. The pension started bigger. You cannot compare £80 growing tax-free with £100 growing tax-free and then only look at the tax at the end. That's not a complete comparison. It's like comparing 2 runners in a race, 200-meter race, but you started one of them 100 meters ahead, and then at the end you judge who ran faster purely based on who finished first. That's misleading calculation. Let me show you what this looks like with real numbers. Let's look at these 3 scenarios. Watch what happens at stage 1 before a single penny of growth rate has even occurred. So a basic rate taxpayer, 20%, you earn £100, and after 20% tax you have £80. You put that £80 into your ISA, you have £80 working for you inside the market. Put that same £80 into a SIP, HMRC automatically adds 20% basic rate tax relief. You now have £100 in your pension, more money compounding in the market from day one. Same effort, same person, maybe same starting salary. £80 in the ISA, £100 in the SIP, both growing completely tax-free. Now let's look at scenario 2, higher rate taxpayer, 40% tax. You earn £100 After 40% tax, you have £60. You put £60 into an ISA, £60 is working for you. Now, but if you put the same £60 into a SIP, HMRC automatically adds 20% of the basic rate relief. So that will be 20%, that's basically 25% net, £15, brings it up to £75. You then claim an additional 20% higher rate tax relief via self-assessment, that's another £15. Basically, your £60 is now £90. So your gross amount inside the pension is £75, but you've got another £15 coming, so £90. So if you look at it, it's £60 in the ISA, but you've got £90 in the SIP. Basically, if you put back the same 20% you've claimed through Self Assessment. So let that sink in for a moment, right? So Scenario 3, the 60% tax trap. So if you're earning between £100K and £125K, £140K, This is where things become extraordinary, and this is the scenario that quietly affects a significant number of doctors—consultants, GPs, doctors with additional locum or private income. In this income band, the effective marginal rate is 60%. Not 40%, not 45%, 60%. Now, this happens because for every £2 you earn above £100k, you lose £1 of your personal allowance. Now, if you combine it with the 40% income tax, the effective marginal rate on that income becomes 60%. So you earn £100, and after the effective 60% tax, you keep £40. If you take that £40 and put it in an ISA, £40 is now working for you, compounding, invested. Okay, not bad. Now, if you put the same £40 into a SIP, 3 interesting things happen. One, the contribution reduces your adjusted net income, which could help you escape the 60% tax trap. 2, automatically you get 20% of the initial gross up into your SIP, so HMRC refunds you. Now 3, you claim another 20% via your self-assessment. Doing this correctly could restore your personal allowance, which basically, when you account for the tax relief benefits, you're getting 60% uplift again. So for someone in 60% tax trap, this is what the picture looks like: £40 in the ISA, it's £40 working for you. But in the SIP, you effectively— the £40 could actually be grossed up all the way to £100 when you claim all the tax relief and also getting back your tax-free allowance. Same income, different decisions, different outcomes. And this is even before any investment risk has been factored in. And what we have not even talked about is how— what restoring that personal allowance, what it does to the rest of your tax bill. Does SIP always win? No. And I'll be— let's be completely honest about when it does not. But I need you to see stage 1 clearly first, because most people never even see that stage 1. They just see the end. Hey, I've put significant amount of thought and research and resources and real-world experience into making this for you. This is not surface-level content. It's structured so that you can actually implement it. If you're finding value genuinely with it, don't consume it quietly and alone. Share it with a colleague you think will find real value in it. That way, you're also helping them to take charge of their finances and build their financial future. That's generosity. The goal is not just about getting more views. The goal is getting better informed medics taking charge of their financial future. All right then, let's jump right back. Now let's use some practical examples. I'm going to introduce two doctors to you, Priya and Claire. Let's make it Even clearer, Dr. Priya and Dr. Claire, and they are both NHS consultants, whip smart, both with an adjusted net income of about £120k. They are both sitting firmly in the 60% tax trap. So they have crossed £100k threshold by about £20k. It's the beginning of the tax year, new tax year. Both of them are quite keen to invest. They are 42 years old both, and both plan to retire at 60. So they have 18 years and they also have extra $20K to invest. And every year they want to do that until retirement, okay? Because time in the market beats time in the market. But they make different decisions, and I'll share that with you. Priya goes ISA first. She transfers $20K straight into her stock and shares ISA on day 1 of the new tax year. The money goes in from after-tax income. She's already paid tax on it. No tax relief. No government contribution. $20k invested. Growing tax-free. Accessible anytime she needs it, of course, by selling the investment if she wants to. She feels good. She's acted early. She repeats this every single year for the next 18 years. But here's what she doesn't see. Her adjusted net income is still $120k. She still lost her personal allowance. She's still inside the 60% tax trap. HMRc contributed nothing to her investment and her personal allowance is still quietly being eroded. In fact, she loses £10k of her personal allowance, leaving her with just £2,570 of tax-free income. She remains firmly inside the tax trap and every pound she earns in that band is 60% taxed. Dr. Claire goes pension first. She pulls the same £20k from her take-home, however it goes into SIP. HMRC automatically adds 20% basic tax rate relief, so the gross contribution in her SIP is now £25k. She files Self Assessment and claims the additional 20%, so gets another £5k. Basically, like, from £20k, she's gone to £30k without taking any risk yet. But here is the second thing that happens, the one most people miss completely. Her gross SIP contributions of £25k has also reduced her adjusted net income from £120k to £95k. She has left the 60% tax trap. She has escaped it. Her personal allowance is now fully restored. Now the value of that restored personal allowance, the £12,570, or in this case it's actually £10,000. If you look at the 40%, it's like £10,000 coming back to her family. That's £10,000. 40% of that will be £4,000. So that's money coming back to her family. In addition to that, she's also gotten this grossed up that is invested. Okay, so it's totally two different scenarios, the same amount of money, different decisions. Dr. Claire using a SIP with money from her pocket is only £20K, but it's been grossed up all the way, £25K plus another £5K she's claimed through tax relief. And then basically her new adjusted net income has dropped below £100K. And her personal tax allowance has been restored, which the value of that alone is another £4,000. When you look at 40% she had to pay on that £10K. For Dr. Priya, it's a little bit of a different story. She's doing all right. She's investing, but she's not getting those extra contributions and she's still in the 60% tax drop. Understanding these things are really, you know, it makes a lot of difference in the long term. Now, if they continue doing the same thing year after year, Remember, these funds are being invested and it's compounding. Now let me show you exactly what that looks like when you run it all the way to retirement. Let's say they do it for 18 years each. Both Priya and Claire, they're 42 now, both plan to retire at 60. So that's 18 years of consistent investing and compounding. They are both buying the same fund, the global index fund, same market. Let's just use 8% annual return. Compounding, the long-run historical average for a globally diversified index fund that is tracking the MSCI index. So it's conservative, nothing crazy. And of course, past performance does not predict future outcomes, we all know that, but it matters less here than you might think because we are not comparing two different investments. Both Priya and Claire are in exactly the same fund, well-diversified global one. The return assumption is is the same for both. So basically what we are comparing is purely, purely the vehicle, the wrapper, the sequence, nothing else. So for every year for 18 years, Priya puts $20K into her ISA from her take-home pay. Claire puts the same $20K from her take-home pay into her SIP. HMRC adds $5K on top of that every year for Claire, so $25K gross, and then she claims another $5K in self-assessment. Okay, we already established that. The same 20K out of their pockets, but they, they applied it differently for 18 years. Here's what they finally end up with. Drum roll. Um, yeah, I'm running a free masterclass. Basically, we're going to look at investing, look at SIP, ISAS, NHS pension, how to combine them. It's going to be a free investing masterclass for doctors. Now, over 1,800 doctors have already attended previous masterclasses. And we've had hundreds of testimonials. If you want to attend, you want a free ticket, I've got one for you. If you check the link in the description, you can click to get a free ticket to attend my next free investing masterclass. It's 90 minutes. We're going to learn what medical school didn't teach us and what many doctors have spent so many years trying to figure out. If you head over to moneywisedoctor.com /MASTERCLASS, you can grab a ticket there or check the link in the description to get one. Now for Priya, ISA at 8% for 18 years will give her £808,000, and for SIP that Claire has invested in will be over £1 million. So Claire gets over the million pound mark. The gap between them is about £200,000. That's a massive difference. But that's not the end of the story. I know there's still tax. Okay, now let's be completely honest about the tax for Claire. Her SIP is going to be taxed when she draws it, and I know that's a question in your mind. But don't forget, 25% of Claire's SIP over £250,000 is completely tax-free. That part, the remaining 75%, which is like £750k, is taxed as income, and in retirement If she draws it sensibly, staying within the basic rate tax of 20%, I mean, if she's not drawing above £50,000, that could actually make a lot of difference for her. In fact, if she draws £12,570, she pays zero tax. If it's £50k to £70k and below, she pays only 20% tax on that. Now, if you assume that she's drawing 20% tax, remember she has the tax report as well. If you assume that Claire is drawing 20% tax on her pension, Um, so basically she would still end up with $859,000. So basically she's still going to be $50K, above $50K, above what Priya will end up with— $50,558 if you want to run the full numbers. So the SIP wins even after the tax at the end because it started with so much more, has compounded for years. But here's where it gets even a bit crazy. Remember that £5,000 that Claire was getting back from HMRC every year from her Self Assessment? What if she does not spend it? What if she puts it straight back into Stock and Shares ISA? Now, that £5,000 per year into an ISA for 18 years at the same 8%, that will grow to £202,231. So let's just say £200K. So Claire's total wealth will be around £1.2 million, while Priya will be about £800K. The total gap is massive, like £400,000. Okay, the same income but just different approaches to investing. So Claire ends up £400,000 wealthier than Priya simply because she funded the pension first and put the money HMRC gave her back, back to work, and that made a massive difference. So that's one more way to look at these numbers. Again, if you look at it from a long-term perspective, they're using the 4% sustainable withdrawal rate to look at how long that money can last. That means Priya could withdraw up to about £2,600, while Claire can withdraw £3,300 for the rest of their life. So basically, Claire has £675 more every single month for the rest of her life. Every month, not for a year, not for 5 years, for the rest of her life. If you use 4% withdrawal safe withdrawal rate, and she achieved that by paying only £90k— actually £90k less in investments over 18 years than Priya, who paid more to get there. So let that just sink in for a second. Clare paid in £270,000 total over 18 years, while Priya paid in much more than that. So Clare paid in £90,000 less and ended up £400,000 wealthier. So that's the power of the sequence. That's the power of the government contributions to your wealth. And that's exactly what most people leave on the table when they fund the ISA before the pension. Now let's be completely fair to Dr. Priya because she's not wrong to have used the ISA. Okay, she's used her ISA. Nothing wrong with that. Her ISA is completely flexible. She can access it at any time, any age, no restrictions, no penalties. She can just sell and take the money. If she needs that money before age 55, or it will be 57 from 2028, for any reason at all, she can sell, whether it's an emergency or she needs quick cash. Okay, Dr. Claire's SIP cannot be touched until she's 55, rising to 57 from 2028. That is a real restriction. But here's the thing, both Priya and Claire plan to retire at 60. Neither of them was going to touch this money before then anyway. We are assuming this, and both have their emergency funds held separately. So the SIP restriction is a theoretical constraint, not a real practical one. Now the question is never which vehicle is better in the abstract. The question is which one serves your situation best and in which order. Now one more angle worth mentioning before we move on is estate planning. Currently, a SIP generally sits outside your legal estate for inheritance tax purposes. Because SIPPs are held under trust, they're generally excluded from probate and distributed according to your expression of wishes. However, that's about to change. From April 2027, unused pots will now be factored into your estate for inheritance tax calculation. By contrast, your ISA already forms part of your estate and is subject to inheritance tax at 40% on death. Though ISAs can be passed on to a spouse or civil partner tax-free, and some AIM-listed shares within an ISA may qualify for business property relief as well. Right, some of you are asking, what about the Lifetime ISA? Well, it's also an ISA, but I want to address it because I know some people are thinking about the LISA, Lifetime ISA. If you're a LISA holder, Lifetime ISA, obviously you're thinking you're getting 25% government bonus It's free money, you can't beat that. You're right, it's valuable and it's genuine, but let's look at it a bit more carefully. Watch what happens when you compare it properly between a LISA and a SIP. The Lifetime ISA allows you to contribute up to £4,000 per tax year. The government adds a 25% bonus, so the maximum will be £1,000 per year. £4,000 grows to £5,000 in the pot, so You put in £4,000, you get £1,000. Excellent, fantastic. Now watch what happens with the same £4,000 in the SIP. Basically, if you put it, you get 20% automatically, which is basically 20% of gross. It gets you up to £5,000. Now when you claim another 20% in tax relief in self-assessment, you get another £1,000. So basically, your SIP, the £4,000 goes up to £6,000. So if you're a higher rate taxpayer, you can claim an additional 20% relief via your self-assessment. That's another £1,000 back to your pocket. So basically, again, your £4,000 has become £5,000 in the pension, and you have another £1,000 back in your pocket which you can reinvest in the pension. So total amount, total gross up working for you is £6,000. Let's put that side by side. LISA, £4,000 becomes £5,000 with the government contribution. See, for a higher rate taxpayer, £4,000 becomes £6,000 when you look at the tax relief. So basically, comparing these things properly really matters. And for someone who is 60% tax-free, it's even that much more important because you're getting back part of your personal allowance that will usually be taxed, um, if you didn't have this relief going in. Okay, so it makes makes a massive difference. But look, don't rush off to close your Lifetime ISA if you're a first-time buyer, or even if you're not. Um, one specific situation: if you're a first-time buyer, if you're buying your first home for no more than £450,000, the 25% bonus is available exactly for that purpose. And that's a powerful targeted benefit, and it absolutely earns its place there. But as a retirement vehicle, the comparison does not favor the Lifetime ISA. In fact, the SIP can be accessed from 55, rising to 57 from 2028. But the Lifetime ISA, you have to wait till you're 60 unless you are buying a qualifying first home. So even on access, the SIP gets you there earlier. And remember, the Lifetime ISA, you stop getting the government contributions at 50 anyway, right? So if you could use up the Lifetime ISA and the SIP and the stock and share Lifetime ISA if you can afford it, That's not too bad, but if you must decide which one should you start with first, understand which one gives you the advantage. Now, if you want the full breakdown of ISA types— cash ISA, stock and shares ISA, lifetime ISA— the rules, the limits, the penalties, I have a dedicated video on the channel covering all of it. Again, the link is in the description. For now, let's go back to Priya and Claire. They've done quite well. But $400K difference is massive. And even after tax, $50K difference is still quite a lot. So if you look at them, they've utilized basically different accounts and they've had different outcomes. And I know quite a lot of you, tax is something you worry about. You think at the end of the day you have to pay tax. I know some of you are thinking about, oh, you have to pay tax at the end. Yes, the SIP puts more money upfront into the pot, but it gets taxed when you take it out. The ISA is always completely tax-free, so ISA still wins in the end. Not really. Now, this is the most common objection I hear, and it deserves a proper honest answer. We've already sort of like examined the numbers. You're right that 75% of the SIP withdrawals will be taxed as income in retirement, but here's what matters. It's not just whether you are taxed, it's what rate you pay. And when and in which direction the money moves. Let's use Dr. Claire, for example. She's earning $120K now as a consultant, adjusted net income basically. She's paying 40% income tax, effectively 60% on the marginal income above $100K. In retirement, with a sensible drawdown strategy, she might pay 20% or even less on much of her pension income. And don't forget, 25% of her SIP it's already completely tax-free. If she builds a £1 million SIP, she takes £250,000 completely tax-free. The remaining £750,000 she draws down strategically, staying within the basic rate tax, paying 20%. That means, um, rather than pay 60% or 40% while she's working, she's paying 20% now on the money that has been allowed to breathe and grow and compound. She benefits at both ends. Compare that to Dr. Priya. She put £20,000 annually into her ISA from after-tax income. She's already paid 40% on that money before it went anywhere near an ISA. She gets it tax-free at the end, but she went in smaller and HMRC kept the difference at the point of earning. So the ISA exit is always clean, no tax. But if you entered it after you've already paid 40% or 60%, you've already lost that percentage and the ISA did not get it back for you. Now the SIP gets it back on the way in before the money has grown by a single penny, before any market risk as we say. Now there are scenarios where the ISA genuinely wins the argument and I want to name them for you honestly. So if you have fully used your £60,000 Annual Pension Allowance and you've used your carry forward from previous years, you don't have much choice. The ISA becomes your best option, not the SIP. 2. If your expected retirement income is very high, if your NHS pension plus State Pension plus SIP drawdown consistently pushes you into the higher rate tax band in retirement, the ISA becomes increasingly valuable as a complement to the SIP because the ISA exit is always 100% tax-free regardless of how much you withdraw in a single year. If you draw heavily from a SIP in one year, you can find yourself in a higher tax band than expected. But if you draw from an ISA any amount any year, HMRC gets nothing on that other end. So this is precisely why the answer is almost never ISA instead of SIP. Now, it is ISA and SIP in the right order for the right purpose for the right person, depending on your tax situation. Okay, now let me redirect. The SIP wins when one, your tax rate now is higher than your expected tax rate in retirement. That's the most common position for many senior doctors paying 40% or 45% or effective 60% tax rate while working and likely going to draw 20% in of income, 20% in retirement, basically because depending on how much you're drawing. Now, 2, SIP wins when you need to reduce your adjusted net income. If you're falling into the 60% tax trap or you have the child— high income child benefit charge is something that's going to be an issue for you at £60k or £260k adjusted net income, you're about to lose your pension allowance, then a SIP could actually help to reduce that. Again, third scenario where SIPs might win: if you're not planning to access your money before 57. The lockup is real, but it does not constrain your actual plans, so it's not a real cost. You don't need that money. Number 4, obviously estate planning, if it's on your mind. The SIP currently sits outside the estate, though that is changing very soon. The stock and shares ISA wins in these scenarios. One, you need access before age 55 or 57. Completely liquid. You can get it anytime, any amount, no penalties. Okay, so the ISA is the only vehicle that gives you that— the stock and shares ISA. Oh, I mean, obviously in terms of investing. 2, your expected retirement income is high and you expect to remain in the higher rate band even in retirement. The ISA is always tax-free where you're drawing it out. Okay, number 3, you want simplicity. You don't want to have to deal with all of that NHS pension allowance, NHS such as pension, how much of your annual allowance is still left, and you don't want to have to deal with all of that. So the honest summary is this: pension first to manage your tax position and claim government contributions, while stock and shares ISA second with whatever surplus remains after the pension target is set. Both in that order every year will give you the best of two worlds. But here's the bigger picture before we close. Let me just say this clearly one final time. The ISAs and the SIP are not enemies. They are not competing for your money. They are partners doing different jobs at different stages of your financial life. I use both. Think of the SIP as your tax efficiency engine for investing. It reduces what goes to HMRC today and builds long-term retirement wealth. It works hardest when you are in the higher tax band, and you're expecting to retire at a lower tax rate when you start drawing. Now, but think of the ISA as your financial freedom fund. Flexible, liquid, completely tax-free at any age, no rules about when you can draw it, no questions asked. I think you need both. I use both, and I think I find it useful. The question is never which one, it's always in what order and in what amount for what purpose. And that order for most higher-rate taxpaying doctors and professionals starts with a pension. Yes. So what will you be doing this tax year? I want to know. SIP first or ISA first? Tell me in the comment. I'll be interested to read your spicy comments. Um, yeah, so before you make any investment decision this tax year, start by understanding exactly where you currently stand. Most doctors have never had a proper financial health check. Not because they're not interested, but because nobody had ever, you know, designed a tool that helps to make sense for the specific complexity of doctor's financial life. So I made one. It's called the MedScan Financial Health Score. So it takes about 3 minutes. It helps you to look at your overall financial position across 7 key areas, including tax efficiency, pension, investment, investing, debt management, and financial protection. It gives you a clear score, a breakdown of exactly where you are, where the gaps are, and it's completely free. Takes 3 minutes. So if you head over to moneywisedoctor.com/medscan, or you can check the link in the description to get it. It's 3 minutes, real clarity, free. And hey, if you want to go deeper into investing tax efficiently, if you want to understand how to build a strategy that uses the ISA and the SIP in the right combination, understand investing, the core stuff, um, yeah, I'm running a free masterclass. Basically, we're going to look at investing, look at SIP, ISAs, NHS pension, how to combine them. It's going to be a free investing masterclass for doctors. Now, over 1,800 doctors have already attended previous masterclasses, and we've had hundreds of testimonials. If you want to attend, you want a free ticket, I've got one for you. If you check the link in the description, you can click to get a free ticket to attend my next free investing masterclass. It's 90 minutes. We're going to learn what medical school didn't teach us and what many doctors have spent so many years trying to figure out. If you head over to moneywisedoctor.com/masterclass, you can grab a ticket there or check the link in the description. To get one. Now go back to that comment you left at the start of the video, if you did leave one. Have you changed your mind, or do you still think it's the same? ISAs first or pensions first? Has anything in this video changed your thinking, or has it made you even more confident in what you're already doing? Tell me in the replies. I read every single one, and your comments help to shape exactly what I cover next on this channel. Now, if this helped you see something you had not seen clearly before, come on then, go ahead, share it with your friends, colleagues, especially that one, you know, the one who has been reminding you every year to max your ISA before the tax year ends. Maybe they need to see this too. Subscribe if you have not already, hit the bell, and I'll see you in the next one. All right then, bye-bye.







