Secret Hack Revealed: Finding Distressed Deals on Privy | Deal Finding Friday
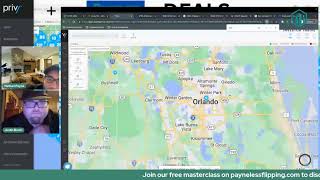
Justin Birch shows how to find distressed deals on Privy by stacking keywords like "loan assumption," "fire damaged," and "motivated seller." A live example reveals a VA loan at 4% and solar loan at 3%, blending to 3.6% on a $455k property. The key: set alerts, contact agents fast, and test keyword combinations.
Chapters
What is going on everybody from Privy Nation? This is Nathan Payne. I got a special guest today. What's up Justin, how you doing?
How's it going brother? Glad to be here man.
Yeah, I wanted to bring you on here guys because I was talking to Justin about Privy and he showed me a special secret hack that he has and I was like, I gotta show this to Privy Nation, I gotta show this to the world. So if you guys don't have Privy, you need to give it a shot. It's legit, you know, I use it. It's a great tool for finding deals that are on the MLS. And we all know that, you know, if you can get deals off the MLS and doesn't cost you any money to do it, it's a great way to find deals, especially if you're a new beginner. It's a great thing. So we're going to go over the strategy that he just showed me. I want everyone to try it with specific, you know, using the specific keywords he's going to tell us and in your market and go get some deals, guys. Because the reason why I'm doing this is I want you all to maximize your efforts. I don't want anybody in here not to succeed. So if you're watching Deal Finding Friday, if you're watching it with us, take action. Don't just watch. We want you to go do it. So after you watch this, you can take action or maybe even take action while we're showing you. So let's dive right in here. My screen.
And I used to say, I used to say knowledge is power. Applied knowledge is power.
100%. That's— I agree with you all the way on that one. So let's go over here and let's, um, let me pull up Privy right here. Okay. So everybody, if you've seen Privy, this is what it looks like. And you can obviously, you have the deals tab where you can, you know, depending on what area you want, you can find fix and flips, pop tops, tear downs, buy and holds. These are automatic filters that are set. But what Justin was showing me is there's a different way to go about it. So we're going to go here and we're going to clear the filters. And, um, we're gonna reset it. Okay, so you're starting fresh, everybody. And this is kind of like what it looks like. This is showing you the opportunities that are on the MLS that, you know, Batch— uh, sorry, um, Privy is, is saying, hey, let's— this is good, this is what you need to look for. So, uh, Justin, tell me a little bit about the strategy. Walk me through it like what you did before.
All right, so for first step, you would go to the filters, the filters tab. Okay, and you can pick a market, but for this demonstration we'll do nationwide because some of them are real niche searches that I'm going to put in there. And then you want to scroll down. You can put anything in the filters down there like bed count, whatever, but the main thing we want to show you is the keyword search. So let's say, let's, let's, let's say you're a sub-to student, right? Here's a good one for you guys: loan assumption. So type in loan assumption because then I know loan assumption and sub-to is two different things, but you could— but they're already ready to let you assume their loan, so you can just pitch Um, sub to them. So if you go to the houses and go in the description, you will see, um, loan assumption right there. They will allow a loan assumption.
Wow, that's pretty sweet. So you could go to this one, call and say, hey, I see that, um, you know, you're— they're open to letting me assume the loan. Uh, amazing. You know what, bro, that's, that's, that's a great hack.— if someone that's not able to, you know, qualify for a mortgage, they want to see. But, you know, and there's not that many in the United States right now. Yeah, it's insane. But, you know, these are ones that you call quickly and kind of determine what you can get done with it. So let's see this one. Guys, if you wanted to, you could call, you could call and go to MLS details. You could find the agent. You could, you know, well, this is a VA loan. Yeah, VA loan right here.
That's a good interest rate.
What is it? Where's the interest rate? Where are you seeing that?
So VA loans, I probably don't say it on here, but usually VA loans are like 2% to 3% interest rate.
Let's give a call. Let's call the agent. Let's find out what's going on.
So we call them.
Yeah, I'm going to call them right now.
Let's just—
let's show people how it's done. Then you can see what brokers they're at. Buyer's agent, blah blah blah. They usually have the phone number if you're an agent but I'm not so let's see. Office name, flaystay.com.
So let's see.
Flaystay.com. Okay, so I want his contact info. Usually LinkedIn does not give the contact info. Of the guy. Let's see, YouTube wouldn't—
I would take off the.com maybe. Good call.
And Reddit, you know, another way to do it is, let's see, we go here. We can also just look up this on Zillow, usually it pops it up. Listing, nice house.
Yeah, that is 19 days on market.
So 407-744— this is probably the brokerage, uh, number, and I don't like calling the brokerage, but, um, we'll give it a shot anyway. So let's— let me give him a call. All right, everybody, it's as easy as this. And if all of you are like, oh man, I'm a little nervous, I don't know what to say, I just want to ask about the rate. I want to ask about, uh, yeah, what would we be assuming?
Nothing crazy.
I just want to know if it's, uh, pencil it in, see what the payment would look like. Hi, the person you've reached is using a screening service from Google and will get a recording and transcript of this call. Go ahead and say your name and why you're calling. Nathan Payne calling about the house on Canyon Drive, Sage Canyon Drive.
Thanks.
Connecting you now.
Hello? This is Ken Johnson.
Hey, Ken, how are you? I'm calling about the house on Sage Canyon Drive. How's it going?
Oh, good.
Yeah.
Yeah.
Do you have, do you have a couple minutes to chat or did I catch you at a bad time?
Oh, I'm in my car. So until I get to my destination, I've got a few minutes.
Okay, great. Well, you know, I was calling about the property here and I see that it's, uh, the loan is assumable. Is that, is that correct?
That is correct. It is a VA loan on the property. Yeah.
So kind of, can you give me a little information on that? Cause I do like to buy properties you know, where I can assume them. And I just wanted to get a little bit more information on it.
Are you the buyer or are you a broker?
I buy and I do both. But this one specifically, if the terms make sense, you know, and I can cash flow, then I'd probably just keep it.
Are you a veteran by any chance?
Well, I don't— I'd like to think of myself as a veteran. I've been doing it for about 6 years. I don't know if that counts.
No, no, no, no. I mean a military veteran.
I'm sorry, I was like, well, veteran in real estate. I was like, I try to, try to be. Um, no, I'm not a veteran.
I'm not. No, because I mean, that would be the ideal scenario is if you were, of course, then you would have eligibility to assume the VA loan.
I've actually, I've actually bought, uh, yeah, I've actually purchased properties that have had VA loans. I've assumed their loans, but Um, is, is that just like preference, or are you saying like, is there something I'm missing?
Well, if you're, if you're not, uh, VA eligible, then the only consideration would be that you would have to, um, assume the loan and, and deliver a waiver to the seller so that he's free of the liability so that he can purchase another home using his VA eligibility. Okay.
Okay. Yeah. So, so he's not allowed to have multiple VA properties purchased through his VA status?
No. Essentially nobody is. Okay. I mean, if, if you ask the Veterans Administration, they say, yeah, you can do it.
But.
Right. Because their, their guidelines are so antiquated, in reality, you can't purchase much more than a trailer home. Right. And then use the loan again on something else. That makes sense. For all intents and purposes, yeah, he needs to be free and clear of any debt obligations so that he can utilize his full eligibility to purchase his next home.
Got it. So then, having you said that, if I understand correctly, would I still be able to assume the loan? It would just change like the interest rate and everything would change, or how would that work if I were to—
No, you would be able to assume the interest rate at 4%, which I think you'll agree is Not phenomenal.
Yeah.
Yeah. And the principal balance is a little over $400,000 in that loan. So you can grab $400K at 4%. Okay. Now here's where it gets a little tricky. This house has a, a electrovoltaic solar panel system installed on the roof.
I see that now.
That essentially takes care of the entire requirements for the home. Right. Now, where are you from? You live—
you live where? I live in Salt Lake City, Utah, but I invest in Florida.
Okay. All right. Well, Florida, the Sunshine State. You know, this is actually a place where solar makes sense. Yes. And there's a $60,000 solar system on the roof. Exactly.
Yeah, they get expensive.
And so there's, there's two ways that you could go as an investor. One is, you know, you got to in your mind add $60,000 onto the comparable value that you place on this home. Correct. Because you've got a brand new solar system on the roof.
Yeah. So you'd have to take over that payment of whatever the payment is on that thing.
Yeah, well, there's two ways you could go. You can either include the $60,000 in your offer, or the other possibility is there's an assumable loan for the solar system. Yeah, yeah. And that's $55,000 at 3%, which is even better.
Over how many years is the solar?
Solar is 25. 25 years was installed 18 months ago, so it's like 23 and a half years at 3%. Okay. Which again is like dirt cheap money.
Yeah, that makes sense.
So, so you have the ability to assume $460,000 in debt obligation at a very low interest rate. And so I've run the numbers. So at the, at the offer price, your, your blended rate, even if you were to get— even you were to finance the entire purchase, it's going to be about 3.6% with the solar and the, the more the assumable 4%, right, of the— the—
yeah. Okay.
Let me ask you this. Acquiring, you know, the balance of the financing elsewhere unless I don't know, would your intention be to use cash for the balance? Or—
Are you referring to like what's on top of the— what I'm assuming, like the difference between the $550,000 and the—
Yeah, the difference between the purchase price and the $460,000 that's available.
Yeah, I would probably— you know, hopefully my goal would be to negotiate a little bit down, but yeah, I would cash out the seller of their equity. I got a special guest.
Okay, um, well, uh, you know, run the numbers on it. If, uh, let's see, you don't have access to our MLS, do you?
I don't, but I'm right now I'm just looking at if it would cash flow, like if I were to Airbnb or if I were to rent this out, you know, considering the 3.6 blended rate.
Do you—
have you run the numbers to see what the monthly on that would be?
Yeah, what I was going to say is when we hang up, why don't you text me your contact information? Give me your email address. Okay. And when I get back to the office, I'll send you a spreadsheet that breaks it all down.
Okay. And, and let me look at it. Let me ask you this. I'm assuming, I'm assuming you've had both.
The other thing too that I, I want to make sure I don't neglect to mention is that because there's a solar system on the roof an electric bill that would otherwise average $410 per month is less than $50, which is great. Okay.
So yeah, keep that in mind.
So that's, that's like taking another $350 in as a credit against your monthly obligation for owning the home.
Yeah.
So let me ask you this really quick. I'm assuming, you know, I'm not the first one that's seen that this is assumable and you probably had quite a few calls. Is that correct or Or not really, and it hasn't had too much.
Yeah, no, in fact, um, I think this, this, uh, this particular listing, uh, the best case scenario is somebody who understands the value of getting really cheap money in the deal.
No, I understand that value for sure.
And, and is prepared to assume both the VA loan and the solar loan.
So with the amount of people who've called, because I just like to know what I'm up against, is $549,000, does that get it done? Is there wiggle room where I could offer a little bit less and still get it done? And by the way, I'm not represented, so you would be able to represent me on both sides of the transaction if you want, or just give the seller a discount on the buyer's commission.
What was your first name again? Nathan Payne. Nathan, what I would suggest is send me your contact info. Okay. I'll send you the spreadsheet that has the particulars on it. And I would say drop an offer. Okay. You know, let's, let's begin the process that way. Okay. You know, and just, you know, give me something, proof of funds or—
Of course.
Or, or, you know, eligibility for financing.
Right.
That shows you that you can get it done.
So just so you know, I'm not wasting my client's time.
Yeah. No, no, I don't I don't want you to waste your time. So I have a couple of business partners I work with. If I'm not able to send it to you right now, I'll probably have it sent to them because I'm actually going to take a drive right now. I'm going to Vegas with my wife. So, but I will tell one of my partners about this deal. But is not being represented— I know sometimes that benefits either the seller or the agent, you know, is able to represent us. Do you see that being beneficial in this sense? Like that, you know, if you can represent us or the seller, we get a 3% discount to them on the buyer's commission?
No, it certainly is advantageous to you as the buyer because there isn't the built-in 6%.
Of course.
Yeah.
Cool. All right. Well, that's what we'll do then.
I got—
this is your phone number, right? The one that I'm calling? This is your cell phone?
Yeah, this is my cell. So as soon as we hang up, if you don't mind, go ahead and just Send me your name so I don't forget and send me your email address and any other contact information and as soon as I get back to the office, I'll shoot that other info out to you.
Sounds like a plan. I really appreciate your time. It's been a pleasure, Ken.
Okay, Nathan, good to talk to you.
Yep, you have a good one.
Bye. Have a good day.
Good job, bro. Wow, right outside of Tampa.
Dude, it's a nice area.
I usually—
what I like to ask people if they have a VA loan is, um, do they have a place to go already? Because most of them will want to use their entitlements to go to, like, their benefits to go to another place. But some, some veterans already have a spot, so then you could take over their things up to—
yeah, yeah. And is he saying in this situation— I couldn't quite understand. It sounds like it's sub-to in the sense that we would be taking over his current $400,000 that is owed.
Is that— Yeah, so there's a difference between loan assumption and sub-2. Okay. So loan assumption is you have to qualify for it. So you'd have to qualify. That's why they're asking if you're a veteran. So loan assumption, you'd have to qualify. So basically, when you call these loan assumptions that are VAs, you got to convert them over to sub-2. So the best way I usually do is like get them on a Zoom, like me, like it would be you, the client and the agent and discuss sub-to and the benefits of it and all that stuff.
Very interesting because I'm not going to qualify. I'm not a VA. I'm not a veteran.
Yeah. So you'd have to switch it over.
Did you like when I was like, hey, I guess I'm a veteran. I feel like I'm—
Yeah, dude, I was like, oh man, I was laughing, bro.
I know. I heard you laughing. So that's funny.
Um, let's throw them some more keywords, man. Let's call some more people, like a couple more.
Yeah, so I was just wondering, I actually got to get going, uh, but, uh, but we can do some keywords just to show people what it looks like.
And yeah, let's show them a couple more keywords.
I think that was helpful. What do you think, Justin? Do you think that was good?
That was really good, man.
Okay, let's, let's give it—
let's go to another one. So for sub-to loan assumption, of course, like we just went over, and then you can—
let's go fire damage on them. What do Let's see how many fire damaged properties are in these areas. Okay, guys.
Oh, and make sure you hit the X. Yep, you got it.
Yeah, so fire damaged. We want to see if there's any fire damaged properties. I've sold a couple fire damaged properties. I've wholesaled a couple. You got to get them real low, but wow, look at these. Not very many in the United States. So this property in Vienna, Georgia, don't know much about Vienna, Georgia.
Union City. Oh my gosh, that's like a teardown, bro.
That's real bad, ain't it?
They want $65,000.
What? It's got to be for the land, dude, because you can't even keep that house. That's just—
that's just— dude, that's pretty hardcore, bro.
It's crispy. Literally still crispy, still hot. So you can see just from Privy's info that homes in the area that are comparable to this one before it got burnt down, are in the $200,000 range. So you'd have to see how much you could build out there for. You'd probably have to sell this to someone that builds, bro, you know, because no one— that ain't a rehab, that's a new build.
Yeah, that's crazy.
All right guys, so another one that you can try along with the filters you want to do is fixer-upper. Now fixer-upper I think is going to have a lot—
You're putting it in zoning?
Oh yeah, my bad. Fixer Upper is another one that is— I hit enter, my bad everybody. Fixer Upper, run search.
Handyman Special is pretty good too.
Handyman Special. Handyman Special is a good one. So if you're in the Tampa market like a lot of people, I'm in Tampa and Orlando. Let's see what Orlando's got. So you just go to see what you're working with. Oh, look at that one. I like that one. That was a good one. Let me go back. These are all great. Look at all these ones that need a little bit of love. Yeah, I wonder why they put fixer-upper. Maybe because it's been fixed up. The property provides an excellent— I don't know what they're smoking. That's not a fixer-upper at all. Okay, right here, right here. Yes, sir.
Okay.
Yes, sir. So this is a great way to just be like, you know, Privy already kind of gives you the juice by giving you the filters, but you can just quickly, like Justin showed us, just quickly be like, all right, let's give it some love. You know, Justin, you know, it's a really interesting thing too, is like pictures are a huge factor in this. Like if you were just to clean this house out, like if you were just to, you know, get it vacant, and just take nice pictures with nice lighting, this house could probably sell for an extra like $40,000. I don't know, I haven't run the numbers, but that's a big, big thing that agents are not very good at is they just take bad pictures, bro, and it just makes the house look worse. So, you know, they could really— that's what back during the pandemic, that's what a lot of people would do is they would just look at, you know, listings that look dirty, they buy them, just clean it out and relist it, and they'd make $40,000, $50,000. So just so everybody can know how important it is to stage the property right. Like right here, let's see this. This is a comparable, it's saying. So $500,000. Okay, so this one's a lot nicer and it sold for $557,000 and they're asking for $500,000. So they're too high, way too high on theirs. It's $535,000 in that.
And you can even stack the— stack the keywords too. So let's say you want a fire damage that has tax problems. You can put two keywords and it puts both of them at the same time.
That's right. So we can go fixer-upper and then— sorry, that's actually already there. Let's go handyman special.
Yep.
See how many are stacked there. There you go. So a lot of these agents will not only put one of the keywords but they'll do multiple. You go in here, so you got fixer, you can see it's right here, fixer-upper, fixer, and you got handyman.
Oh, hand.
Yeah, it's got a hand. Oh, special. Let's see if that's— I wonder why I pulled this one up with that.
I don't know, that was weird. You know, you know another good keyword? If you erase those two, this is a good one: motivated seller. That's a good one. We're about to find out because now you'll know they're motivated.
Ooh, okay. So this house, they're motivated. So you could, even though it's a nice home, maybe you could still get subject to, maybe you could get some, you know, favorable terms or the price might go down. Um, great idea, brother.
Right there.
Motivated. Welcome home. Well guys, you know, hopefully this was a helpful, um, breakdown of how to do this. Justin provided immense value. We got some people saying, do you have preset alarms on your filters? A lot of people do that. Yes, you can do that, Uriel. Set that up. Good stuff, gentlemen. Carlos, we appreciate you. What about an FHA loan pre-foreclosure with no equity? Bro, test everything out. Anything you can think of, bro, test it out. See what we can do. And the key, the key to getting deals, guys, is making the offers. You heard the agent himself. He was like, hey, just make me that dang offer.
Right.
He was just like, just make an offer and let's go from there.
Like for Rodriguez, he can put FHA in the filter.
FHA in the filter. All right guys, well, I hope that was helpful. This is Deal Finding Friday. These are the secret hacks brought to you by me and Justin Birch. All right, check him out if you haven't. He's got some great tips. He's willing to help as well. So we'll catch you guys later.
Later, y'all.
More from Nathan
Why Traditional Wholesaling Keeps Failing You (Use This Pre-Flip Method Instead)