Scott Selleck breaks down the Hawthorne, NJ market where homes sell 5 days after listing and 7-8% above asking price. The problem: appraisers use older comparable sales, creating a $50-$85k gap between your winning bid and what the bank will finance. Only cash or conventional buyers with liquid reserves can cover it; FHA buyers win just 2.4% of offers over ask.
Chapters
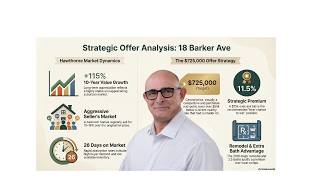
The Hawthorne real estate market is currently starving for inventory. With year-over-year appreciation hitting between 7% and 8%, homes are being absorbed in an average of just 26 days. If you are operating on traditional home buying advice, you are already behind. Look at this aerial view of the neighborhood. This dense, highly established suburban footprint means almost no new construction. The demand is entirely focused on a fixed number of existing lots. Take our subject property, 18 Barker Avenue. It is a 4-bedroom home listed at $649,999. In just 5 days on the market, it racked up over 100 saves and 3 offers, 2 of which are over the asking price. This cascading bar chart illustrates the modern pricing reality. The list price of $649,000 is marketing fiction designed to generate foot traffic. Zillow estimates the value slightly higher at $658,000, but based on current market dynamics, securing this property requires an offer of $725,000. Bidding $75,000 over asking introduces a massive structural problem. You are willing to pay $725,000 to beat the competition, but banks do not lend based on your desire to win. They lend based on conservative valuations of their collateral. In a seller's market, the list price functions strictly as a starting bid. To win, you have to bid high. But winning often means taking on significant financial exposure. This exposure comes from how appraisers and buyers value properties differently. Appraisers seek safety by comparing homes with identical architectural styles. Buyers ignore architectural categories and compete for modern upgrades and move-in-ready conditions. To an appraiser, the safest comparison for 18 Barker is 370 Goffle Road. They are both Cape Cods. It recently sold for $640,000. However, it lacked 18 Barkers' 2016 major remodel, the premium kitchen, and the ductless AC. Looking at this photo of 163rd Avenue, you see a completely different architectural style, a colonial. It sold just one week ago for $780,000. Even though 163rd Avenue is a colonial, it represents the true market appetite. It closed $91,000 over asking on a lot that is actually smaller than 18 Barkers. If buyers are aggressively paying $780,000 for that footprint, a $725,000 bid for 18 Barker's upgraded interior and larger lot is supportable. This matrix breaks down the risk. Your bid is built on the $780,000 colonial comp. If the appraiser anchors strictly to the $640,000 Cape Cod comp, the bank refuses to finance the difference. That leaves an appraisal gap of $50,000 to $85,000. Winning the house means you must bid aggressively, like the buyer of the colonial. But actually taking ownership requires you to be financially prepared for the bank to appraise it like the standard Cape Cod. This is where the actual dollar amount of your offer stops being the most important number on the contract. Sellers are scrutinizing how you plan to pay. This chart tracks offer success rates by loan type. FHA buyers, who typically have strict appraisal requirements, are winning homes at just 2.4% over ask. Cash and conventional buyers are dominating, securing properties at over 13% above asking price. Cash and conventional buyers achieve this by using an appraisal gap waiver. This is a contractual promise to the seller that if the bank's appraisal comes in low, the buyer will cover the difference out of their own pocket. To execute this strategy, you must have up to $85,000 in liquid cash sitting in a bank account. This is entirely separate from your down payment and your closing costs. In multiple offer scenarios, sellers aren't blindly chasing the highest top-line number. They search for the buyer with enough cash to absorb conservative bank valuations. Your offer strategy comes down to a single variable: how much liquid cash you have to bridge the gap between market reality and bank policy. We map liquid cash against offer competitiveness to see two distinct buyer segments. Segment A has the $85,000 cash cushion, operating in the secure winning zone. Segment B, utilizing FHA, cannot bridge a $50,000 shortfall, landing in the high rejection zone. Crafting a winning bid is a cold calculation. It measures your liquid assets against the specific appraisal risk of the property. If you fall into Segment A, the data supports an aggressive move. Offer $725,000 with a full gap waiver. 18 Barker's 2016 remodel and Hawthorne's strong appreciation rates justify the premium over the long term. If you are in Segment B, bidding on 18 Barker Avenue is a misallocation of your time. Your financing structure simply does not match the heavy risk profile required to take down this specific property. Constrained buyers need a pivot strategy. Drop your target list price by $100,000. Look for homes in the $550,000 range where you have the breathing room to bid aggressively and where your loan structure is an asset, not a liability. The most dangerous mistake you can make right now is the emotional overbid, offering $725,000 to win the contract while knowing you lack the cash to close the deal. That path leads directly to lost deposits and legal trouble. A successful real estate transaction requires leverage you can actually back up. The smartest offer is the one that aligns the aggressive reality of the market with the safety of your own balance sheet.