BoneChat #138 - How Startup CEOs Can Negotiate Corporate Deals Without Losing Control

Mike Minette, who spent 30+ years in med-tech partnerships at Exact Sciences and Medtronic, walks startup CEOs through negotiating corporate deals without losing control. He covers distribution, licensing, and joint ventures, and stresses validating market interest early, protecting IP, and building internal champions at the buyer before revealing your full hand.
Chapters
Okay, welcome to BoneChat 138. Uh, the BoneChat members have asked me to bring in a partnership licensing expert, so I found Mike Minette. I, I'm calling him the king of deals in our industry. Uh, he's orchestrated deals in orthopedics for High Ridge, Brainlab, Zenvi, Canary Medical, mBody, and many, many more in medtech. Mike only has 4 slides, so get your questions ready early. Welcome aboard and thank you for being here, Mike. And I'm going to, I'm going to try to share slides now.
Let's see.
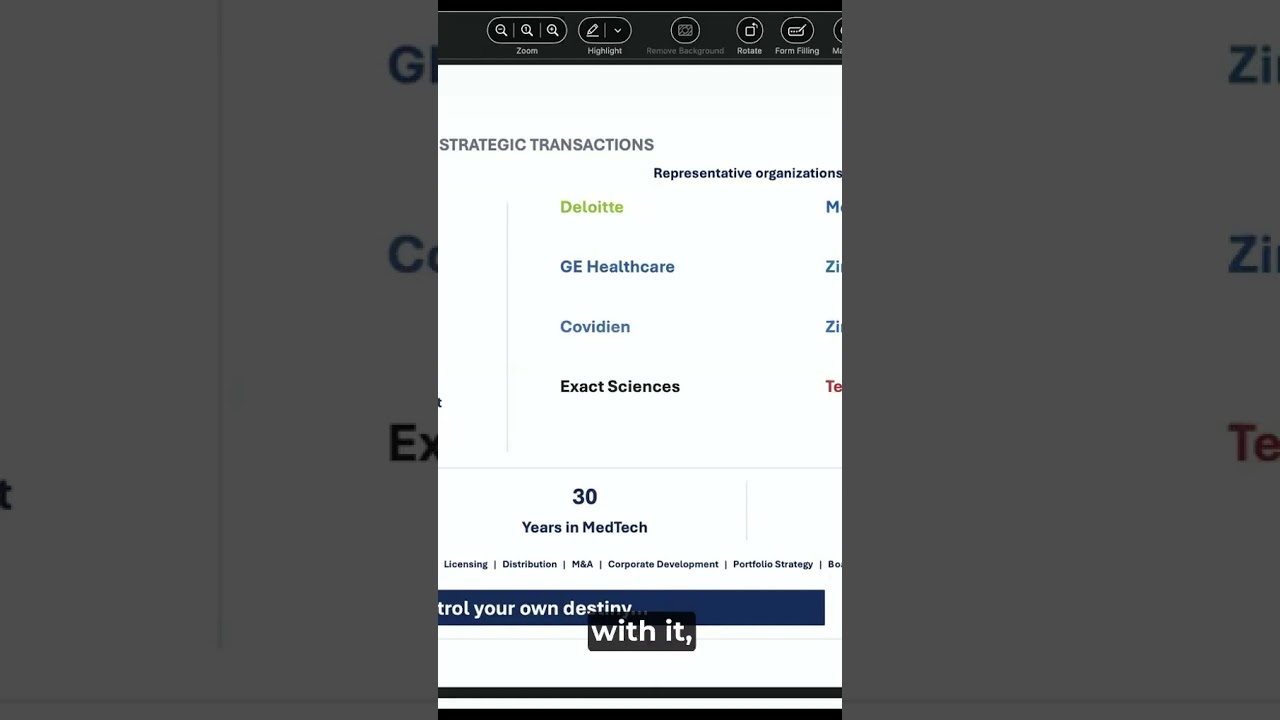
Very good. Well, I'll fill the air because no one likes quiet in business or in any other part of your life. But so, hello everyone, thanks for joining today. Mike Minette, as Tiger so introduced me, I've got about— Tiger said, hey, listen, let's be flexible, 45 to an hour. I'll try to spend about 10 or 15 minutes, you know, going through just a little bit on me because that's the boring part. A little bit of philosophy on kind of just deals as a whole, because I think at even at smaller stages, I'll call those sub-$100 million revenue organizations, you have to be open to all different types of inorganic activity. We'll focus a lot on partnerships because those tend to be the most cost-efficient for cash-strapped organizations or organizations that watch that bottom line closely. And then I'll dive into some more specific stories, and then we really want to open it up to hear from you. I want to take live questions in any way, shape, or form. And, you know, the less we can, we can share in terms of details, but in philosophy, I'm happy to do that. And also happy to have follow-up calls if folks have very pointed things. So thank you again, Tiger. Go ahead and click to the next slide. So just a quick basis, Tiger kind of gave a bit of a comment off the top. You know, I, my career itself has been over about 30 years now. I started out in sales in the OR, you know, worked in Detroit, and that I will say, as I've kind of laddered throughout my career, moved around, it was very important to me because those first 3 years in sales were very formative, especially as I make recommendations to organizations. Because what we can't forget on any deal, and that's, you know, if you're at a Medtronic or you're at a zero revenue stealth startup, is how do you transact with the customer. So I took that into every decision I made. So that sales rep, I proudly hold that as the first job I had out of college. And it was kind of a near miss. I was going to go into finance and I ended up getting done early with my degree. And took a bunch of life sciences electives and just got the bug for disease states and really just wanted to go into healthcare. You know, listen, I'll blend a little bit of the left-hand side with the right-hand side. I always kind of say that Deloitte, GE, and Covidien gave me all of the education, postgraduate school that I needed. Exact Sciences taught me a lot about what and what not to do, and that was a hugely successful organization and only kudos to that. And then, you know, Medtronic and Zimmer Biomet provided me with more executive-level experience where not only did I have, you know, responsibility for driving the overall strategy portfolio of new products and business and corporate development, doing a lot of venture work. Those were great opportunities for me to kind of spread my wings. But, you know, that was also a time where then I had teams or teams of folks that that were helping me develop greater market access, doing clinical trials, proving out our market thesis, bringing new products to market, at the same time augmenting with partnerships and acquisitions, and also held kind of the reins of doing integration. So, you know, our day job— and I kept this as strategy— is a 13-month-a-year job, and you, you don't just do it for a month or 6 weeks out of a year like some corporations did for a long time, which always kind of irked me. But I I feel like those organizations, you know, were good platforms for me to kind of learn and get to see a lot of different stuff. Today, so 2.5 years ago, after we sold the Zimvy assets, which one was High Ridge and the other one was Zimvy Dental, which went to both private equity groups, I kind of hung my own shingle, though the name is not known because I do not advertise, is Terra Rouge. That's, it's real simple. My family came from Luxembourg. And that's an area near France which had a lot of iron in the soil. So the soil was red. But that being said, throughout my career, you know, roughly 150 or more transactions completed. I, like I said, the more interesting ones are the ones we walked away from. And, you know, that's a little bit of a comment because when you have a big balance sheet, you can pay to walk away from things. And sometimes in small organizations, walking away is really hard because it's the access. And I've worked in zero-revenue startups a couple of different times, and also, you know, companies that have had, you know, $30+ billion in top-line revenue. So the one thing I will say, and I say this to all startup CEOs and boards that I work with, is especially when you're doing a deal, you must always reserve the right to control your own destiny. Sometimes we get into situations where we do not want to, do a deal or a situation, or you just don't feel right with it, but you're backed up against financial problems, market momentum, need to have something on the PR base, delight investors, attract new investors, and you'd be forced to do something. But giving away your ability to control your own destiny, i.e., make decisions for the company, to walk away, to sell, those are always, I think, the most important things. And matter of fact, even one time, and this goes back about 15 years ago, I was working with a startup CEO and I said, listen, this part of the contract is totally not, you know, going to help your company. It limits your ability to make decisions. And so I'm going to reverse that, even though my director worked very hard on making sure that those terms were held in place. But that being said, happy to answer any other questions about my background. But let's, Tiger, move to the next slide because I think As we look at, as we look at kind of the toolbox here, there's a lot of different deals to be done. And there's a, this will flow with the next page in terms of how you stage this. But the way I've always looked at it as from a commercial perspective, these can be the low-dollar, high-value, get into the market type of deals. Distribution is probably the most common one. This is nothing new to anyone. Licensing can be tricky because Often small companies don't have licensable technology, but sometimes they do. And, you know, giving that away can be giving away the farm and, you know, reduce your own control of your own destiny. OEM, unless you're like in a business that is an OEM business, is a tough pivot for a proprietary company that has proprietary technologies. But I would often say to folks, why can't you bifurcate your business if it cash flows and you can divert dollars into, you know, your proprietary business, why is that a bad move? It doesn't happen all the time, but it can definitely happen. And so I would say one of those nuggets would be if you get kind of an off-the-wall offer, you know, don't turn it down for just, that's not how we do business, and walk away, because there could be really something in there that could really help you get to the end of your journey with your initial strategy. So especially in times where capital is tight, being flexible is important. And that doesn't mean going up to 15 or 16 points on convertible loans. I've had probably in this area, probably the number one deal I did was on a co-marketing deal. I had never done one. It was at Exact Sciences. We had We had a small relationship with Ironwood Pharmaceuticals that really bridged the gap to a full-scale sales force. And it was— our stock was at, you know, call it $20, and then it dropped down to $6, and it really buoyed that organization. And actually, it may have been higher, maybe $30, and dropped down to $6. And that partnership helped us claw back to $30, and then everyone knows the transaction to Abbott was over $100 a share just earlier earlier this year on a close and an announcement late last year. So, you know, even though I had never done one, it may have been one of the most impactful. So that's where I would say on the, you know, the side of making sure you keep an open mind is you never know what could be the most value added to your organization. And believe me, as CEOs, I know you get crazy phone calls all the time. And that doesn't mean, hey, you know, embrace the crazy and listen to all of them. But it's worth some mental processing time from time to time, I believe. The strategic— listen, deal du jour in the 2000s was joint ventures. Hardest deals ever to put together. It's bringing two companies together that try to bring their own primer or structure and build another company together. And I've done a couple of these. We did one where it was brick and mortar. It was combined manufacturing. It was better part of a year in the making. It did almost nothing besides kind of a lopsided press release. It didn't generate any value in the market from our perspective. And I'll talk a little bit more about some of those trappings, you know, here in a slide. But if someone says joint venture, you say, is that a contract joint venture? And if that's okay, then that's just a fancy way for saying another type of quasi-commercial investment, you know, opportunity. And again, these are where the mind of the creative, but the, you know, I would say resolute in what you are trying to do is really, really important. One of the things I will say to my, you know, the folks that I advise, one being here on the phone today, is, you know, as the CEO, you're the lifeblood of the organization. Don't take your eye off the ball for a year, otherwise your organization will die on the vine. So preserve your time for revenue generation and product development, the things that really, you know, make the company work. And while deals can be sexy, partnerships can be a nice press release, their hit rate is actually not huge, right? It's not an 80% success rate. I would venture it's less than 50% of the time these are value-added to the organization. I would say some would say the numbers are even less than that. But at the same time, it can absorb an enormous amount of time of your organization, so much so that we would see this from time to time. At GE, uh, we would throw the GE playbook in diligence and quality management systems and every other thing at these small companies, and they would drown. And then we'd get 3 months later during the negotiation and say, we need an update on your financials. And they'd say, well, we're down. But why are you down? Well, it's because everyone on the, on the company was pouring their heart and soul into getting diligence completed and we took them away from their customers. So that's one of those things that if you ever get into a process, whether it be, you know, a licensing deal or, you know, a merger or an acquisition, you can't take your eye off the ball of the business. And I listened every time a CEO would ever say to me, I've got to go run my business, I can't be dragged through the mud on this. I wholeheartedly respected that. But today the game has changed quite a bit too. I'll even tick on market access. This is the VAT Committee's which I remember coming 20, you know, 20, almost 30 years ago. They're like another FDA for startup companies. And it stifles innovation. It's really tough. It's— once you get the approvals, you've got to go through step by step, organization by organization. We've got to find a way as an industry to really ramp up market access for newer startup companies because it's going to continue to stifle innovation. Innovation has to get to the patient. And I think you all would agree with that. I'll just tick on international. That from time to time has been an amazing shot in the arm for organizations that are trying to grow and maybe hitting a little bit of a slow spot waiting for that next product to come to market where you can really expand your business. You know, these can be good chip shot deals with good organizations, but you've got to do a lot of work on them too. So that's not for the faint of heart. I'll kind of skip the capital side of this a bit because these are things you folks deal with on a day-to-day basis. We've talked a little bit about there's tight money out there, but then I would also say on the corporate transaction side, when you get of a size or you get of an interest level, these are things that happen very fast, but also some would say it's very slow to get there, but it's very fast when it happens. And I'll weave in a couple of commentary throughout the next page or so and answer any questions. But I have this philosophy of you must always be preparing yourself to be ready for that inbound phone call from the perfect strategic saying, listen, we'd like to go under diligence, we'd like to take a look, we'd like to see what you have. And there's nothing better than being ready. And there is also, and this is a trick of the trade, maybe this is something I was going to see on the next slide, is if you've got a data room or a deal room just kind of sitting there waiting, It's easier to turn that on than to take the 400-question request from a Johnson Johnson and then scramble your organization to find documents and create documents to satisfy what might be their initial swaths of diligence. And again, as big companies, we try to get better about this, but the reality of it is, you know, we're still pretty bad at that or really good at doing diligence. So that's the— the challenge that we have. And, you know, a couple of takeaways here is, you know, the structure has to follow the strategy. And you might say, well, geez, Mike, what structure? Well, of course, your organization structure has to follow your strategy. Any type of deal you do, meaning the contract, that has to follow your strategy as well. If you deviate too far from that, you're going to find yourself in compromising situations. And I would also say, that the construct of how the flow of your relationship works, that organization that has to follow your strategy as well. Again, you can compromise your strategy if it's the right thing for the market. Maybe you don't have the capabilities to do something, but your partner does and you're like, wow, I'd love to go after that, but I don't have the extra $5 million to do it and they do. But I would just say that those are when we get bright eyes and we follow the shiny toy, we can get off the ball in terms of are we going to be able to execute this, um, at all? And then, you know, I mentioned this earlier, the reality check. That is just true. Um, large corporations don't do partnerships well, um, and it's, it's a thing. And I think maybe large corporations have a harder time doing, doing them well. They've gotten better in doing tech relationships, um, but you don't see a lot of medtech companies come and do big partnerships. You see a lot of private equity or, you know, venture stuff. They will do that in medtech. Tech seems to work well because they can complement each other. But I would say that— and I saw two deals that we did at GE. One was with Johnson Johnson. It was dead on arrival. We just— two different organizations that were alphas that could not work a different way than they worked. And we tried partnering and it just didn't work. And that was one I wasn't part of. I had just heard the horror stories of it. It was a great press release, but it ended up being not much. And then I was very close to a deal we did with Intel on home health at GE. And listen, they wanted to sell processors and chips. We wanted to sell healthcare equipment. They just wanted a press release to be in healthcare. And it just didn't work out. It was one of those things. And we found that out kind of way too late after we formed a joint venture.
I'm going to hurry you along, Mike.
Yeah, please do, because I feel like I am droning a little bit. Let's move on to this stuff. I'll tick through these, everybody, but I hope that this starts to answer some questions. And I've tried to hit this a little bit. As you line incentives, I think on any deal, you need to have that before you negotiate anything. And I think that that's just getting to know people, familiarizing yourself. It sounds logical, but it's often we jump to negotiating. And listen, I'll tell you, everyone from day one saying hello is somehow positioning or negotiating. You just have to really get aligned. And I feel like that sets the roadwork. And in doing that, you've got to understand their values, what they truly value. Are you something that is a stopgap for the organization? You know, it's kind of like telling your 2-year-old, "Ah, you're going to be the king or queen of the castle for the next 3 years until your next sibling comes along." It just doesn't work all that well if you're going to be a stopgap. But if you're going to be front and center or the tip of the spear for this organization, you've got something that's really valuable. Economics need to work in everyone's favor. This is why lawsuits come about. That should be pretty straightforward. I've talked about number 4. So, you know, I also am a firm believer that when you start your company and you get to your kind of market, you know, you're meeting the market, is how would you like to transact if you want to transact? And, you know, what will you entertain and what won't you? And I also think that this number 6 really goes back to kind of number 2 and number 1 is you've got to be in line with the people you're working with and not just the person who's got a president in the title, vice president, associate vice president, senior vice president, executive vice president. You need to know the person you're going to be working with when the contract is— ink is dry. I think those are just really important things because that handoff can be rough and bumpy and you may feel like I need the attention of that person who's got other things to attend to. So making sure you know is really important. The don't side, listen, Don't force anything. This goes back to the own your own destiny. Bad economics, even though the deal's in front of you, continue to push on it. You just, you don't need to get bad economics. You don't need the, I can bankrupt my company if we're maybe not even successful with this. These are just really, really touchy things that big companies will force upon you, even smaller or mid-sized companies. Culture, we talked about earlier. It is, I think, tantamount. Don't ignore it. It was funny, my mom did a lot of M&A from her HR executive role while I was in high school and college. And she said, we would do HR assessments all the time. And I said, well, why would you do that? She's like, because, you know, they eat strategy for lunch after we merge them together. And I think that's a quote from one of the strategy oracles. But also, you know, the signed agreement is not the success point unless you're just doing it for a press release. It is, it is really the starting gun of a very arduous race. It does not get easier after that contract. It gets harder, and if it gets better because you're doing so successfully, it's still, you're still going to have pain. And I would always say with the teams is never confuse activity with progress too. So I talked a little bit about alignment. GE and Intel, we weren't aligned. You know, good culture fits. I found that Covidien and SuperDimension very much on the same page. We did an investment, we did board observer, we acquired the organization, big earnout for them on the back end so they could stick around and drive. We doubled and tripled that number kind of year over year. It was a great success. That was one of the reasons that Medtronic came in and acquired Covidien, as they were trying to figure out how you incubated small companies. So there was a capability there. Zimmer and Paragon, I took the first crack at that. They completed it after I left, but that was an organization— Zimmer hadn't launched 2 or 3 products in 3 years. If you looked at the tail of the tape, what Ivan Tornos said the other day, we're gonna launch 50 products in the next 3 years. That was our goal, and Paragon was so aligned with that. And so I think you had a real good meeting of the culture there. And then I talked a little bit about a great deal with Exact Sciences and Ironside Pharmaceuticals. We were looking at Valiant very closely, and this is just before they imploded. And we had to walk away because we just didn't like how it was all coming together, the rumblings on Wall Street and so on and so forth. So, we looked at that as that could be a problem and that could have blown up in our face in a bigger way than we thought. So, I'll let you all read the key principles, but let's move on to how we apply this because I've taken a few more minutes than I wanted to. I'd love to hear from you all about partnership opportunities or things that you're working on right now, where you're up against a roadblock or how should you think about it differently? Bring those real situations. I mean, I think there are situations that you've probably said, geez, I've never seen this before and am I crazy or do I just have to say no to this? And then I always think, you know, personally, you know, the strategic side of if you're wanting to attract a large Fortune 500 company is how do you present yourself, build yourself and really, you know, make yourself digestible to these large organizations if you want them to transact. And it's a bit of work. You've got to speak their language. You've got to know their strategy. You've got to, you know, really sink into what is important for them. And I always kind of tell folks, if you can write the presentation for the business leader, the business development leader that they can take all the way to the CEO, and this is why we match strategically, this is where it helps our organization. You've done that job and you've made sure that someone in between and again, guilty in business development from screwing up the message in between. So I'll stop there. I promised 10 to 15, I went to 21, my bad. But hopefully this has answered some questions, but I'm definitely open for business in terms of fielding yours. So thanks everyone.
All right, open, open question time.
Mark, have you ever seen a company succeed or a strategic alliance succeed without the C-level people being totally all in full time?
Yes.
Yes, I have. And I'll tell you why is because I think in those rooms you've got, and I always say the classic one where the CFO is just like, this is a lot of money for something that is a bet. But you can have people in the room with the CFO respect the CEO, the COO, the president of the business that say, no, we need this. It sounds like it's coming off as a big gamble. So yes, I think you can. If you've got dissension in like 50/50, you're going to really struggle. If you've got dissension of one or two and the others can kind of close over it, then I think you can. But you know, that, that, that's a tough one. You've got to get the approval. Sometimes people at the C-level will say, go ahead and do it, it's your neck on the line, and then you've got to prove them wrong. But I have seen that in, in my, my experience kind of going both ways where we didn't get full approval but we got partial approval and here's what we're going to do. We've fallen back and said we're not going to acquire you but we want to do a distribution and an investment. Um, so it wasn't— and then those often turn into acquisitions later down the line. Even after a recall, we had that happen once. So, um, so yes, I have, uh, but it's, it's, that's a hard mountain to climb, Mark.
What about at the startup level when you've got just a relatively small team versus a bigger kind of a bigger team?
Yeah, you know, I find it where the CEOs often, you know, have to kind of put their foot down. Either listen to the person and say, I agree with you, uh, but I've got to push this through for the for the reason that we've got to take the flag on the mountain. Um, or, you know, how can you not get in line with this? But, or, I respect you enough to say, if you're saying this is going to cripple us, then, then you've got reason. So it— that, that one is a bit tougher because you're right, it's usually smaller, there's usually a higher level of trust, there's a lot more on the line. Um, but I think it's, it's to really understand that, uh, and get them to really really explain why it's not a good deal in their eyes. And I, you know, I can think of examples, but it's, you know, that's part of the sales job internally. And it's not the CEO sales job. It's the, we got to do this for a reason. And if that reason doesn't resonate with one or two, then, you know, what you don't hope is on the back end that they don't, they kind of try to dog the deal afterwards, not give it the attention it needs, make it look like it doesn't go well. And people listen. We trust them, but they can poison things as well.
So thanks.
Yeah. All right, Patrick's up next.
Mike, can you talk about sort of what you see as the pros and cons of if you're a small company trying to sort of court the attention of a large company and the sort of pros and cons of trying to sort of like work it through the business versus work it through the business development function? I think different companies probably have different perspectives on that and maybe it's, maybe it's a situation-by-situation answer, but I know I have seen totally different approaches with different large companies that they sort of like, they want you to work it through the business or they want you to purely work with the BD function. What's your take on that?
Yeah, it's a, I think it's a great question. I can tell you what works really well, I think overall, and it can also be annoying. So there's friction in a lot of this. If you do it well, you're probably pressing some friction. So I guess my comment is one is organizations will have a prescribed path. And so just adhering to that is probably a good thing.
Yeah, if they say it, sure.
Yeah.
I'll go back to my earlier comment about, you know, early on you should have a plan on how you want to transact. If you say, hey, I want to sell to Medtronic, okay, as an example, you need to start building the relationships all across the board of that organization over time and have a logical, methodical plan to keep them updated and interested. It's my personal opinion. So build a relationship with the product people, R&D, you know, get the BD people because usually they come in a little later depending, you know, have quality updates versus, you know, things that are, you know, hey, I'm just pinging you because I want to see if you guys are now ready to acquire us. And believe me, I've had those all the time. But bringing and adding value, hey, here's our update, our sales are up 40% quarter quarter. You know, we got, uh, you know, 2 more pieces of intellectual property patented. You know, we've got, you know, we've added 4 more distributors to this relationship. Um, you know, we're starting to make moves. The thing about Medtronic, if you look at the spine space as an example, they're surgeons. You can crack one of their surgeons and they start chirping. All of a sudden you've got this chorus, and then you're going to meet at some point at a conference their senior vice president, their general manager. And then I think what you need to do is really keep them all updated with a different marketing and messaging campaign. Almost treat it like you're going after different markets, uh, or different buyers. The teenagers, you know, the 20s, the 40 pluses, and then the geriatrics, right? How are you marketing to those groups? And I'm not saying it's because their age, because I think you do need to kind of, um, manage that message. I'll tell you the annoying part. It was very effective. We were acquiring a technology out of Israel, and I've acquired 4 technologies out of Israel, but one of them, the guy He would tell you part of the story and then he'd call 3 other people and tell them different parts of the story. So, when we get together in meetings, we'd all have 4 different perspectives because he had infiltrated us and almost used psychological warfare against each other to move the deal forward. It didn't move forward. It took us 18 months to get the deal done, but he had successfully infiltrated everyone and was pushing them in different directions, almost to a point where I said, okay. Hey, business development director, he can't talk to anyone else anymore until we get this contract done. And he talks to you only. I wouldn't say go quite that far, Patrick, but you get the point. It does make sense, especially if you're instilling fear in the organization.
Sounds like an old Army tactic that they used or something.
Yeah, yeah.
But hopefully that made sense. I mean, I do think there is a, there is, as part of your plan, you can have a plan to say these are our 3 potential buyers and I'm going to work the, you know, work the room on each one of them and have those contacts. Because when you, when you do get into something, you can always go to that person and say, this is what I heard, but did I hear it right? And you maybe get a different answer from a director than you get from a senior VP.
Yeah, because I have heard different things from different companies. Some companies will, they will, the BD function will sort of take everything and run with it almost from start to finish. And then others, even though the sort of title on the business card looks the same, their job, the BD job at that company is to sort of just do the work at the request of like the president of that division or something like that. So the president of that division will say, go look for companies that fit this profile or add on this piece of technology. But if you approach, if you sort of cold call on that company's BD people, they may listen and take like an introductory meeting, but they're never going to sort of like, you know, advocate for you until the advocacy comes kind of from the other direction.
Totally agree. And I think where you get multiple voices, so I kind of talked about surgeons as an example. I also think investment banks and consultancies, if they know who you are, if you familiarize yourself with the practice leader at Slalom or the practice leader at Piper Henderson or whatever Piper's new name is, actually it's Janus Henderson, I think, but it's Piper. If they know you and you're in a market segment, all of a sudden they're quarterly walking into the room with the CEO, CFO, and presidents of these businesses and they're saying, oh, remember this company? And that recall can come in very handy down the line.
Great question. How do you, Mike, how do you avoid getting teased along by the strategics? Because I hear this a lot from startups. Um, yeah, we're talking, oh, things are going great, we're having a meeting with the business development people every few months, they want more information, we got a data room, and then nothing happens. It just goes on for years, you know.
Yeah. And there are some former employers of mine that are classic for doing that. 2 years to do a distribution deal. It's mind-numbing and it can be paralyzing. We used to call that at GE, the alligator roll. You take them all the way to the bottom of the Amazon, you roll them around until they pass out, and then you got the carcass to eat. I'm not proud of that by any stretch, but your best way to do that is go get somebody else that's going to move faster. And so this is the whole old adage of don't put all your eggs in one basket. If you've got one good— someone comes to you and says we need to do a distribution deal and here's why, and the strategy is smart, maybe you hadn't thought about it or you didn't think you were ready for it, go try that with 4 or 5 others that are of like size or smaller and see who moves the fastest. Because I do think, um, competition, just great, great competition. Yeah, yeah. And believe me, in business development, no one likes I'm sorry, we can't talk anymore. I'm under an agreement where I can't speak to you until I've got something else done. And then they've missed it.
They get real interested all of a sudden. Yeah, that helps. All right. Todd Martin is in the background. He's got a question. And then Raymond. See if we can hear you, Todd.
Sorry about that.
I got a lot of noise going on here. Hey, thank you very much for coming.
You can hear me?
Yeah, yeah, yeah. Great.
Thank you.
Perfect topic.
I love this question. It's with respect to tech partnerships.
It—
based on your experience, is it— is a tech partnership a good place to start for initial funding, or is there— or is that just— or are there better options for initial funding? Well, I think there's a lot of context needs to wrap around it. Tech partnerships tend to be one of my more favorite deals to do. And the reason is, I think those, if you break them down, probably have a higher success rate. If someone's coming to you and saying, we've got a little bit of tech here, but you do something better where the industry is going or is headed, uh, or is today, and we need you to help us get there, I think those, those come with, you know, good solid revenue streams. You can pay the bills, keep the lights on, employ the people, keep the benefits going, um, and maybe keep a little bit for your own, your own internal projects. So I do end up liking those because it ends up proving your technology inside of a larger platform can work. Um, so as a source of funding, that can be a, like I said, the OEM component earlier, where you're a proprietary company but you get a little bit of an OEM business because you've got a partnership going where you're designing, maybe building, uh, because they can't or don't have the capability or they don't have the funding to do it internally, which sounds weird. Big companies don't have the funding. Well, they do have the funding, it just got diverted to something, you know, bigger, sexier, so on and so forth. So I do like those, um, and structured well, I think there's a high success rate rate because you're— they're asking you to deliver largely what you know and usually, you know, can pay for it on the back end, not often stroking big checks up front. Um, but if they say, hey, we'll do a high transfer rate just to get you out of there, and as we scale we'll pull it back down, you can, you can fill your, uh, your bank account a little faster that way, as long as you can get— as long as you can stomach getting that into their hands.
Yeah, perfect.
Thank you.
Awesome.
All right, Raymond.
I agree with Todd. Perfect topic. Very, very helpful. And Mike, you and I have talked a little bit about this in the past, but it would help for people like me who are a little bit slow to try, try to understand what you've shared with me once before. When you do a distribution agreement with a strategic And that strategic then says, well, you know, what we're going to do is we're going to essentially, by helping you get into hospitals and so forth, increase your valuation. And therefore, we shouldn't be penalized by increasing your valuation if we have an acquisition. And so what kind of structure helps protect both parties? Do you understand my question?
Absolutely. And we see it all the time. And we, listen, we started Covidien Ventures, um, and I always say we, it's the royal we, it was being started by, um, some really sharp people under the leadership of Amy Wendell a long time ago, uh, to do just that. We, we felt if we created 20% uplift that we needed a 30% discount. Uh, and so I think there are a couple of ways. The easiest way is they do a direct investment. Another way is they find a way to loan you money, uh, that, you know, that gets you where you need to go, but it doesn't offset them. And then I do think there are ways that you can structure, um, if you drive— let's say I'm doing $5 million in revenue and you drive, um, big company, $5 million in additional top line, you double my business— there can be a way where, uh, you become a shareholder, or we find a way to get you some sort of discount. I've not done a lot of deals like that, but in theory, they're helpful. But I'd say the best way to say is, you know, you're— and if they're saying we're not doing equity investment, we can't get to consensus on a structure that works where dollar of sale here gets us 15 cents of equity in your organization, And again, there's all this monkey math that you can do with attorneys that'll drive you crazy and probably cost you a lot of money. But you basically say, listen, your value is seeing this hit the market, right? You have got insider view on the success we're having and you can sweep in with insider knowledge, basically due diligence over a commercial period of time. And you just need to move quickly. Some organizations don't move quickly. And so they can say that we can't do that.. But if they're saying, hey, we're driving, you know, we're driving a lot of the value for it, it's like, well, you either want it or you don't. Would you rather overpay? And I'll— this is a story from my past I was kind of dredging up while I was preparing for this— is often you would see the BD team beat people up to get the best price. And then later— and this is what Covidien did very well— they always called it the gentleman's dollar. They'd overpay for the asset because they felt it was a good fit culturally, strategically, you know, for the organization. And it just, it made everyone stick around a little bit longer and you got a better feel for the integration and a greater likelihood of success on the back end. Companies should be willing to overpay. Now, I think what we're seeing in ortho and spine is there's, and you know, Tiger Buford, your article today, I think there's a big component of that. In terms of there's going to be diverting towards efficiency. That means there's going to be less money for product innovation. But I do think there's going to be M&A to offset that. And I do think they should get into the mindset of overpaying a little bit just to get, you know, get the deal done in security. But I don't know that, and that's a company-by-company basis. I was lucky enough to work for a team that did that. So hopefully that helped to answer your question, Raymond. I know I went off on a tangent, but that, you know, if they say that, say, well, you guys can easily remedy that. Which route do you want to go?
Kind of a tangential follow-on, and that is trying to get good data and good comps to justify valuation, you know, whether it's a company-defined valuation or even in negotiations. So there's obviously the public sources, but I don't know, Tiger, you always say, you know, I'll eventually find out how much, I don't know, JJ Depew Synthies paid for expanding innovations. But I don't know, how do we— is there— are there sources that I'm not aware of?
Yeah, so there's— I think there's two ways to do that. One is you can go to a pitch book or a Crunchbase and you can probably with some work, figure out something. The problem you have with organizations is they'll always value it the way they value it. And that's a little bit of a black box to a company, but where they're getting a large portion of their data is from investment bankers. And those investment bankers are getting it from, you know, the same kind of financial subscription websites that are out there. So I think there's a couple of ways, to do that. But, um, you can ask the bankers for it, uh, you can go get a subscription to a data service that's not going to cost you an arm and a leg, uh, and you can kind of get there. But, you know, your biggest thing is, uh, if, if you've got a track record of announced deals— the problem with small deals, they don't all get announced. And what you want to know is, under $100 million in top-line revenue, what does J&J— what did they pay? And you, if you could get that data and they released it, you could probably say, hey, they 5 times revenue, but you don't get that data and they kind of shroud that for a reason because they don't need to. So it's a bit tough and it's something I'm happy to work with you on.
It's all apples and oranges too. Every deal is different, you know.
Yeah, you can find some similarities in deals that don't look like you, um, and you can find similarities in, in that, that, in deals that look exactly like you and dissimilar, dissimilar situations.
So Thanks, uh, Patrick.
Mike, do you have examples without probably naming company names or anything like that where, um, you kind of got told get into this space almost in a copycat manner? I think we see this a lot where like tech, you know, everyone brags like, oh, we've got— we're the only ones that have this type of technology. And I'm of the opinion that sometimes that's almost like too good to be true and that you sort of need like at least one other person in a given category or space. And, and, and sort of nurturing the, nurturing the category as a small company is almost as— not, you know, it's just as important sometimes as like developing your own company, because you can be sort of too out there that no one wants to take the risk. But as soon as like there's multiple companies out there, as soon as once somebody like one company comes along and gets acquired, then everyone else almost like overreacts and says like, now we need to be in this space because look at look at our competitors, they're doing this and this and this. Is that like— that's my perception. Is your reality match that?
It does, you know, at the highest levels. And I went through several examples there. Um, at Covidium, we went into neuro and peripheral vascular. We did diligence on Mirus. J&J snapped them up, and then we went and got EB3 almost immediately after. We did a couple of other small things too, uh, for R&D purposes. But it was the clamoring at the top. I can't miss out. Wall Street's looking at me like sitting on my hands. I've got to get into these high-growth spaces. Um, same thing happened. We saw a huge reaction when we did, um, energy-based— well, we did lung and GI navigation technologies, and then lung-based and GI-based ablation technologies. And it had J&J on their heels. And then they went and bought NuWave and a few other things, but they were, they were on their heels and they got yelled at. We heard that. Um, so I think there is a chain reaction once one goes in. So one in the market is good. You've got taillights if you want to follow them, but you've got to wait for the first one to pop, and, and then the others should be really quickly all over you. But, you know, those don't happen as much anymore. I feel like that happened a lot 20 years ago, and I think it's, you know, everything right now seems to be cardiac and a few other things, but each market's a little different too. So I think you'll— I do think that in spine and ortho, we're going to see a little bit more of of an M&A binge coming here in the next couple of years. I also think that's happening in small to mid-tier banking, which is, you know, small regional state banks. Because if you look at the supercycles, but no, I think that that can happen if you get one interested party and they go, the other one has to kind of answer. And there is friction in organizations. And if you're sitting in that space, you need to capitalize on that.
Yeah, that being said, I was part of the spine bubble at the very beginning by accident. I was on the BD team at Sulzer Orthopaedics when we bought SpineTech for $600 million in '97. And then that started, and everybody wanted spine. Yeah, it was, that started the whole world.
Yeah, that was the feeding frenzy. There's two types of feeding frenzies in my mind is one is, and, and one you'll, you'll like this. It's the segment, then the feeding frenzy happens, and then everyone's buying. And then there's the feeding frenzy around your organization. When the big companies start swirling around like there's chum in the water, like sharks, they are, you know, that's a good place to be.
Interesting.
So let's shift the topic from acquisition to sales and distribution because a lot of small companies, they lack the capital and the time to build a nationwide sales force. And they're always interested in distribution agreements. What does a good distribution agreement look like and what does a terrible distribution agreement look like?
Yeah, I mean, I think I'll go back to a little bit what was— and then hopefully I didn't skim over it. It's misaligned incentives. Economics are a huge thing. We've got, you know, I would say in spine and ortho, you've got— and this is changing a little bit. Gosh, like 5 years ago, I was looking at what Zimmer Biomet was doing with their direct sales force. Do we go direct more? Do we, you know, keep the distributors? The good thing about SpineOnOrtho is it has these great— this great distributor network system, especially in the United States. It's a different form in Europe, as you all probably know. This is a good thing, but they also charge a king's ransom. So you say, what's good and what's not? I'd love for, you know, big strong distributors to say, we're going to take a flyer on this, we're not going to charge you a lot, we're going to see if it goes, we'll share the economics on the back end. But often they're charging you right up front. I think that there's going to be more of an entrepreneurial spirit in those— some of those distributors and say, we're going to try you out. If it catches on like wildfire and we delight our customers, we'll work out the economics later. Um, but charging $1.01 to get in is tough. So it goes back to you know, misaligned economics. Um, and, uh, because what you can't do is have success at a distributor at the risk of putting your own company out of business. And I think that that's the razor's edge of spine and ortho, is we have great margin products, uh, but at the same time, you've got to pay that distribution channel so much money, um, that it can, it can stifle an organization's ability to launch new products or go into new markets, uh, new states, new territories, new MSAs.
That's good, good advice. Yeah, a lot of times I've seen companies— I was on the board of a company for a while, and, um, they did a partnership agreement with a bigger company, and what they found out is they weren't even trying to sell the product. It was, you know, they had like 1% mind share. You know, the distributors are, are— they're selling whatever they can to make money. They don't You know, and then you throw a new product in their bag they're not really that familiar with, you know.
That happens everywhere. And that's where I think you get into the culture. You get into, you know, what are the real reasons they want to do a deal with you? And if you find out it is, you know, it's the, you know, the visor flap on your car, it's not the engine or the suspension or, you know, the steering then you're going to be forgotten after that contract is dry.
Yeah. Mark, you want to talk about your joint preservation roll-up a little bit, or do's and don'ts?
I can talk about it. Give me a minute here. There's a train coming by where I am. I don't know if you hear it or not.
No, I can't. They do a good job on muffling these days.
Yeah. Here we go.
Joint preparation.
Yeah.
I feel like I'm out west. We finished the, over the weekend, the, the acquisition of our Cura Medical, which is a meniscal suture device. Mm-hmm. And we got another company that's an Austrian company that's in kind of a, a gait analysis rehab. Knee Pain thing. And the whole idea is to build a platform to generally dedicate to joint preservation.
Okay.
And we're getting a lot of enthusiasm about the concept, even though the physician community's not sure really which doctor's supposed to be doing this.
Yeah.
My, my answer to that is that this is consumer-driven, this is patient-driven. And that doctor probably doesn't really exist yet, or that sub, subspecialty, if you will. It could be a surgeon, it could be a physiatrist, I don't know. It could be a combination or just, it could be just under the umbrella of joint preservation of which that can include regenerative medicine as well as services and products. So, you know, we're just getting this going. We're trying to raise money.
Mm-hmm.
In this very easy to raise money environment. That we're in right now. Yeah. So any kind of advice like that would be, uh, any kind of advice that you've seen would be appreciated. Yeah. I do have one other thing I want to slide in at the end. Um, have you been, have you been involved in any deals that are just strictly software SaaS related that are in healthcare, or has it all been like medical device?
Yeah, so I did a turn in, I'll just answer that quickly. I did a turn in software between my medical, my healthcare stuff. So I was in software for quite a while and I've done for data and analytics software, machine learning software, software to put on our devices, several deals. SaaS, I think is, you know, it's getting a little bit of bad news in the press lately because of AI, but that was really kind of a lot of what we were looking towards to building kind of continuum of care ecosystem. Them. As a matter of fact, when we were at this lung business at, you know, Covidien Medtronic, we had a group spin out and basically did a kind of a full integrated care pathway, which included inputs from all kinds of different data sources. So that was more application than it probably was strictly SaaS. But yes, licensing is a little different, you know, deals are a little different, the multiples are different, the companies, they're different. But yeah, I've worked in those, they're kind of refreshing in a lot of fronts, but you know, you don't often need the FDA approval on a lot of those things. Now that I could be wrong because I don't know the company, but going back to your question on a kind of a holistic roll-up and I, the first thing that really comes to mind and I don't know how you're encapsulating this, if it's a, we got a box that we drop off with all kinds of different, you know, products and services and outsourcing and keeping that patient inside of that clinic. Or if you're actually doing the clinics. And I— the one thing I would say is either way, there are corollaries, most of them globally, on about roll-ups of, of— instead of we do the one— we've been historically great at one-stop shops. You get your knee done here, you get your spine done here, you get your pain over here, you get your primary care here, you get your rehab over here. You know, if you're trying to pull a lot of this together, there there are great examples in Europe where they've brought together bariatric clinics or other types of clinics. I always thought that China was working towards getting day centers pulled together where you could show up and they would do the diagnostics there, they would do the right procedure for you, they send you home. So I think there are other examples in the market without knowing the full depth of this market. It's hard for me to really pinpoint it, but I think looking at the corollaries that have been done in other market segments, and then especially the ones that fail. And then, you know, and then really trying to say, hey, it's been done here successfully, we want to match that, I think is usually a good way to indicate or find that, you know.
The basic pitch is, Mr. Big Ortho Practice, you do not have a joint preservation program, right? You're gonna lose patients. To somebody that does, or the QC Kinetics, or whomever, they're going to leak right and left and you might not get them back. That's the pitch.
Yeah. And so what they're saying is, do I have to build out additional infrastructure or pay additional money to address or attract people earlier in the cycle that I really probably don't even know yet to make sure that they come? And so they, you know, if I'm a physician or a surgeon and I'm a senior partner and I'm I'm going to retire in 2 years. I look at that as coming out of my cash flow, my restricted units on my payout every year. If I'm young and I'm embracing robotics and I want to treat that patient with all kinds of different therapies before we do a partial or before we do a total knee, as an example, and then you could say, I've grabbed them earlier, I've generated revenue off of them, there's no way they're going anywhere else. I will have them for that joint replacement procedure and I have faith in that. But I think you've got to fight the people who are the big shareholders and the ones that see the future. They're just not in bigger numbers as I'd like.
Good insight. Thank you.
No, yeah, you bet.
Great, great insight. Patrick.
There we go. Mike, aside from, you know, like someone who like literally is lying or, you know, like actual sort of fraud or deception, what are some some kind of like interpersonal characteristics that over the years just always like really bothered you? Like, like personality traits or styles that like, that got on your, your, on your nerves, where maybe you were sort of polite in the meeting, but, but in the back of your head you were just sort of rolling your eyes and saying like, okay, I've seen this way too many times.
Yeah, I mean, God, the cast of characters, I could, I mean, I could fill a prison with them half the time. Um, and yes, I've been deposed several times because we got into deals with bad people. That stole money and so on and so forth. Nothing that I ever got in trouble for. But, you know, listen, I think it's just— I would apply it to normal life. If these people are, you know, overly arrogant and brag too much and, you know, are demeaning to other people, have a superiority complex, those are your freaking greatest red flags. Where I've kind of shifted my business— this is a small— and I'll continue on. I have promised in this chapter of my life and career, I will only work with people I like because there's so many people out there that are just insufferable to work with. You know, there's the folks that are defeatists, can never get anything done on time, you know, can't be trusted. So I think it kind of comes down to, is this a person that you would, you know, and this was a Deloitte thing, I am going to work an 18-hour day with you and I don't want to kill you on the 3-hour flight home after afterwards. Is this someone you can really kind of be with and hang out with? And is it, you know, have a beer, you know, you travel Europe together as families, or do Fourth of July together? No, you don't need that. And matter of fact, that separation time sometimes is helpful. But I find extremes in personality, uh, usually will show you, um, what you're dealing with. And I think, well, is there's, there's kind of a saying that Maya Angelou had, If people, people, you know, don't look away, and I'm going to butcher this, you know, when people tell you who they are, don't, you know, don't, you know, listen to them.
Yeah.
Um, that's one. And then the other thing is you can often tell in the process of getting to know someone, doing a contract with someone, if the, if the, if the engagement period is going to work when you're married. Now, married can be doing a distribution deal, or it can be doing an acquisition, large acquisition, a position you folks are in. You're going to be gone Anyway, um, so you can— that's fine. Um, but they're going to show you their stripes throughout. Um, and you know, there's, there's people I work with today on behalf of some of the companies I advise, and we got to work with some weasely people, and you don't like it, but you do it and get the deal done. The deal's probably going to be just fine when you're done with it. But anyone who's too outside of the bounds and just has an exaggerated anything in their character and it just, you know, give me the heebie-jeebies.
Got it. Okay, we're kind of bumping at the top of the hour, so Mark Yap's going to bring us home here.
Thanks, Tiger. Yeah, Mike, thank you, uh, for sharing all of your, uh, all of your, uh, insights.
Uh, I have a, I have a what may be a basic question.
Where in the timeline of developing an idea, uh, would you suggest reaching out to strategics to just begin conversations? Is it once you've secured IP? Is it when you've got functional prototypes? Is it when, you know, you're well into validation testing?
Is it all of the above?
It sounds, it sounds like it may be like all of the above, just starting a conversation and then like you said, providing updates along the way to kind of keep, you know, to keep your space, you know, in their mind or online.
But I, so Mark, you're tapping into a really good question. And I have found that, I found organizations to do exactly what you just said on all of it. And I don't know if one is right or wrong, but we've had organizations come up and say, hey, we've got relationships inside of, you name the company. And we just want to validate that this is a good market space. And usually they catch us at a conference or something easy. They don't really fly to us necessarily. And if you can validate that that's a market space that they're definitely interested in and they're truthful with you about it, what you want to do is validate their strategy and intent. Is this still at the top of the pecking order in terms of investment for your organization? Or, you know, is the next new shiny thing come along and this is not getting investment? Because what you don't want to do is go down a development cycle for yesterday's product because it's really hard for them to kind of claw back unless they were number 1 and now they're number 3 and it's a real thorn in the side of, you know, some executive and they want to get you done. But I think validating early on, even without exchanging design, uh, are you still interested in this space? Um, what are the things that products need to do better? What are things the procedure need to do better? What's your voice of technology? What's your voice of customer? Validate off of those because they've largely spent spent money on that. And then I would feed them along the way. And then, you know, once you've got your patents filed, right, I mean, there's prior art is a thing now, right? Um, you know, I'd say that's kind of the safest thing. And listen, I had a great R&D leader that he and I, he'd say, we've got this meeting with X, Y, and Z tomorrow, I want to lay down 3 patents in the next 48 hours or 24 hours and, um, and submit them so we don't have a problem talking them. We've done that before just to protect ourselves and the company. Um, but I would say, yeah, I mean, the keeping the, keeping the updates, you know, all the way through with those potential buyers, I think is always bright. But your timing has to be, I think, comfortable where you are and releasing that information over time. And, you know, folks would be in deep discussions with our ventures people. The ventures people will bring it to the business The business would say, you know, "Hey, BD, what do you think?" And then we would start working and then you'd have a good quorum there for attention and therefore investment and therefore, you know, getting people really excited about the technology. And that's what you really want is you want champions in each one of those functions. And I think there's a perfect way to do it in each organization. I don't know if there's a perfect way to do it that matches every organization, if that That makes sense. It's kind of like Patrick brought up earlier. Each organization is a little same or a little different. Excuse me. They're not all 100% the same. But I think you're thinking about it the right way in terms of letting a little bit of the genie out. You know, hey, it's 3 wishes. Hey, it comes out of the bottle.
But I'm not—
Yeah.
Building intrigue, right?
Yeah. And I think, you know, done with respect and done with candor and done with You know, not being braggadocious, going back to again Patrick's question about, you know, you're not going to walk in and say, I have solved all the problems in this disease state, right? You know, those people are insufferable, and BD doesn't love to pick up the phone for that. But I think you can, you can find a nice way to thread that needle. And it's, I think it's a, it's more of an art around your science.
Yeah, thank you. Thank you for that.
Yeah. We're at the end of the hour. If anybody— we can say goodbye. If anybody has a burning question, we can keep going. This is obviously— we could do another hour probably.
Yeah, come back again anytime, Mike.
Yeah, no, happy, happy to. And, you know, Tiger, if there's nothing else, I'll just— I'll end as well before you end. Um, yeah, no, that's—
you're good. Thanks, it's been a great hour, Mike.
Uh, no, thank you. And again, you know, folks, I, you So love doing this stuff, love having these conversations. If there's things and you want to bounce things off of me, feel free to reach out. LinkedIn's the easiest space, and I think Tiger made that available. Tiger, thank you. Thank you, Raymond, for the recommendation to Tiger. This has been a ton of fun for me. I love doing this stuff, and the best to you all and in all of your endeavors. And if we run across each other, I look forward to it.
We'll see you again, Mike. Okay.
All right.
Thank you, Mike.
Thanks, everyone.
More from Tiger


BoneChat #145 - ASC Robots, Direct-to-Patient Marketing & Ortho Startup Reality

BoneChat #144 - Defining the Standard of Care for Orthopedic Tissue Preservation & Restoration

BoneChat #143 - AI-Driven MedTech Sales, Startup Traps, & Orthopedic Commercialization


BoneChat #142 - Fastest-Growing Ortho Segments, Reverse Shoulder & Joint Preservation Rollups

BoneChat #141 - Disrupting Surgical Visualization: Single-Use 4K Scopes with Richard McKillop

BoneChat #140 - Transforming Knee Rehab, Patient Experience, and MedTech Go-to-Market