Preparing Yourself Early to be a Practice Owner
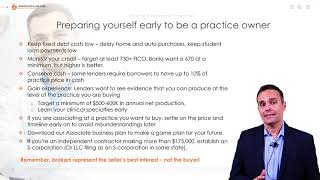
Greg explains how associates can prepare to buy a practice: get your credit score above 700, save cash reserves equal to roughly 10% of the purchase price, and time large personal debts before you buy. Banks want to see your practice cash flow cover your personal fixed costs plus a 25% cushion. Hire a CPA and attorney to handle the deal, not just a broker.
Chapters
Hello, my name is Greg. And today we're going to talk about how best to prepare yourself for being a practice owner as an associate. And this is one of the things that you don't really get taught about a lot during dental school. So we're going to go through some of the key points. The first, most important thing that you probably need to, to get into practice ownership is financing from a bank. And banks, as you can imagine, want to lend to people who are safe. And the way that they evaluate that is that the cash flows that the practice sends off through its operations are enough to pay your living expenses and them back, plus some cushion. So.
The way that they measure that is obviously to look at the practice financials, see how much free operating cash flow is left over after everybody is paid, the employees and the rent and whatnot. And then if that is enough to cover your fixed cost, mostly your fixed mortgage payment, home payments, student loan payments, and them, and leave 25% left over just in case there are dry months, so to speak, or slow months. So towards that end, it's a good idea if, whenever possible, to delay big purchases that require financing to until after the practice purchase, because those fixed payments, debt payments, ding you more in their calculation than some that are more flexible, such as rent. So if possible, try to defer a home payment or that big auto purchase until afterwards. Similarly with student loan refinances, whereas it's a great idea if you can refinance out of a 6 to 7% student loan.
Package into something that's around 3%, which is what's possible today, you probably want to delay that even though it's going to save you money. If you're on IBR income based repayment, which caps your payments at a lower rate than they would be if you refinanced and had to pay full boat as a part of a private loan. Because under IBR the government is picking up some of your interest or at least limiting your payment. So keeping that payment low is also going to make the bank's financing formula work. Next, banks are going to look at your FICO score, otherwise known as your credit score. There are three credit bureaus, United States TransUnion, Equifax and Experian, and they all report credit scores that are all more or less similar. It's called FICO score. At a minimum, banks will probably look for a 670, but it's best to have it significantly over 700 if you can. It's free to check your credit score and I would recommend it for anyone doing it all the time. And there's a free app from the makers of TurboTax and QuickBooks. The company is called Intuit and the app is called mint like the leaf.com and you can have it on your phone but. And it's a great thing for alerting to you if your credit score has changed or if there's been a new application for credit. Another free app and website is called credit karma.com and that checks two bureaus and that's good to have as well. Just to monitor credit score. A few things that you can do to get your credit score up are obviously pay on time. That's one, two is you want to have what's called low utilization of your available credit. It's kind of like your score goes up and lenders want you more the less you need them. In other words, it's better to have a $10,000 credit card with a 0% or $0 outstanding balance than have that thing maxed. Because by having a zero balance shows that you don't really need that card and they want you more. And that makes your credit score, your credit score go up. Next, you want to have longevity in your credit history. That means that the length of your accounts from the time they've been open is as long as possible. So it's not always good just to open a card, get the airline points and close that card because it lowers your longevity score. Credit givers want to know that you're going to be on the hook paying them tons of interest for a long time and the length of that score shows and the the fourth main thing that affects your credit score is how many inquiries. And this goes back to the more you need them, the less they want you philosophy about credit. If you're going out and applying for a loan here and a credit card there and a house payment here, they're going to think you're desperate for money and the lower credit score is going to go. Now, most practice purchases don't require money down. However, banks want to know that you've got some cash in reserve. And pre pandemic, some banks were looking for about 10% of the practice purchase price in personal cash in your bank account just to show that you had the wherewithal to come in and finance practice during an emergency. And that may change now a little bit more after the pandemic because when there's uncertainty, banks pull back and they make their lending restrictions that much more difficult.
Next, banks want to see that you can perform at the level of Production that the practice that you're targeting for purchase is already performing at. Put in other words, if the practice you're buying does a million dollars of collections, they want to see that you can produce somewhere in that neighborhood. If your production has only been 200,000 for the past year or two, they're going to wonder if you can work at that speed or produce that kind of revenue for them to get paid back.
If you. Now, there's a lot of different ways to buy a practice. One is through brokers, and.
We like to be honest, brokers are.
They work for the seller, first of all, and that's not always set up front. They get paid by the seller, they advise the seller. They have their duty to represent the seller. They do not represent you unless there's an explicit dual agency agreement signed. But at the end of the day, the buyer is typically not paying the broker, even in dual agency. And guess who they're loyal to? The people that they're paying. And even more so than the person that they're paying, they're loyal to getting the highest possible sale price because what they get paid is on average 8 to 10% of the sale price of the practice. So. So we advise you to get someone like practice CFO or a CPA to represent you in conjunction with an attorney who's seen deals and can represent your interests exclusively. If you're looking to buy a practice from a broker, there's going to be a lot of unknowns, kind of like a blind date sometimes. And we've been in situations where people will buy a practice and never have had stepped foot in it during operating hours. They've never met the patients, they've never met the staff, and it's a big unknown, and that's risky. The more ideal way, if possible, is to associate there. That eliminates a lot of that risk of the unknown. You get to gauge the personalities of the staff. You get to look at the equipment and test it out and see what needs to be replaced. You get to gauge the patients in a good demographic that you know you're accustomed or strong in dealing with.
All these things are good to get exposed to, but you don't want to work as an associate for too long without sort of having the talk, so to speak, with the seller about where this relationship is going and probably getting that in writing. Oftentimes when sellers or, you know, more senior docs bring in an associate, it's with an eye on the exit and the feature future. And it's better within the first few months. To have that talk.
In all honesty, you probably want something of a promise ring, so to speak, early on. And the legal terminology for that is just a letter of understanding. And all it does is it outlines the points about when or is this practice going to be sold? Is all of it going to be sold? How is the purchase price going to be calculated? What happens if, if this associate helps to double the value of the practice? Are they going to have to pay for what they've contributed? This should be ironed out. And then when the time comes closer to sell, that's when you will enter into a letter of intent, which should be drawn up by an attorney. It's only a couple of pages usually, and that's a much more serious document where you outline the price and some of the allocation of the price, which I'll talk about later. We actually have an associate business plan that you can download from the Associates on Fire website. And we encourage you to do that because not so much that it's for anybody else, but it just forces you to realize you're becoming the CEO. And not everybody should be a CEO of a business. And what it's going to entail in terms of being the human resources director, being the marketing director, being, you know, keeping a CFO accountable, even if it's a fractional cfo. And to think about, you know, is the cash, how much cash do I need to live, get ahead, pay off my debts?
One last piece of advice as you prepare yourself to become a practice owner is there's probably some tax savings. And please speak with your CPA about this. If you form yourself an llc, depending on the state, or. Or an S corporation, different states have different requirements at about $175,000 of gross income. And the reason is because of the corporation, you can divide your income between a W2 salary, you become an employee of your own company, or just net profit. Both streams of income, W2 or net profit are subject to income tax. No way around that. But only the W2 is subject to Social Security and Medicare FICA tax, which, if you limit your W2 to a reasonable amount, can limit your FICA tax. Because if you're just a sole proprietor.
All of the income is taxable for both income tax and Social Security and Medicare. So having an S corporation is a great way to do that and limit that expense. And it also gives you a little bit of legal protection too, or separation of your personal assets from your business.










