The Practice Purchase Initial Analysis - A Case Study Part 2
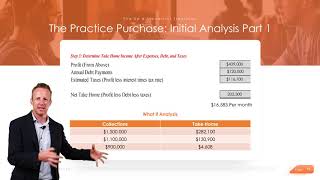
Wes Read analyzes Dr. Devlin's $1.1M dental practice asking price. After normalizing the income statement, he finds true operating profit of $439,000 and calculates the buyer's take-home at roughly $202,300 annually, or $16,583 monthly, accounting for debt service and taxes. Collections matter hugely: a $1.5M year pushes take-home to $282K, while declines can crater it.
Chapters
Art Associates. Let's continue on. In our analysis of Dr. Devlin's practice, we've now decided or determined what is the true profitability of that practice. $439,000. But what does that mean for you exactly? After you pay the debt and the taxes and take home for you, what does that exactly mean? How does that translate into real dollars in your personal bank account? That's going to be the point of this discussion as well. As is the price reasonable based on that $439,000. Now, stepping back, just to reiterate, that whole process was what we call income statement normalization. Taking the numbers as you got it, normalizing it, filtering out, you know, the stuff that's not going to be applicable to you, determining what the true profit is. And now we have a number we can actually do something with that's called income statement normalization. Now we're on to step two here. Determine if the asking price is reasonable. Well, what's the asking price? The asking price was 1.1 million. What. What were our collections? Well, our collections were 1.4, but let's take out the patient refunds of 50,000, so it's really 1.3.
So price to revenue is simply divide the price, which is 1.1 million, by the collections, which is 1.35 million. So 1.1 million divided by 1.35 million is 81%. And as I mentioned in our assumptions, if you look down below on the slide, you'll see that it's between the second to the bottom line, 70 to 90% profit, price to revenue is the industry range. Again, that's going to be a little bit unique to geography and a few other factors, but all things considered, somewhat of a reasonable range there. So 81% falls pretty much right in the middle. Might be in some areas a tad high, for sure, but that's based on our numbers here. That's going to be a fairly reasonable number. Now let's look at it from a profit standpoint, not a collections, but a profit standpoint or operating income standpoint. Price to earnings, which is the price divided by the profit, which we arrived at from step one. Now, we had to go through that whole charade of activity to find out what the true profit is, which was $439,000 wasn't the 67 that was stated when we got the financial statements. We had to do all the add backs.439,000. So 1.1 million, which is the asking price, the sale price divided by 439,000, which is the operating profit, the income, the net income is 2.51. If you look at the very bottom price to earning industry range 1.75 to 2.75. So it's on the higher end for sure. Remember the overhead was a little bit higher at 67% in this practice and therefore it is on a little bit on the higher end but it's still within range. So it's not out of the question. Then you got to look at other factors. Is this a practice you are already having some doubts about or is this something you absolutely want to decide whether you want to move forward or perhaps even try to negotiate the price a little bit more? So is the price reasonable? Yes or no? I'm going to say yes based on the context of these numbers. Now let's go into step three. Determine the take home income after expenses, after, after debt and after taxes. Well remember from step one we arrived at what's the true profit before paying any of those? Your operating income. That was 439,000. Now what's our annual debt payment? Well in the assumptions it told us $120,000, 10,000 per month. And what are our taxes here? See this one you probably didn't get right off the bat but that's why you're taking this module to learn. Well, your taxes are going to be your operating income. Less operating income, less the principal, I'm sorry, less the interest on your debt. Because that 439 is before paying your interest on your debt. Now you have all your tax deductible overhead up above and you now pay your debt of that amount. 50,000 went toward interest. So you're going to take 439 less than 50,000. You're going to multiply that by your tax rate which was 30%. Now I'm leaving something out here which is called depreciation and amortization. I get to that in another module. I'm keeping things simple here. Depreciation and amortization would drive your taxable income lower. But that's how you would arrive at your estimated taxes for purposes of this.
Of this sort of project, of this workbook that we're doing to finally arrive at your net income or your take home income. 439 less. 120 less than 116,700 equals $202,300 per month. That's $16,583. That is the number we were trying to get at. What does this all mean? What is my take home after all the dust settles and is this going to help me pay for my student loans and my rent and my family and everything else, my entertainment, travel, etc. Now I also do a little what if analysis here, just for fun. Actually, not just for fun. This is important that you got to know that if your collections fell in the practice and or if they rose from what the seller had, how does this affect your take home? Well, I just ran the numbers just to give you some examples. If the collections went from 1.35, which is what they are now with Dr. Devlin, up to 1.5 million, your take home would go from 202,000, which you can see above on the screen, up to 282,000. So it goes up by about $80,000. So you had $150,000 increase in your top line and over half of that went to you. That's because most of your costs in the dental practice are fixed costs. Once you pierce your fixed cost, the larger share of new collections goes right to you. It's just the nature of a dental practice. That's why it's so important to get your collections past your fixed costs and into a profitable territory. I talk a lot about that in our break even modules in fuel cell number three. Now if your collections were to drop from 1.35 down to 1.1 million and all your overhead stays the same, other than your labs and supplies, those are going to drop, then you're going to take home 130,000. So now you see a $72,000 reduction in your take home. That's a lot with not that much of a drop in your collections. That's why you've got to maintain those collections. Really important that you work extremely hard when you buy that practice to maintain those collections. You might see a little dip, very common. But then you get it back to where it was when or even better if you worst case scenario, this thing drops down to $900,000 from 1.35 million per year down to 900. Now your take home is 4,608. That's not a good place to be in. So I wanted to show that to you, not to scare you, but to know that it has an upside. If you collect more then a good portion, the majority of that ends up going to you. And if you collect less, then sort of the opposite happens as well. So this was a very in depth module about normalizing an income statement. Now there's one other thing though before I end that I want to show you which is what's your total compensation? Well, this is step number four. What's your total compensation? So we calculated that your total take home is 202,000, which is your profit less the debt, less the taxes. So your total take home is 202. However, in the practice, because you paid $120,000 in debt for the year and 50,000 went to interest, that means 70,000 went to principal. So you paid your debt down by $70,000. If you maintain the collection level, then the value of the practice stayed the same, and now you've created equity in your practice of 70,000. In the same way as when you paid on your home debt, you build equity in your home and you just built $70,000 of equity in your practice, such that if you went and sold it the next year, you have a $70,000 of new money, you're going to pay taxes on that. But of new money, that's called what we call equity income. And so if you add the equity income to your total take home, you're looking at $272,300. Not a bad income for a young dental associate who is just starting off in their career. This practice has some good things I would take away from it. You want to compare it to other practices that you're looking at as well to decide is this the right practice for you?










