Texas Home & Auto Insurance Explained for Busy Moms
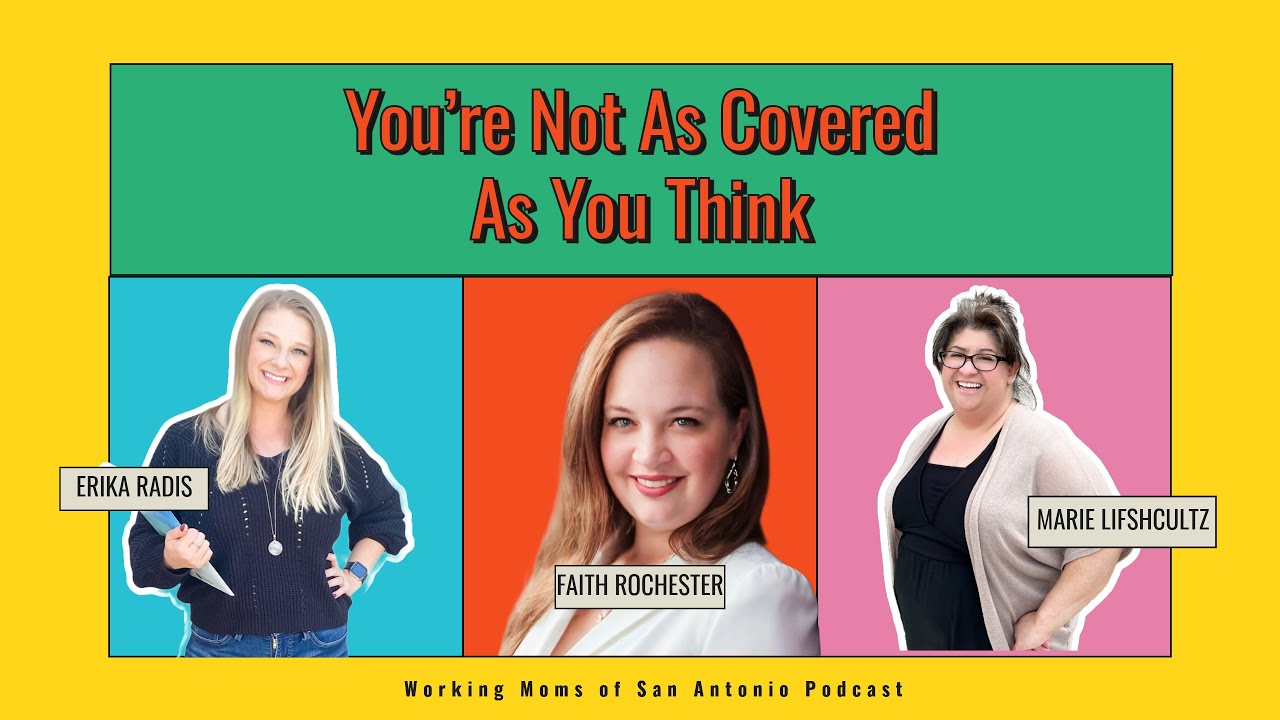
Faith Rochester, founder of Rocking R Insurance, breaks down auto and home insurance for Texas families. She explains why "full coverage" often doesn't cover your loan, how roof damage affects homeowner rates, and why bundling policies saves money. An independent broker can spot gaps in coverage busy parents miss.
Chapters
Welcome to the Working Moms of San Antonio podcast. We're your host, Erika Radis and Marie Lifschultz, a realtor and lender here in San Antonio. But most importantly, we're working moms just like you.
This podcast is all about creating a space where we can come together, share stories, and learn from each other. We love connecting with local moms in business here about their journeys and how they're balancing it all. Because let's be honest, it's not always easy, but it's so worth it.
Before we dive in today's episode, we're excited to share some big news with you all.
Our business community and coworking memberships are officially open. Whether you're looking for a supportive community of moms in business or need a beautiful space to work and grow, we've got just what you need here at Working Moms of San Antonio. You can visit the link in our show notes or workingmomsofsanantonio.com/membership for more info.
Now on to today's episode. Grab a cup of coffee, settle in, and let's get started.
Welcome to this week's episode of the Working Moms of San Antonio podcast. Today we have a guest on, Faith, and she is with Rocking R Insurance, and we're gonna talk about all things insurance. So I'm gonna turn it over to her.
Yay.
To introduce herself a little bit more and share a little bit about her business.
Um, my name is Faith Rochester. I recently opened up Rocking R Insurance. Um, I was doing some other things for for a while working for other people.
Yeah.
And then I decided to work for myself, which is always good.
We love that. Yeah, we do love that.
I love being my own boss. It's great.
Yes.
Um, yeah.
Um, what made you decide to open your own?
So I had started doing insurance in health and life specifically about 6 and a half years ago. Um, working for a company that's based out of Florida. And then I took a step back from that. I still did it a little bit on the side, but I was like, this whole 100% commission thing is kind of rough.
It's a little hard.
Yeah, it's a little hard.
Sure.
Especially because I had a newborn and other kids in school, and I was like, this is just— it's just rough.
Yeah.
So I took a step back and I became an adjuster with State Farm for a while, like one of those people you call whenever you have a car accident.
Yeah.
And they decide Yeah, your car actually is broken and we're gonna pay you to fix it. Um, and I did that for about 2 and a half years and I was like, this is not for me. This whole working for somebody else thing is, is just not. Um, so I talked to my husband a lot about it and he was like, you should quit. He was like, just do it. Just quit.
Yeah.
Uh, which is great. I love that in a husband.
Yeah. My husband has also said that to me in the past.
Just quit.
Yes. And it is one of my favorite qualities about him.
Yes. It's, it's amazing. It's an amazing quality in a husband. Um, and I was like, Get that all, you guys, right? Like, pay attention. Yeah. That's, that's what you need to do. Just tell 'em, just quit. Um, and then, and he's honestly, he's been one of my biggest supporters, which is great.
Yeah.
Um, and so I did, I, okay. I quit and they were very shocked cuz they had just given me a raise and they were like, are you sure? And I'm like, I'm, I'm sure I'm, I'm quitting. And so I quit and I refocused. Back on insurance. I started reaching out to my old clients. I was like, hey guys, I'm still here. Like, been dabbling in it for the last 3 years, but we're going all in. Um, and then I decided to go ahead and add, um, not just health and life, but to become a full-service agency. Okay. So I added in home and auto and commercial insurance as well. I also do pet insurance. Not very often, but just throwing that out there.
That's a new thing right now.
So like really you do all the things.
All the, all the insurance.
I do. Uh, most people hate insurance. I decided to be weird and make my life all about insurance.
It's great. Yeah. Mm-hmm. Yeah. Well, before we, you know, started recording here, we mentioned, and this is so true, I don't understand how insurance works. I know that I pay for it. I know that we need health insurance. I know that we need, and I, we have life insurance, we have all the things. And do you feel like a lot of, and it must be a lot of your Um, job is, is educating people because they are like me and they really have no idea what they're even paying for.
Yes, definitely. Um, like I have clients come in and they're like, I'm 50 years old and I've had health insurance this whole time. What is a deductible?
Yeah.
And then they're like, and then what's this out-of-pocket thing you keep talking about?
Yeah.
Um, and so a lot of my conversation usually, especially the first conversation I have with a client is discussing like, this is what this means, this is what it is, this is why we care about it.
Yeah.
And it's not just the premium that you're looking at every month because you can be paying a lot of money for your premium every month, but your coverage actually isn't that great.
Oh, that's interesting.
That is very common. How important it is to have someone to sit down with you and talk with you and explain what the benefits are. Like, you don't get that from a 1-800 number.
No.
At all. No, you don't.
Like you, you might not even understand the people you're trying to talk to. Yeah. You know, but having someone to talk with you that's local and knows your environment, your situation, and have someone hands-on is so important. Not only in the, you know, insurance industry, but just in general, especially about things that you don't learn about in school. No one teaches you how to have insurance.
Yeah. Yeah.
And why— No one has taught me. No.
They should. They should have a class on insurance and taxes. They should. Yeah.
Just basic life skills. Like, hey, this is what it means. And what is a deductible? What's a high deductible? What is that?
Yeah, I know one of the things when I was an adjuster, people would call in and they'd be like, well, I have full coverage, so you should just pay for my car that's been totaled. And that's not how it works. We're not going to pay off your loan. We'll— they only pay what your car is actually worth. And if your car— if your loan is more than that, they're not going to cover the remaining balance. That's why you have to have gap insurance.
And I was actually talking with a client just yesterday about that, and that was reviewing a credit report, and there is a a large derogatory on their credit. And I asked what happened, like, oh, we totaled the car and the gap insurance didn't pay for it, so we went and bought another car and it just— it's there. The insurance should have covered it. I'm like, did you see what was— like, what? Doesn't just do it because you said so.
Like, you have to understand the coverage.
So, but yeah, and, and so it's affecting his ability to purchase a home because he has this large collection on his credit because the gap insurance of whatever he thought he'd had, he did not have in place.
Yeah.
So he's like, oh well.
Well, because especially for auto insurance, people will, like an adjuster or not an adjuster, but a broker will say, hey, you have full coverage. And so they just assume that that's what that means is that they'll pay off the car. What that actually means is, is that you have liability and comprehensive. So if you get in an accident and it's your fault, your insurance will cover to fix your car if it's fixable. That's what that means. It doesn't mean they're going to pay off your whole loan for you if the car is totaled. Unfortunately, it would be great if it did, but—
How does it work if you get in an accident and it's not your fault?
So if you get in an accident and it's not your fault, hopefully the other person has insurance.
Yeah.
Which they're legally supposed to. But here in San Antonio specifically, there's a huge population here that's not covered. They're just not insured. Most of that has to do with car rates. Actually, that is driving up the premiums in San Antonio is, well, specifically, but for all of Texas really is because we have such a large population here that doesn't have coverage at all. So hopefully they have coverage. If they don't and you only have liability, which is all the state minimum is, is liability, then your insurance company is not going to fix your car because it's not your fault.
Oh, that's interesting. Mm-hmm. That makes me feel like we need to look at our car insurance situation. Absolutely. Because for us, and my car's not very old, just a few years old, um, but we have paid it off now. And so thankfully, and so, um, I feel like my husband was like, maybe now we just need liability. But I feel like no, maybe we do not.
No. I mean, I, I would think that you would still want full coverage if that made them the word. What's the word that you used?
You want to have, um, comprehensive.
Just because it's your only vehicle. And if it gets totaled, what happens if you only have liability?
Um, then you don't have a car.
You don't have a car no more.
Yeah.
So unless you have the funds to self-insure and buy another car— no— then you're in trouble.
Yeah.
Well, no, but no one explains that. Like, liability, they give you those options when you're looking like, I just need something inexpensive. Oh, we'll just go liability. And you're like, oh, okay, great. And then you don't have a car in 2 months if someone hits you and They don't replace it or, yeah.
I mean, so technically what you could do is you could sue them personally. Oh, but the thing is, is if they don't have car insurance, they probably can't afford car insurance. They probably also can't afford to pay to replace your car.
Right. Yeah.
Out of pocket.
You're just suing and there's nothing to want even. Yeah.
So there would be a judgment there, but there's no money. You can't get blood from a stone. Yeah. It doesn't work that way.
My mom would say that.
Yeah.
Uh, yeah.
An old soul.
Like, but she was just saying like, you can't get, or you get blood from a turnip.
Like, you can't.
It's true.
Um, so yeah, I would, I would definitely look at that. I know my husband's truck is old. It's like an '07, but he loves that thing. It's a Toyota. They run forever. Um, and his is paid off completely. And they always, before I started doing auto insurance, they would be like, oh, well we can just drop it down to liability. And I was like, absolutely not.
Yeah. Not if he needs it. I mean, like, I wouldn't understand like a, like a, a recreational truck, like something that you just had.
If it was like a farm truck and it was on the farm. Yeah, sure. And that's all we drove it for. Like he didn't need it for everyday use. Sure. Liability. But, uh, cuz all liability does is it just fixes the other person's car.
I see.
So it's not even if you have liability and you get in an accident and it's your fault, they're not even gonna fix your car. They're just gonna fix the other person's.
Yeah. I mean, I feel like in our circumstance we were shopping around for, um, homeowner's insurance.
Mm-hmm.
And, um, we ended up going through USAA. Mm-hmm. Because they offered us a really good rate. Um, and the guy was just like, but we can get a better rate if you just like throw your car situation in here.
Yeah.
And of course we were like, okay. And then really didn't look at it. I mean, how common do you feel like that is?
Very.
Yeah.
Very common. Um, bundling does usually get you a cheaper rate.
Yeah.
Which is great. I mean, plus there's only one bill to worry about instead of having to like make sure you do two every month.
Yeah.
But yeah, I would suggest everyone look at their car coverage. 'Cause like, I know for me, especially with being an adjuster for so long, I would always have, of course, the state minimum of liability.
Yeah.
Plus it's $30,000 for medical insurance and bodily injury and to cover property damage, which would be the other car. So if the other car is worth more than $30,000, they're also not going to pay more than that.
Mm, gotcha.
That's it. So I also carry comprehensive. So if it's my fault, they'll fix it. And then I carry underinsured and uninsured. So if I get in an accident and they don't have coverage, my insurance company picks up the bill. If I get in an accident and my car is worth more than $30,000, which it's not right now, but if it was, Um, and they were only carrying state minimums, their insurance company would only pay $30,000. And then if mine was, say, worth $36,000, my insurance company would pay the other $6,000 to fix my car. Yeah.
And most cars aren't $30,000. No. And you can't even get a used car.
Exactly.
Yeah. Like it's—
Mine's like $29,000 right now. Like it's super close. Uh, but when I bought it, it wasn't.
Yeah.
Like it was more than that. Um, and then I also carry PIP, which is extra personal injury protection, which will pay out no matter whose fault it is, they'll pay whatever you pick. Like I carry $10,000. And so that's just in case if I get in an accident, everyone in my vehicle gets $10,000 to pay towards medical bills. Now it's not like a $10,000 check, but like if you end up taking an ambulance ride or going to the ER, that adds up real quick.
Sure.
Like you're going to meet that $10,000 and you turn those bills in and they reimburse you for those bills. So it's on top of the bodily injury that's already being paid out by whoever's vehicle is at fault.
Well, I got really scared one time. It was several, several years ago. It was a rainy day and I remember I was headed somewhere and I had ran to my car, right? So I, to get outta the rain. So I had to get in and my glasses had gotten wet. So I was at a stoplight and I was, my glasses had water drops. I took 'em off and I was trying to dry them off and I ended up dropping my glasses on, like, on the floorboard. So I leaned over and my foot slipped off my brake and I bumped the person in front of me. I'm like, oh my God, I'm so sorry. Like, I was too close, whatever. They, 6 months to a year later, they were still claiming medical and stuff. Yes, I'm serious. It was a young guy. We pulled over. It was crazy. And I'm like, and they're like, hey, your insurance only went up to, I want to say we had $50,000 or whatever. They already met. That amount, and they said if they go over, we were going to be like, we needed to get an attorney.
What were they saying was wrong?
I don't know, it didn't get that far. The insurance company did their due diligence, fought it and whatever, but I'm like, what? Yes, I had no idea. And then they're trying to sell like another policy and this and this. I'm like, wait, I don't like— knock on wood— I don't get on accidents, but it was just— I bumped, like it was a bump. I wasn't even going like— it just rolled forward.
That's wild.
But then something with a personal—
I mean, injury, blah blah blah. I'm like, how could he? What did he do? He didn't get a new head. Like, what happened?
Um, he probably claimed, um, like chiropractors and stuff because I don't know if you know this, but whenever you get an accident, um, if you end up like going to a chiropractor or a massage therapist to like help ease the tension or whatever, you can turn those over to the bodily injury.
And he went to a spa, yeah, like lots of times.
Do you want to park behind me and bump into me?
It was so random. And I immediately— I'm so sorry, like, I, I'm short so I couldn't reach anyways. Long story, but I barely— I wasn't even moving, like, it just rolled forward and it was a big truck. But yeah, so then I got really nervous because they started sending this attorney information, and thankfully the insurance still did— I want to say did their part and it never went past the amount. But I'm like, it would have been getting blood from a stone because there's no more money here.
Yeah, you don't have $50,000.
No, just give away— just don't have that.
Yeah, people are wild, man.
But you know, I didn't know that you needed— like, I didn't know that if they got— like, you're only insured to your cap. Like, if they go above that, and God forbid it's a, it's a big accident, you are liable for those things.
Yeah. So like, I personally don't carry state minimums either, because state minimum is $30,000. Do you know how fast it takes to do that? Like, and if you have, heaven forbid, you're on 410.
Yeah.
And it's more than one car, it's $30,000 for the whole accident. It's not $30,000 per.
Oh, wow.
So like, you get more than one.
So if they find you liable because you bump and they bump, bump, bump down.
Yeah.
You're still responsible for, for everybody's.
So the $30,000 split between 4 cars doesn't go very far. No, no, not, not in today's world at all. Yeah. So I, I carry $100,000, uh, for property and then $100,000 per person for bodily injury just because it is more. Mm-hmm. But San Antonio is terrible drivers.
But is it like significantly more?
It's really not.
Yeah. I'm so curious about that.
Has anybody ever talked to you about, hey, you might want to have $50,000 per person. Never.
That's, has anyone ever done that to you?
No. Like, what does that mean?
Never in my life. Uh, another one that I see people are, they're like, no, I don't need the rental. Do you know how much rental cars cost?
Yeah.
They're, it's like $60 a day to get a mini SUV, which is what I would have to have just to fit all 4 of my children in there.
Yeah.
They could function. Yeah.
Like it doesn't work. Otherwise, and you, it's like $2 a month to have that $60 a day rental just covered for you.
Yeah. That convenience.
And you don't have to worry about it.
Yeah.
Like, because you can't Uber a family sometimes. Like, no.
Like, I've got a 12-year-old, a 9-year-old, and a 4-year-old. My 4-year-old's still in a car seat. Like, you know, it's a booster car seat, but that thing is heavy and lugging it around. It's just not practical.
Yeah. Yeah.
Plus, you know, like my oldest is in theater and she does EA gaming and she does livestock judging and, and that's just her.
Yeah.
So she's got on like Tuesday through Thursday, she has theater until 5 and then Friday she has EA game practice and Monday she has livestock judging practice. And then Saturdays we either go to a gaming competition or we go to a livestock judging competition. And that's just her.
Yeah.
Yeah. I mean, that's not even counting the other two.
It's not realistic to Uber to all the cities.
No, you'd spend more than $60 a day Ubering all those places. Yeah. Um, so you definitely, like, it's worth it to just bite the bullet, pay the extra $2 a month and just get the rental.
Get the rental. Mm-hmm.
That's good advice. And who knew?
We need to have a class. We need to have a class on English. I know.
Well, As you know, Marie and I are in real estate.
Oh, yes.
Whether we want to be or not.
Can my husband please tell me to quit?
Great.
Well, my husband told me to quit my real job to do this, so I don't think I'm going to get that again.
That was too much.
But, um, it's like a one-time offer.
Yeah, it happened.
And it happened like 12 years ago, so. But, um, I want to talk about homeowner's insurance.
Yes.
Okay. I need to know the things. Why is it so high and what is going on with homeowner's insurance right now?
So there's a lot of things going on with homeowner's insurance. One is we're having what feels to be a lot more natural disasters right now.
Yeah.
So they're having to pay out, the companies are just, they're having to pay out a lot more.
Mm-hmm.
Um, and so they're raising rates on everybody to try to mitigate their loss. Uh, because I always think of insurance as a bet. The insurance company is betting that nothing is going to go wrong and you're betting that it is.
Yeah.
And so every month that you lose the bet, they're losing, they get the money.
Yeah.
But whenever you win, you win much bigger. Um, and that's whether it's life insurance, health insurance, home, auto, doesn't really matter. It's all, it's a bet. Um, And so right now they've been losing, so they're upping the bet because all of these hurricanes, the fires, the flooding, the— I mean, every time you turn on the news, you see like, yeah, random hail. And so they're having to pay out a lot more, so they're upping the cost on everybody for everything.
Yeah.
So I have to see that in my— right now, because I, I work with buyers, right? So when they're looking for shopping for a home, I have to know a lot of things up front in order for me to get some kind of idea for— because home insurance will price you out of a house.
Yes, now it will.
If it has an old roof or had a claim or something that apparently I'm not finding out, I can't generally, oh, it's going to be X amount a year because I'm way off if I don't know certain— the home is older, whatever the case is. So I'm having to have that information up front. And right now I'm seeing a lot of times Buyers negotiating with the seller to, let's fix the roof because roof is 10 years old, because my insurance— I can't afford the home because my homeowner's insurance quotes that I'm getting are so expensive because the roof is old. Yeah. So that's a big thing, I'm assuming, right now because of the hail and all the things that happens to a roof.
And also what type of roof you have is huge. There's some companies that won't even do composite shingles. They're like, we're not gonna, yes, I won't, we won't insure my roofs.
Yes.
Yes. It's great. No insurance for you.
Yeah. Um, yeah. Like when my mom was looking for, um, homeowner's insurance a couple months ago, I had to go to like 7 different companies cuz they were like, we don't like her roof. And I was like, I don't like her roof either, but it's just the roof.
I think it literally just happened with your sister-in-law as well. Mm-hmm. I was lucky enough to help Faith's sister-in-law., on the purchase of her home. And that house is 2 years old. Like it, that roof is new.
Yeah.
And the company that she would normally use was like, nope, not this roof. And I was like, what?
Yeah.
So she had to look around, I guess.
But yeah, cuz she was asking me, um, about which company to go with and I was like, you should probably go with this one. I was like, I can't write you the one. Yeah. Because they're captive. So captive means that they only sell one company's insurance.
Got it.
I am independent because I like offering more than one option for everything. Uh, cuz I want to be able to, we like options. I love options. I like being able to help people find their option that works best for them.
Mm-hmm.
And not just, these are the 3 options I have, pick which one kind of fits you. Um, so that's why I'm independent.
Mm-hmm.
On everything. I, home, auto, health, life, all the things. All the things. If they're captive, I'm like, well, They're great, but I can't write it. Yeah. I'll just tell you this is probably the one you should go with.
Yeah.
And so I had told her, I was like, this is the one, um, that I like. It's one of the ones that's coming in least expensive right now. Um, and then she came back and she was like, yeah, I can't use them. They won't, they don't like my roof.
Mm-hmm.
So I was like, what?
It was, I mean, that was the first time that had happened to me with a buyer where it was like a new roof. I've had buyers that have to, like you say, negotiate to put in.
Yeah.
Because like the roof that currently is there is like not insurable. It's that old and damaged and whatever. Um, but I've never had a new, like, in good shape roof. People be like, nope.
And it was just because of the way it was made.
It was just like a basic roof and they wanted it to be, I don't know, I think that particular company maybe wanted it to be like dimensional shingles or something like that.
It's the shape of the shingle.
Yeah.
Itself is what they don't like.
We gotta get a life, man. That should, but okay.
Brand new roof.
But they just, they just changed their policy. About 9 months ago on that one, um, because before they would cover it. Yeah, because I had mine with them for forever and they were like, you can— you'll be grandfathered in, like, but if you ever drop us, we won't take you back.
Yeah.
And I was like, okay, well, and it's—
and it just— it changes. I would assume, like, in your industry and as in ours, rules change daily sometimes. Like, what? We did this last week, why can't we do it this week? So trying to stay on top of guidelines and changes and that, that takes someone— having a relationship with your insurance person is very important.
I agree.
Like, having that relationship— hey Faith, what's going on? Um, yeah, I need this because this is changing my life. And you're like, okay, that won't work anymore, we need to do this. Yeah. And this is why. And walking you through those steps, because if not, then you're blindly just signing stuff and could be wasting money or not having the coverage that your family needs.
Yeah, I know. Right now not to be political.
Sure.
But there's a huge thing going on in Washington, DC right now about health insurance and ACA marketplace and the premium, like the subsidies. Um, and you were talking about changes that are happening every day. So I get certified every single year so that I can sell health insurance plans with the marketplace. Like, I have to get certified, I have to take a class It's like 3 hours long and it's about all the new regulations that they have for that year. This year they were like, here's your certification, but things might change between now and December, so we'll keep you updated. And any plans that you write between now and the end of December might have to do them again before January 1st.
Right, we're now in the realm of open enrollment right now, right?
Yes, yes we are.
For health insurance, so that's coming around.
Yeah.
And ooh. Mm.
Yes. So the subsidies are set to expire December 31st.
Mm-hmm.
So everyone that's, we're doing open enrollment for January 1st of, and for all of next year. And so, and people are coming back and their premiums are a lot higher this year.
Yeah.
It's great. Uh, having to have a lot of hard conversations with people. Yeah. Um, because they're like, hey, last year with my subsidy, my insurance premium was like $20 and now it's like $40. $400. What's going on?
Yeah, it's a lot.
It's a big difference. And so we've been having to explore different options for people to go with, make hard choices about what they're prioritizing, whether they want a lower premium or if they're okay with, like, do they want a lower deductible and a higher premium, or do they want a higher out-of-pocket maximum or a lower one? And so that I think is what's really important to work with a broker because You can tell, like people will tell me like, hey, my kid has asthma. I know that we're going to go to the doctor this many times.
Multiple times. Yeah.
There's a really good chance we could end up in the hospital at some point this year. And so for them, I'm like, okay, let's go ahead and put you on something that's going to cap those costs. And yeah, you may be paying a little bit more out of pocket every month, but if worst case scenario, someone ends up in the hospital, you'll be capped on how much you actually are paying out of pocket.
But do you know how many people who don't understand that conversation or even know to have that? I had to sit down because I'm— my insurance is through an employer-based policy, right? And I move companies, it happens randomly, and I'm like, why is this so much more? Like, oh my goodness, this is like— I'm, I'm making a whole lot less money because of what my insurance costs. So I had to sit down and really look at how often do I go to the doctor, what do we actually need? Do we have prescriptions that we need on a regular basis? And I had to decide a high deductible plan and say, okay, I need to put money aside on a regular basis because if something was to happen, I know I'm ready for more out of pocket in general. Like I know that, but I don't see the doctor on a regular basis. So a lower monthly premium made sense for our family. But my son now is going to need surgery. So I'm like, uh-oh, like, can we wait till next year so I can change my plan up? Like it just, but no one ever sits down and say, hey, these are things you need to think about. And so you can be prepared for these changes because you're used to just like, oh, here's a copay and we're good to move on. And that's not how life works anymore.
No, it's really not. And then there are some plans on the marketplace that like have a lower monthly premium, but they don't have a set copay for doctor's visits. It's a percentage after deductible. So if you have a $2,000 deductible, the insurance isn't going to pay anything until you've paid $2,000 out of pocket. And then after that, if you have that percentage after deductible, they're only going to pay, like say it's 25% after deductible is your copay, you are going to be responsible for 25% of the doctor's bill until you've met your out-of-pocket maximum. And so it's not like you go to the doctor and it's $40, it's the whole thing.
Yeah.
Until, you've met your deductible and then it's 25% of the whole thing until you've met your out-of-pocket maximum, which right now the out-of-pocket maximums are around anywhere between $8,000 to $10,000.
Well, so check out this conversation. So I called the doctor to make sure he was in my plan, right? The doctor is in my plan. The facility is not, that he works at is not.
That's fun.
What?
What a fun turn of events.
And then I have to, so it's Aaron. Aaron's going to need, he needs jaw surgery, right? And we're planning it for the, holidays.
Yay for him.
But, and so I had to, I had to like, okay, what about the anesthesiologist? What about like, those are not in the plan. I'm like, what does that look like? So I'm like, okay, uh, no, stop. We need to figure this out and regroup because that's not a full— we can't afford— I cannot put up my house for sale in order to pay for a jaw surgery. Like, this is not— no, no, no. But like, they get you because sometimes if you don't ask those questions, like, hey, what's covered, what's not, and so forth, Mm-hmm. Then you go into thinking, okay, this is covered, and then you're gonna walk out with a $40,000 bill because the random anesthesiologist wasn't in it.
Well, I find that we have insurance through the VA. I have CHAMPVA insurance. No one knows how to bill for it. Nobody.
No.
I go into every single doctor's office and I get charged like the most random amounts. They're like, this is your copay today. Like I see them look at this like binder. What's in the binder? I wanna know what's in there.
Best guess.
They look at a binder and they're kind of like doing this with their hand and I'm like, okay. And I know this by now. I'm waiting for the shoe, right? Like to drop. And sometimes it's like, hey, it's, you know, this amount of money. And I'm like, okay. But I'm like reluctant cuz I know I'm gonna get billed later. So I'm like erroneous amount of money. No one knows how to bill for it. It's a percentage of something.
Yeah.
No one knows.
Yeah. And I mean it, it, that should be illegal. It's crazy. Like my mom has Medicare cuz she's older and which I do Medicare too. She does it all. All of it. And so like, I was not doing Medicare whenever she turned 65 back in 2017, 'cause I was a baby. Not really, but I was in college. So she didn't know, she didn't talk to anyone about it. So she took Part A and Part B and that was it. And she was like, I don't need Part D because it's just prescriptions and I don't have any.
At that time.
So I'm not going to take it. Swell, down the road to last year in May, um, I made her go to the ER because she looked like she was dying. And come to find out, she had 3 blood clots in each lung.
Oh no.
Um, and after 2 weeks in hospital and like having fluid drained out of her lungs and all kinds of stuff, And then she had a specialist for everything, like every body part that you have, an organ, she had a specialist for. And she's on 15 different prescriptions for things and she doesn't have Part D insurance. And she was like, well, now I'm having to pay out of pocket for all of these things. And like one of them, Eliquis, is a prescription that I see a lot of my seniors on. And it's the only one, you can't get generic for it. That's it. It's a blood thinner. It's the best blood thinner on the market. You need it, especially if you've had blood clots or if you have heart problems or anything like that. And it's $800 a month. And that's it. So what I did for her and what I do for a lot of my seniors, if they end up not having coverage, and actually a lot of my clients too, is I'll tell them there's a website, it's called needymeds.org.. And you can find, like, you put in, it's really easy. You put in the prescription that you have and they find manufacturer's programs and coupons for it. And then they can also give you a list of pharmacy prices in the area for cash prices. So with her, I managed to find the manufacturer has a program where if you don't have insurance, they'll give you, and like you do the whole approval process they have and she was able to get it for free. They would just mail it to her every month. So that was really nice.
That's amazing.
That is a huge— yeah, I had no idea that prescriptions cost differently at different supply or places.
Yes.
CVS versus HEB versus— yes. Like, I was paying for this medicine, allergy medicine, like a monthly was— we were at CVS because at that time, years and years ago, my insurance said, hey, use CVS. That's where we like to, whatever. So we always did it. I thought they were the same. And then for some reason, I don't know why I got moved to, we had to move it to H-E-B. It, the, the price difference was huge.
Really?
Huge.
Like we paid, I don't wanna say $40 at CVS, nothing at H-E-B. Mm-hmm. Like, wait, why?
H-E-B has a great prescription program, to be honest.
I guess I thought it was the insurance that was dictating that information.
I thought it was not, I guess.
Um, so they do play a part in it.
But H-E-B, like they have different prices too. So like for my insurance that I have right now, my daughter's ADHD meds for the generic version at H-E-B is $15 because that's what our tier is for that. If I use the brand name, it's $75. Yeah. But if I went with just H-E-B's program that they have and didn't file it through insurance, her brand name prescription would only be $65.
Oh.
So they pay, I pay the lesser amount because I go to H-E-B. But if I went to Walgreens where the non-insured price would be like $85, I would be paying $75.
Hmm.
So it just differs. I had no idea. Yeah, like it— because I always thought it was insurance I was dictating the price of what you're paying.
Yeah, like, well, like I said, we have stuff through the VA. I can't go to H-E-B, they make me go to Walmart. Yeah, they won't, they won't let me fill them over there, right?
But I'm telling you, like, you don't— until you are adulting, you don't really understand this. And even then, you don't— if no one sits down and talks to you. Yeah, about it. And you could be way overpaying or not are under coverage or are undercovered.
And this is the perfect example of what we talk about. Like you don't, and we do this all the time on this podcast. You don't know what you don't know. Mm-hmm. And so it's like when you go to a mechanic and they're like, this is gonna cost a bazillion dollars. And you're like, I don't know. So here's all the money. I need this vehicle or whatever.
I call my dad.
Yeah.
Well, I mean, I don't know. We, we never know. And so I'm just like, here. Yeah. And so, but I mean, if you don't know, like you're not really looking out for it. So when insurance tells me this stuff costs this, I'm just like, Okay.
Yes. You know, well, military insurance, I would think, would be— it's also different just in general, right? So it's a little different, but, but in general, like, you still have to have something. And, you know, and it would be nice to have someone to talk to, like, hey, these are the things that I'm— here, here are the hard things that I'm facing. Like, my prescriptions are way too much, I'm paying too much out of pocket for premiums monthly, and I don't go to the doctor. So, and here are some options for you. Here's some ways to save some money.
Yeah.
And then when life changes, let's talk again next year.
Yeah.
And make sure that you're at least touching base with someone who you can build that relationship with them. Oh, I've had— I'm about to have a baby.
Why?
I just found that I'm pregnant. What should I do with open enrollment? Yeah, right.
So by the way, I'm not having a baby, but I actually have conversations like that in moms groups all the time.
Yeah.
Um, where people are like, I don't know which plan to pick through my employer. And I'll be call me. Yeah, like, I know that I'm not going to sell you anything. I'm not going to write you a plan. You have employer insurance. But if you need help explaining it, you could call me and I'll walk you through what everything means and which one would work better for you.
You know, because I've always had employer insurance, I didn't, I didn't know if that— now that I, I guess talking it out loud, like, is that the best? Why do— how do I know that's the best choice without talking with you? Does that make sense?
Like, well, you wouldn't, but most likely it is.
Is that true? If you have stuff that you can go through work, you should go through work more often than not?
Um, so the way insurance works, because you know how the government is, things aren't always the best when they get involved. Um, but so if you wanted to go through the marketplace for insurance, you have to and you're offered employer insurance, there's a couple of things that we have to do. The employer plan has to be more than 10% of your income or it's considered affordable and you don't qualify for marketplace insurance.
Oh, interesting.
Which 10% of your income—
That's a lot.
Is not my definition of affordable, but that's the government's definition of affordable.
Yeah, that is not affordable. That's a lot of money.
So if you decided not to do that.
Is that gross?
Yes.
That's a lot of money.
It's your taxable income. So gross. Unless you own your own business and you write a bunch of stuff off. The other option that you have is to do individual off-marketplace insurance, which the state of Texas right now has it to where the short-term plans they want you to do it 4 months at a time. The problem is, is if you do it 4 months at a time and something happens, like in your 4th month of having insurance, then it would be considered a preexisting condition when you do the next 4 months and they're not going to cover it. Whereas the marketplace, it would be covered.
My brain is doing something weird right now. It's trying to think about this. Which is, it shouldn't be. So you do this 4 months at a time and during that 4 months you discover some illness that you have.
Mm-hmm.
Then you have to re-up and when you re-up they're like, no, not this thing that you know you have about now.
Yes.
What? That's why would you want to re-up every 4 months? That's awful.
Yeah. Um, because that is what the government has us doing right now. It's great. Uh, the state of Texas legislatures don't know much about insurance.
Yeah.
And they—
I don't think they know a lot about anything.
Well, I wasn't going to say that, but I agree with you. But they don't know a lot about insurance, but they like to make laws about insurance. So now we have this problem.
They do that in our industry too.
They sure do. Yeah, it's great. So if you have employer insurance and it does meet the affordability clause, it's probably going to be better for you. Got it. If it doesn't meet the affordability clause and it's more than 10% of your income, then you would qualify for marketplace insurance and we could go from there.
Got it.
Mostly what I put people on short-term plans with is, like I had a client just this last week where she called in and her income was more, she wouldn't be getting any subsidy for the marketplace. So for her and her daughter, a silver plan was going to be $1,100 on the marketplace.
A month.
'Cause they have to pay full price. 'Cause they're not getting a subsidy. Which is not in any way affordable.
Mm-mm.
And so for her, because they don't go to the doctor a lot, they don't have any preexisting conditions, I talked to her and I was like, this is an option. You can have this coverage. It's actually about the same as what you get on the marketplace, but it would only be about $400 a month instead of $1,100. I was like, it's an option. It's up to you. I will write whichever one you want me to write because I get paid either way. Yeah. Yeah. And so she ended up going off marketplace. So I do present those options to people and let them know, but I was like, but if something happens, they're not going to cover the pre-existing. So it's one of those things. Yeah, it's a gamble.
Um, so if you like Vegas, try insurance.
But yeah, I would always suggest people talk to a broker about anything because there's a lot of ins and outs that if you don't know, you don't know. Like before I started doing insurance, I was like, I don't know.
Yeah, same in our industry. We didn't do what we do, we would have no clue how it works. It's just trying to find those trusted individuals that you feel comfortable with and sharing, and, and someone to stay on top of you. Like, hey, you're— it's open enrollment, what's changed? Let's talk about your options.
Yeah, well, it's like I had a client the other day and he was like, hey, it's that time again. And I was like, yeah, it is, because he texts me. Sure, you can text me.
We love texting.
I love texting. A lot of my clients love texting. It's a millennial thing, I think. Everyone's like, I don't want to talk on the phone.
I was like, fine, you can text me.
Talking on the phone. So like, I get clients that'll reach out on Facebook Messenger or via text, and I'm fine with that. They can, they can do that. Um, but, uh, he was like, hey, let's renew. And I was like, okay, cool. And he was like, I like my plan. And I was like, all right, has anything changed? And he was like, no.
And I was like, I got married.
That's where we're going with this. I was like, okay, so still you and your wife and your 4 kids, and you still live at this address and you still have this income. And he was like, oh, well, my wife got a job. And I was like, okay, how much does she make? That's a change. Like when you said no changes, yeah, that's a change. And he was like, she makes $1,200 a month. Okay, cool. And then I was like, any other changes? And he was like, I got a raise. And I was like, also an income change. Mm-hmm. I need to know about that. And he was like, and we had a baby. And I was like, that's a household size change. Mm-hmm. I need to know about that. And he was like, oh, and we moved. And I was like, also a change.
Yeah.
Yeah.
Yes. And then I was like, okay, so I put all these changes in. I was like, if you wanna keep your plan, it's gonna go up $300 a month. And he was like, mm, maybe we should call. And I was like, maybe.
Yeah.
Yeah. Um, and he ended up changing plans, but he was still covered, so it worked out. But yeah, I don't ever trust those. No, nothing changed.
Yeah. They lie. He had all the changes.
He had all the changes. I have noticed though. That when it's moms and I say, have anything changed? They'll be like, oh, well, you know, I moved one block over and I'm like, okay, well that works. It's not gonna really affect anything cuz you're still in the same zip code, but thank you for telling me. Whereas when I talk to the husbands, they're like, yeah, no changes. And then it's all the changes.
Tell me why your zip code matters. What does that mean?
Um, so specifically on the marketplace, the zip code. There's different plans that are offered for different zip codes. So like, it has to do a lot with network. So like, even here in San Antonio, the zip codes, we pretty much have the same plans. We got Oscar, Ambetter, Aetna left the marketplace this year, so they're not there, United, Blue Cross Blue Shield. But if you go to say, La Vernia, or Pleasanton, you get Oscar and Blue Cross Blue Shield, and that's it. The other ones aren't there because the hospitals and doctors down there aren't in network. And then like, if you go to Corpus Christi, um, Christus is going to be one of the major carriers down there. And then while they do have plans in San Antonio, they're not affordable and they don't have a lot of coverage. Whereas if you go to Dallas, um, Baylor Scott White is going to be one of the bigger ones and they have nothing here in San new.
Yeah, how interesting.
They speak another language. Yeah, like what? But yes.
So even though you're still in the state of Texas, if you move, even if it's not that far— I mean, Pleasanton, I grew up in Pleasanton, it's 30 minutes away. Sure. Like, it doesn't feel like that big of a difference, but it, it does.
Makes a change.
Yeah.
Well, this has been so interesting. It's, it's opened my eyes to what I don't know, which is everything.
Everything about English we have no clue. There's so much more to go into.
Yes, for sure. Well, as we kind of wind up, I usually like to have our guests share how people can get a hold of you so you can educate them on all of these things that we talked about today.
So there's a couple of different ways to get a hold of me. I do have a website. It's called rockingourinsurance.com. Just all one big word, no dashes nor anything. And then I also have a Facebook page, Rocking Our Insurance. And my phone number is the easiest way to get ahold of me.
She likes text.
I do. I text works. You could text, you can call me. And then my phone number is 830-570-2323.
Perfect. Well, we will put all of that in the show notes and thank you so much for being on and educating about insurance. Like I said, I just knew nothing.
And let us know how much we really don't know. Yeah.
Which is important. But thank you for being here.
Yeah, of course. And even if it's not me, you should talk to a broker and get more information about stuff just to make sure that you're actually as covered as you think you are.
That's a good point.
Yeah, for sure.
We tell people.
Good advice. Yeah. And I'll also thank our listeners for tuning into this week's episode, and we'll catch you next week.
See you guys next week.
Thanks so much for tuning in to this episode of the Working Moms of San Antonio podcast. We hope you loved today's chat and found a little inspiration to take with you into your week. If you have a podcast topic suggestion or a question you'd love for us to cover, definitely send us an email at hello@workingmomsofsanantonio.com. We'd love to hear from you. And until next time, see you in the community.
More from Erika


I don’t want a prenup, I just want you!" 📜💍 …until you realize you just agreed to 50% of zero! 😂

In Texas, a 17-yr old is legally considered an adult in the criminal justice system

What Every Parent Needs To Know Before Your Child Talks To The School (Texas Law)
Is Your Marketing Strategy Tasting a Little... Muddy?#podcast #podcastclips #podcasts #