Britain bullish on a Brexit deal as GBP rallies
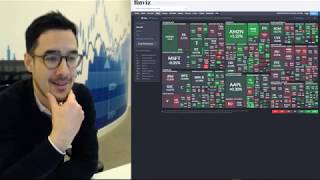
In this live market briefing, the host (Speaker A) and co‑host Sam provide a comprehensive overview of the macro and technical landscape shaping the trading day of February 20, 2019. They start with a quick scan of US equity performance, highlighting the continued strength of the NASDAQ and the short‑term trend lines on the S&P 500, and suggest possible breakout or pull‑back trade ideas. The discussion then shifts to commodities, where gold, copper and oil have all broken key resistance levels, a move the hosts attribute to improving China‑US trade talks and the U.S. request for a stable yuan. Detailed charts illustrate gold’s march above the 2019 high, copper’s return above October’s peak, and oil’s double‑top formation, all framed as bullish signals. The briefing moves on to the latest US‑China negotiations, noting that both sides are drafting a memorandum on yuan stability, which could avert a tariff escalation and further buoy risk assets. Federal Reserve commentary is examined: Loretta Mester’s dovish remarks on balance‑sheet runoff, John Williams’s centrist view on rates, and the upcoming FOMC minutes, with emphasis on how the release timing (weather‑delayed API) may affect market volatility. Brexit dominates the FX segment. The pound has rallied on reports of progress in the back‑stop negotiations, amplified by rapid Twitter dissemination from journalists Harry Cole and Tom Newton‑Dunn. The hosts outline the political timeline – May’s meeting with Juncker, technical talks in Brussels, the potential “Malthouse compromise,” and the risk of a minority‑government collapse as Tory MPs defect. They advise traders to monitor Twitter for real‑time sentiment and to consider taking profits after the recent GBP surge. A brief note on Italy notes Deputy PM Salvini’s refusal to adjust the budget, deemed a background risk compared with the US‑China‑Brexit triad. Finally, the hosts list the day’s calendar: US FOMC minutes, delayed API inventories, Fed speakers (Kaplan, Bullard), and the May‑Juncker meeting, before handing over to Sam for intraday trade ideas across equities, commodities, FX, and European indices. The briefing ends with practical trade suggestions and a reminder to stay alert to the upcoming data releases.
Chapters
Okay, good morning, Wednesday 20th of February. Hope everyone is well. I'm going to get straight into the briefing. As you can see, a look across the, the charts, quite a few actual fundamental and technical things to look at today. So we'll divide that up in the usual way. I'll try and focus more on the news and understanding of what exactly is the current sentiment and context and a look ahead for the day. And then Sam can look at things in a little bit more finite detail as to how to basically plan around that and some potential trade strategies that might be interesting to look at going forward. So first things first, let's go straight into the heat map of the close of US trade yesterday on the S&P 500. And the reason why I'm pointing this out was earning season is still continuing So, you know, from a micro level, these companies still updating and typically of a much more smaller market capitalization. However, Walmart, the kind of largest and probably from an index trading point of view most important one of the week, you can see an absolute sweet spot on the table, the most green there. Walmart actually up about 2.2%, and they are a large company representative of a decent percentage size of their respective index in which they're listed. So that obviously helping lend its hand to kind of finish earnings season off on a relative front foot. And then the other thing, of course, has been the kind of progression, if you like, on the China side of things. That's helped not just global sentiment, but equity and commodities. I'll quickly run through just overviews of the charts. I know Sam will go through these in more detail, but you know, really two things here, um, while I'm talking to kind of set the scene for the fundamental stories at play. You got the NASDAQ has been continuing to just climb higher over time. I mean, this is looking over a chart of basically the last month. You can see multiple tests what we've had on that trend line, and it has held so far. Interesting area obviously we're coming up to at the moment because it's kind of make or break time. Are we going to snap lower on the break of that really strong trend line, or as the price gets squeezed in, is that now the next kind of opportunity for another squeeze higher? A similar type of price action mimicked then, as you would imagine, across the other kind of major indices. The S&P yesterday, uh, this is more of a short-term trend line from last Friday on 3 touches now, which is coordinating with the pivot on the daily levels. And upside targets being the overnight Asia-Pacific high at 82.5 and yesterday's high, which would be in line with the R1, just up at 2788 should we get up there today. Commodities though, obviously have been on a bit of a tear. Gold, I mean, this was the gold level which we were looking at with some interest right from the beginning of the week. On Monday, we had that kind of rectangle box. This chart really hasn't changed since that time. And that was the previous 2019 high. You can see how everyone was kind of looking at that. The break above there just saw a real continuation of the price of gold all the way up to— and this was something we were talking about yesterday, actually— this level at $1,338 in the futures was right at the peak of the Donald Trump night of the win of the election. And we had that quite extreme volatility on that evening. Any push beyond here, and we are trading above that level already, about clear $4 above. Then obviously opens up the idea of $1,350, and then the more pressing resistance points up at $1,365, the double top kind of cementing, uh, the end of 2017 high and beginning of 2018. Not just a gold story though, you've also got copper was another big level that it's just moved beyond. And we've been looking at copper for a while, you remember. I think it was about a week, possibly two weeks ago, I was talking about a number of big US banks that were putting out some pretty bullish calls on copper to accelerate over the next 3 to 6 months, uh, and also iron ore and so on. All of these which are intrinsically linked to China, which have been, you know, having quite a tough time at the end of last year as the trade escalation was kind of happening, and that kind of policy tightening idea that that was then dual-fold reasons for real weight in the equity and oil sell-off. That translated into a global growth slowdown story, which obviously has a big direct impact then on demand for these kind of industrial metals. But obviously the Fed have turned, OPEC have cut, China are doing whatever it takes, government and central bank, you know. So we've had quite a severe about-turn over recent weeks and Now technically we've managed to break above, uh, quite key areas. You can see here going back to that October, I mean, that was when the stock market was at all-time record highs, if you remember, was right on the exact same date. And we're now back above that in the copper future. And you can see here on the prior occasion where it bounced quite strongly back in September of 2017. So kind of bullish signs as well in copper markets in fitting them with some of those calls, just given some of the big macro risk events and how they've developed and moved on recently. Oil as well, obviously that would get support from the same kind of perspective. You can see here this, this kind of trend line at the top of the price action through February, which has previously been good resistance, although a little chopped up yesterday for sure, has been respecting it again as we've gone into the overnight session and early this morning. So Asia-Pacific high, that was a little bit up towards what would be close to this kind of double top of price action at 75. Definitely worth watching. Again, remember, given the President's Day holiday on Monday, the APIs will be tonight with the DOE to follow the day after. So everything's been pushed back on the schedule by a day. So as I said, you have the earnings side of things, but the China trade side is obviously pivotal. And this is the latest of what we've got, and this came out last night. And this certainly does help progress this and would be then, as we've seen, supportive of some of these commodity prices as well as, uh, kind of general sentiment and equity index futures. That's because the US is asking China to keep the value of the yuan stable as part of trade negotiations, a move aimed at neutralizing any effort by Beijing to devalue its currency to counter American tariffs, according to People's familiar with the talks. Now, officials from the two countries are discussing how to address this policy in a memorandum of understanding and would form the basis of a deal that ultimately then could look to be signed off by President Trump and his counterpart Xi Jinping, according to several people briefed close to the discussions. A couple of points with this is I do think that this is a positive I mean, if this is the concession that the Americans have been looking for, and the Chinese do bend to their will, then obviously then the, uh, tariffs resetting up to a higher rate gets averted, and net that's a positive development. Little bit questionable that the fact that the US is asking basically China to manipulate its currency to keep it stable— isn't that indirect currency manipulation on behalf of the US? Who am I to say, hey? But it's interesting. I think that this is a step in the right direction. I think that's the way the market have been taking it, and that's the way we have to look at it in terms of the way that, um, to trade it. Negotiations resumed in Washington yesterday, uh, following on the conclusions of talks in Beijing last week, and they are set to continue throughout this week every day. However, as yet I have not had any definitive schedule But of course, I do get the, the kind of daily movements and meetings of Donald Trump. I normally receive that in about an hour's time, so I'll keep you guys informed as in where he's going to be at what times throughout the day, just so you're best informed. Now, why is this so key for the commodity space? Well, this is a graphic I shared with some of you in, uh, who've done the Amplify course right at the beginning of your training. And this is when I tried to explain the reasoning behind why China is so pivotal and why a significant weakening of their economy has such dire consequences and reverberates across the global economy. It's not just a Chinese story. So fears of a hard landing, which were something of direct focus back in 2015, kind of reemerged at the end of last year when we had the big sell-off into Christmas. Was because if you think about it, back then the Shanghai Composite was down 25%, the currency was weakening against the dollar to quite extreme levels of near 7 against the offshore yuan. Things though have since stabilized. And when we talk about things like copper, what I wanted to do with this graphic is just to kind of give a little bit of granular detail as context to why China is so significant. They account in terms of demand for copper, 50% of all copper bought in this world comes from China alone. So if then we get progress on the trade side, as I said, we get lots of different ways and means of helping mitigate the downturn from a government and central bank level, and the Fed are obviously reversing course, which removes this policy tightening idea Well, then, you know, these products can bounce back quite significantly as appetite, kind of risk appetite returns. So copper 50%, obviously cement, aluminium, nickel, coal, all of these linked to the kind of industrial side of things, whether infrastructure and so on and so forth. So gold being another one, obviously from a physical demand side of things. Particularly, um, relevant both again on the industrial side but also culturally, uh, as a metal. So 27% is derived solely from China, and this data is dated as well, so I'm sure these numbers have even moved on since then. So yeah, hopefully just connecting some of the dots this morning. Okay, talking of the Fed, um, a couple things here. One is central bank speakers because yesterday we had quite an interesting speech coming out of a lady called Loretta Mester, who's the one of the most hawkish-leaning Federal Reserve members. Now, she made some quite interesting comments. The one that the media has kind of jumped on this morning was the fact that she was talking about potentially she could be comfortable with the fact of halting the balance sheet process, which is kind of the soft form of policy tightening. Now, this has been something of which we're going to look at very closely in the minutes, this idea of the balance sheet runoff for the rest of 2019. Now, what she said was interesting because that phrase I just said was dovish. She did come back and say though, as the economy continues to perform as expected, federal funds rates would still need to rise. But obviously that's not the one the press are pumping. The one they're pumping is a dovish element that's been introduced by typically the most hawkish member of the Federal Reserve. So quite a telling change here. The dollar yesterday did, did weaken as a session overall, and it remains pretty flat. So that did help elevate the major pairs. Cable obviously had its own sterling-positive elements as well and saw quite a dramatic move. Now, now we've shifted and we go back to Fed's Williams, who spoke in a Reuters exclusive overnight. Now, he said that he is comfortable with the level of US interest rates are at now and sees no need to raise them again. So here you're getting a little bit more of the centrist. So unsurprising, kind of fits that core kind of consensus view. But that with Mester, you know, it's looking more and more like when it comes to the March meeting that the Fed are going to drastically change the way in which they— the dot plots look and the composition of those. Okay, the other thing then we're looking out for this evening on this matter is the FOMC minutes. Now the minutes tonight, quite a key thing. And just, uh, I am aware there's a coffee machine going off in the background. I'm trying to remain as professional as I possibly can. Don't worry, it's perfectly fine. I'm sure Sam put you up to it to try and test out how professional I can remain. Um, yeah, going back then, FOMC, you've got the minutes coming out tonight. Now, a couple of interesting things to be aware of. We've got quite adverse weather conditions happening in the US at the moment. That has meant that there will not be the traditional lockup, which means the way of which the minutes is released is slightly different. Now this does happen quite often, not just minutes. That happens with economic data from the Bureau of Labor Statistics, for example, like non-farm payrolls. So instead of it just hitting the API and immediately out to the market and the machines, algos tied to this can react immediately, this is the opposite when actually it gets released quite often through, in this case, the Federal Reserve website, or in the case of NFP, if it was ever weather impacted, then the BLS website. So inherently there is a distinct delay. The machines are turned off and it means that humans need to interpret a mass of information almost immediately, which puts a completely different complexion on how you have to approach that type of event because that initial spike that you would see is kind of removed and what you get actually is still a large bout of volatility, but in a kind of more slightly prolonged timeframe. but very whipsaw in the first minute or so as people are trying to digest everything because the release is kind of drip-fed in a little bit differently. So if you are trading the minutes, be particularly careful of that. What is it exactly you're looking for in the minutes? Well, it's how dovish are they. We know the Fed have become that way from their more neutral stance. If the FOMC in data-dependent mode, discussions on the balance sheet risks will be key. Markets will be keeping an eye out for any clues that there is a consensus on the FOMC to halt its balance sheet runoff this year. So the underlying detail towards what basically Williams has said— how much detail do they give to that, and is it a collective consensus, or is it quite a split decision on whether that is the best course of action— that's probably going to define how dovish or not this is going to be. The third thing to be aware of here is something we discussed on Monday, which is don't forget on Friday I think there's 5 Federal Reserve members speaking. So remember, minutes are dated by nature, and actually on Friday we get a whole dump of Fed fresh speak of the current context of the present day. So it could be the case that as well that could be more interesting than this ultimately if we don't get those real definitive details. Given the dated nature of the minutes. Okay, Brexit. Where are we with Brexit? Well, a couple things I guess to be aware of. This is the headlines this morning. Theresa May is going to be meeting with European Commission President Jean-Claude Juncker. That's happening later. Now let me just show you cable. Obviously a tremendous day for cable yesterday, quite phenomenal rise. Um, you can see we're having a bit of a pullback. A couple things you need to be aware of this morning I'll get into in a second, but if we just take into context then the move from yesterday, here's some annotations I had marked up from old charts. So this was the post-EU referendum recovery high, we got up to 144. As the no-deal economic slowdown materialized in the UK, we sunk below 130. Then more recently here You remember the Valentine's Day, that was the last parliamentary vote, and then we've bounced back higher, broken that trend line, and we've responded here to the 61.8% fib retracement of that initial high that was seen at the end of Jan to the low that was seen on that parliamentary vote. And we've just turned back lower now, back towards the 130 handle. Yesterday, what was quite key was Twitter Now you'll know we put quite a great emphasis on Twitter when it comes to monitoring Brexit because the journalists are way better than the traditional financial newswires at breaking the latest kind of hearsay rumours in Westminster. Now Harry Cole, the deputy political editor of The Mail on Sunday, tweeted first and he was talking about surprise progression that had been made on a number of different points, but obviously the The main one of contention is the legally binding text around the backstop. And the pound kind of started to gradually move higher. And then you can see, this is a 1-minute profile, about 6, 7 minutes after he tweeted, it really started to pick up as his tweet started to circulate. Someone who's probably more widely followed is Tom Newton Dunn of The Sun. Soon as he tweeted, Again, following on but adding more fuel to the flame, concrete that progression really has been made, you know, accelerated from there. Then you had other reports about German-France agreeing on euro area budget compromise, eliminating some other risk events at least that had been on the horizon. We kind of continued to punch higher and higher and higher. So again, I would suggest watching Twitter is going to be quite pivotal to navigate if you are being more aggressive looking to trade some of these moves. Ultimately though, I do think this is probably fair pricing to take some profit after such a phenomenal rise yesterday. Don't forget, we went from basically low 129s all the way up to 131, so nearly a 2-point move. So taking some off the table if you caught that long, I think, is appropriate, just given the fact that there's obviously increased volatility with every day that comes now as the clock winds down for more definitive action to take place. Now interestingly, yesterday was all built on Britain sources suggesting that progress is being made, but EU officials are playing down the prospects of an imminent breakthrough. It was Juncker last night was quoted as saying that there isn't enough movement for him to be able to expect this to be a discussion with a concrete outcome him referring to his talks that are going to be happening with Theresa May today. To give you an idea, if talks this week go according to plan for Theresa May, her team hopes to put a revised Brexit deal to a binding vote in Parliament early next week before then the Feb. 27th kind of deadline. That would be next Wednesday, so you'd probably be looking at Monday, Tuesday for a potential vote to get ahead then of going back and potentially her losing her powers as Parliament gets more say as we go through that amendment process that we've had on two prior occasions. One plan May has been exploring in Brussels in the hope of reaching a breakthrough is the use of technology to replace the contentious backstop policy for the Irish border. This is something that's been mooted before. The new plan for technology known as the Malthouse compromise is not a serious contender for resolving the current impasse. We kind of heard that yesterday, but it could be revived as part of future negotiations is what people are talking about. And on that point, Attorney General Geoffrey Cox and the Brexit Secretary Stephen Barclay, they're in Brussels holding technical talks with European officials on the backstop, on that specific matter today, presumably later on this afternoon. The problem May has, of course, is the EU is repeatedly said it will not reopen the withdrawal agreement, a position reiterated by them on Tuesday. Instead, it could offer an annex to the existing text, which could be legally binding. So that's kind of where we are at, at the moment. Now, the other thing, of course, that's been happening, and this has been developing quite thick and fast, is another Labour MP has resigned. That's now 8 for this independent, uh, 7 of which initially set up this independent kind of fraction party. ITV's Robert Peston tweeted this morning that 4 Tory MPs quit the party today to become independent is what he expects. PM May's minority government will become even more of a minority with less grip on the Commons, so a general election moves nearer. That was Robert Peston this morning. So he's basically saying that Tory MPs also splintering away to then become independent, meaning that Theresa May, again through the kind of parliamentary arithmetic, is losing more and more numbers because all of these people typically would be more pro-EU friendly and therefore not backing of her deal, uh, and this causing further complications and a rising possibility of a general election, albeit that's still incredibly a low probability scenario. As it stands at the moment. General election opinion polls have just been coming out. There's one just come out from Sky just yesterday. Conservatives are still top, followed by Labour. This new independent group actually tabled at 1 percentage higher than Liberal Democrats is what the current kind of state is at the moment from national polls. So As I've said, the schedule today: May meeting Juncker, Cox and Barclay in Europe for technical talks. If you wanted to use Twitter to follow the news, obviously the Squawk is the first point. They have a designated person looking at Twitter. I've also got an eye on things, but it was these two guys, Mr. Harry Cole and T Newton Dunn are their handles, for those two journalists that I mentioned that were very quick at breaking the Brexit news yesterday. Finally, this isn't so much a market mover this morning, but something I thought I'd mention. Italy PM or Deputy PM Salvini rules out the need for a budget correction. Obviously, this has been as well one of the problematic issues over recent months that have dogged Italy because of their quite wide deficit proposals that were breaking or in breach of European Commission rules. And so we continue to monitor this situation. I'd say one saving grace for Italy, although economically on the ground it is— have— it is struggling at the moment, and that's been absolutely crystal clear in its economic data prints of late. Italy's almost slightly out of the hierarchy of really massive macro events, and so therefore hasn't really been something driving sentiment intraday because the market's slightly saturated by the trade war between the US and China and the kind of the overwhelming focus on Brexit. But Italy still bubbling, simmering in the background, something to be aware of. Okay, finally, quick look at the calendar from me, and I'll hand you over to Sam. What have we got on the day ahead? So this morning it is particularly quiet, so likely to be more of a US-oriented session. Session in terms of where the bulk of probably price movement will derive from. With that being said, there's not really too much out from the US today from an economic data perspective. It's just the minutes really, and that'll be at 7 PM, which could be of interest. The API inventories obviously delayed a day, they'll be out later tonight. DOE is to follow on Thursday. Speaker Mayers meeting Juncker here, as far as the calendars are indicating, that'll be at 5:30, so it'll be later on. I guess Wednesday, presumably she still needs to do PMQs, and then probably she crosses the channel to pick up conversations then in Brussels with Juncker later on this late afternoon, evening. Kaplan from the Fed, dovish member, speaking in a Q&A panel. That'll be later on this evening. James Bullard, the most dovish member of the Fed, well, other than probably Kashkari, he's going to be speaking on a monetary policy panel as well. So those two speakers will be later on, but I can already tell you probably what they're going to say. It's going to be along the lines of we shouldn't really be hiking rates and we shouldn't be really tightening the balance sheet. So I don't think you're going to get much surprises out of here. I'd say the minutes will supersede that as from attention point of view. And if anything, it's more about watching the hawks than it is watching the doves. We already know what they want. It's are the hawks going to move and join the collective group and form a consensus about the balance sheet is what's quite key to monitor. Okay, hand you over to Sam. Have a good day. I'll see you in the chat room. Thanks very much, guys.
All right, guys, hope everyone is, uh, is doing well. Yeah, as I mentioned, pound is coming back down, uh, this morning. Dollar not really doing too much, having had a quite a weak day yesterday, and obviously that helping gold and copper to to have pushed on. And it's bringing in the NASDAQ here. As you can see yesterday, the, the trend line working so well yet again, and we're not too far from a test of that. So would be one that I'd keep an eye on, you know, how many times can that offer up as a level of support. I think opportunity-wise, if that was to go short-term anyway, a short on the break of that, break of the low of the day, is not a bad option. to have a look at. However, as we saw into the back end of yesterday's session, a sort of similar trade of, of what could happen here in a break of those, uh, highs that have been getting lower. That was to, to go in the NASDAQ, S&P, etc. Good opportunity to, to get long as well is not a bad idea. And you can see here with the, the S&P, something similar to what happened yesterday, albeit into sort of the back end of the, the European session. So be keeping an eye on, on the NASDAQ with that trend line to see how that pans out. There's not too much in the way of a respected trend line for the S&P that's too similar. So the, the NASDAQ perhaps to lead way if we are to go to, to the downside. With, with copper's push higher, I think one market to keep an eye on is, is the Aussie dollar. I know we're coming down a bit lower today and just before I got on the mic, uh, Charlie just mentioned this, this trend channel, which, which does look, you know, like one that you would want to have on just from those lows. You see price respecting that quite well. Also with the, the push higher yesterday, weaker dollar, commodities having a half decent day. We're coming back to some interesting levels, uh, we've talked about for the last few days as well, those sort of pullbacks from the 30th of Jan and the early Feb where we did have the big push down, uh, overnight on the, uh, the 5th or morning of the 6th as well. So that around sort of the, the 7200 handle and today's R1 looks like quite an interesting area of resistance as well. Let's have a quick look over at oil, which is just testing the pivot now. We did push, uh, higher into sort of the overnight session and we, we've hit a sort of double tops. I'll be looking to see how we react around this, uh, this pivot. Yesterday's low, you can see, I mean, I know an area a few of us were looking at was just a bit below the pivot, did hold up quite well, and we have, you know, found a decent sort of run from that. But today's pivot, you know, the second sort of time that we're testing it already this morning, just be a bit careful, Bang, wanting to, to get too aggressive on on any, uh, sort of long around this, this area, uh, I would, would say, uh, quick look over European equities this morning. If I just bring the DAX into the picture, you can see we did have a sort of bullish start on the, uh, sort of 8 o'clock and just before candles. However, we have started to retrace a bit of that. Looking at this on a longer term chart, you can see how we did put push to the high, uh, of February, and, uh, that, uh, sort of level has sort of been rejected, and we're now back down below the R1. So I'll be keeping an eye on any other sort of push from there. Quite a key level. I think this morning you can see where we did break through. This could be the sort of the, the line for the, the bulls and, and the bears, uh, you know, buyers coming in above and sellers below, and that might help drag down another couple of the, uh, sort of equities in, in the States, for example, uh, as well. Just having a look more intraday at the, the euro. So the, the low that we had yesterday— I'm just going to make this a 60-minute chart. I know a couple people were talking about this yesterday. I think a few people did put it in the, the chat, the trend line that we had from the 31st of, um, of Jan. You can see we broke from through on Friday evening. So let me just get that in. You've got your sort of a couple of tests before that tested as good level support, and again yesterday that was the pivot before pushing higher. While I think, you know, the dollar over time is, is definitely going to continue to strengthen against the euro, just while we're above this, maybe short term the bulls are in control. However, we struggle to, to get above the the high that we had back on the 8th of February. So that's another level to, to keep an eye on as a resistance point. And as we come back down, I think that from a short point of view, I think if we can get a break of the pivot and this sort of low of yesterday evening, uh, I would like the look of, uh, of getting short almost the low, that sort of area. I think that's not a bad sort of trade to have a look at, um, data this morning. You know, as Ant mentioned, it's, uh, sort of relatively quiet, uh, one ahead of the, the meetings tonight. And obviously with the bank holiday on the Monday, just for any oil traders, you know, the, the data obviously coming out in the evening. So, you know, not, uh, not to worry about the, the 3:30 releases. That will be 4 o'clock tomorrow, I imagine. But now DAX is finding support on that previous high and then coming back to the R1. So keeping an eye, an eye, uh, on that sort of high of the month. Uh, oil around the pivot, just be a bit careful about. And, and NASDAQ I think really can be the, the sort of, uh, potential cue for any move lower in equities, which of course are still relatively, uh, extended for, for the time being. Gold, which we pushed to a, a high for the year, uh, with a move like this it's always slightly tricky to, you know, want to get too aggressive, to sort of almost feel like you're chasing it. If we just have a look at that on a longer-term chart, and I'll remove the pivots, clearing it up for you, you can see having pushed above that high that we had back from April and May last year— April, May last year— uh, really strong push. And, you know, I don't think there's much in the way of, of this market really having a strong attempt at testing those 2018 highs. However, in an ideal world, you would like to see a bit of retracement for, for that to really come in. And that was my sort of basis for the 1300 handle that we were talking about last couple of weeks. I know on this chart it looks like we basically got a touch of that, uh, but, uh, the long I had didn't really get triggered. But you can see similar sort of, um, trade opportunity could be for price to almost start ranging and can we get a test back of this key level in gold that we have broken? Now you can see plenty of times we do come back to, to levels, uh, after a strong push higher. Uh, even just looking at the, uh, the key 13— well, 1235 area, 39. Price pushes through, slow grind higher before, uh, then the slow grind lower before then pushing on. So potentially one to look out for for the coming days. I know with the Fed tonight you will see a bit of movement from the dollar potentially, uh, but yeah, 1326 in the futures, i.e., the retest of the April and May highs, uh, is, is definitely one to keep an eye on for maybe that final push to those highs that we had last year, that double top. Um, any questions, as usual, please, uh, do get them in the chat. Uh, dollar is relatively flat for the day. Uh, just having a look as well, the DAX is trying to have another go at trying to push higher. But a couple of interesting points in the market, uh, that should potentially get tested later on today. I hope you all have a good trading day, and I'll catch you in the chat.
More from Anthony


Inside the Biggest Banking Stories You Need to Know This Week (Anthropic, Diageo, Private Credit)


Inside the Biggest M&A Deals You Need to Know This Week (UniCredit, GameStop, eBay, Eli Lilly)







AI Breakthrough or Hype? Anthropic’s Claude Mythos, Tim Cook Steps Down & LIV Golf Collapse