China Stocks Bounce, Facebook Drops & Powell Update
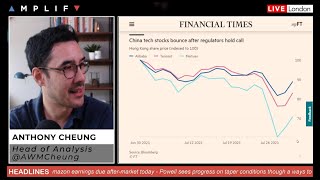
In this July 29, 2021 market briefing, the presenter provides a rapid‑fire overview of the multi‑asset reaction to the latest Federal Open Market Committee (FOMC) meeting, highlighting Jerome Powell’s remarks that tapering is still some way off, the resulting dollar weakness, and the modest relief seen in U.S. Treasury yields and equity markets. He then moves to currency markets, noting the EUR/USD breakout and GBP’s technical bounce, followed by a quick technical note on gold and oil price gains driven by the weaker dollar. The briefing shifts to a sharp rebound in Chinese equities – Tencent up ~7% and the Hang Seng up ~3% – after regulators signaled a softening of the data‑security crackdown and possible state‑linked market support. The presenter then examines Facebook’s post‑earnings slide (‑3.5% after‑hours) despite earnings beat, attributing the dip to weaker daily active users and looming regulatory/ad‑targeting headwinds that weigh on the Nasdaq. He also updates on the U.S. bipartisan infrastructure bill’s Senate passage (≈$550 bn new spending) and its macro‑policy backdrop. Looking ahead, he outlines the day’s key data releases – German unemployment, Eurozone business sentiment, ECB meeting minutes, and especially the U.S. Q2 GDP “first look” (forecast ~8.5%) – and discusses how a surprise high‑growth print could reignite dollar strength, push yields higher, and pressure gold. Finally, he previews the earnings calendar, with Amazon’s after‑hours report as the headline, and a slew of European results (Airbus, EDF, Total, VW, Nestlé, Lloyds, Diageo, BAE, Anglo American). The tone remains analytical and conversational, with a cautiously optimistic stance on the rebound in China and the infrastructure bill, but a measured concern over regulatory risks for Facebook and the uncertainty surrounding upcoming U.S. macro data.
Chapters
Okay, good morning folks, it's Thursday the 29th of July, so I hope you're doing well. And going to talk about quite a few things of note actually have happened in the last 12 hours, from the FOMC meeting last night and the relative kind of relief almost in markets that there wasn't an accelerated conversation on taper. And so we'll have a look at some of the multi- asset class reaction to last night. We're also going to talk about Facebook earnings. They dropped around 3.5% in aftermarket trade after some concerns about regulatory, um, conditions going forward and platform changes which could impact their advertising business. We're also going to talk about the US infrastructure bill which passed through the Senate to continue now that hearing going forward on Capitol Hill. And also finally talking about quite a sharp rebound in Chinese equities overnight. Tencent, one of those largest tech companies, was actually up about 7% in overnight trade. The Hang Seng trading up about 3%. And this coming after Chinese stocks have been getting hammered on that data security crackdown that we've seen weighing on technology and educational stocks. So that's what's on the menu for the briefing this morning. But as ever, let's just kick it off with the general sentiment across markets at the European Open, just having gone through 7 AM here in London. And dollar weakness is one of the main prevalent themes seeing this morning. Um, that comes on continuation, a little bit of fluctuation on the initial release of the FOMC, and then persistent dollar weakness. And so I guess to start things off, before we look at the charts from a technical perspective, what exactly did Powell say? And the headline here pretty much sums it up: progress on taper conditions, although we've still got some way to go. And in summary, before I go through some of his main comments, that's really the gist of it. The idea being here then that the market was perhaps then a bit cautious going into this on could we see a hawkish twist. It didn't occur, and so therefore hence the dollar weakness. And we saw at the time yields decline, T-notes went bid, as did stocks in what I would probably classify as a short-term relief given the, the continuity here and no acceleration on the hawkish side. So basically we're moving closer to starting to reduce support for the US economy. This idea of tapering— Powell, though, said we still got some way to go. He, quote, said, we are not there and we see ourselves as having, though, some ground to cover to get there. And the economy has made progress towards these goals. The committee will continue to assess progress in the coming months. And the FOMC vote was unanimous. So the timeline that is the general perceived Wall Street consensus, which really is towards the back end of August when we have the Jackson Hole Symposium, then leading us into the, the more formalized projections which we're going to see with the latest dot plots and so forth in September, is really seen as the main point when that is still going to happen. So that kind of view remains intact largely. Powell continues to frame inflation as transitory and will remain elevated in the coming months before moderating, but added that inflation could turn out to be higher and more persistent than expected. So absolutely cut, copy, and paste from what he said previously. And looking at these charts then, as I said, the dollar has kind of been the main more sticky move that we've had, and that has helped then some of these major currency pairs. The actual FOMC event was this kind of wick, wick here, extension that you can see on the volatility at the time of release. But then you can see the persistent dollar weakness has made EURUSD then able to break out of some of its near-term range of which has been a market trending higher on some continuous dollar weakness. And overnight, the Asia-Pac session, we came back down to that relative point of interest around the 139 handle. This is looking at Euro futures to find a bit of a springboard and floor from that previous double top to then continue that trend upward to trade at the R1 this morning. On a daily chart, um, actually this is— I'm looking at BP6 here, so this is the British pound. And not the euro, just to clarify. So on, on the pound then, looking on a daily chart, um, we've broken out of those highs from the 9th and 12th of July. So we're trading now back to the highs that we were seeing back on the 28th of June. This is around 1.3943. So finding a bit of a short-term resistance point here technically as we move higher, if we do so. Then 140 is kind of the next stop from a technical perspective, which was quite a key inflection point for the year to date. In fact, um, as you can see going back through February, March, April, and June price activity. So levels that I'd be keeping an eye on here in sterling on any further move higher. As far as the euro is concerned, and we broke out of the trend line yesterday that we'd been observing for some time, as you'll recall from a number of the briefings that I've been delivering over the last 2 weeks. And so the initiation of price, the catalyst being the dollar weakness on the FOMC. And so breaking through that, we've now also taken out the high that was seen previously going back to, what, the 15th of the month. And that's providing a bit of a short-term floor, having pulled back from that initial APAC high that's been seen at 1.1874 overnight. Upside, you've got the R1 sat around 1.1882 area, which would start to bring in some of the highs that we were seeing back on the 13th of the month. Which would be areas of resistance that I'd be watching on any further more persistent dollar weakness. Gold then managing to break out of its relative range to the upside, finding support emanated from the, the weakness in the dollar. We're up $15 extension overnight in Asia-Pac trade for the yellow metal, just seeing a bit of a breakout through these relative highs that we had seen through the back end of last week on Friday, beginning of this week on Monday. You can see we came up on the initial acceleration in gold, uh, post-FOMC, but found a bit of a short-term top until US players exited the market. And then the APAC session saw the breakout, uh, and then the move through as well, the high that we had back to last Wednesday. So short-term now got a bit of support around the, uh, the R1 on any pullbacks around the $118 handle, but yeah, some decent moves to the upside and up $15 to $16 this morning. In the equity space, actually the move fairly tame because if you actually look at when the FOMC came out, it was this price action here. If you actually look where we are, we're still pretty much in a range. So, you know, the one thing I'd say from the Fed is that the relief of sorts that had been seen is a little bit of a as a classified, a relief more than anything particularly shocking. I don't think what the Fed said last night was a surprise. It was pretty much in fitting and in keeping what most people were looking for because we weren't anticipating anything to happen of a great deal so soon. Not when we're looking for another few weeks yet to monitor things like COVID variant outbreaks of the Delta mutation in the US over the coming weeks, allied to how fast the infrastructure bill moves through Congress. With as well more inflation data and jobs metrics to then determine the taper timing towards the end of August. So as far as T-notes are concerned, I mean, here's the FOMC kind of bump that we had. But, you know, if you step out of the noise for a second, we are basically just trading a range at the minute. And so we're pretty much mid that at the moment. And that really, I think, says a lot about how much markets were just basically unwinding some of those hawkish outside bets and now kind of normal service resumes. The one thing is the dollar breakout being almost exacerbated, I think, by some of the, the technicals we just spoke about. Oil as well, a little bit higher this morning. Again, the weaker dollar definitely helps on that regard. And in the short term, I'd say we've also got a bit of a footing, a similar sort of price pattern to gold. You've got the previous highs that we were seeing in yesterday's session now providing what was resistance to turn support now for any pullback on prices. So the range now that we're eyeing for the rest of the day ahead, 7260 to 7284 on the upside. So let's just talk through a couple of these news stories then, having looked at the charts. And there's a few things I definitely want to cover off, and one of the big things is about China. And this comes as Chinese securities regulators convened executives of major investment banks on Wednesday night, attempting to ease market fears about this crackdown that's happening on the Chinese educational industry. State-run media has published a series of articles suggesting the rout is overdone, while some analysts have also speculated government-linked funds have begun intervening to prop up the market, which is not uncommon in China. The kind of plunge protection team definitely coming out given the severity of the fallout that we've had. You know, if you think about some of the tech giants like Tencent, They have fallen as much as 23% in the month of July alone, which is akin to around $150 billion of market cap. So phenomenally large moves. I think Alibaba's shaved off about $100 billion in market cap. So seeing fit then to come in and intervene to steady the market, given that this crackdown is having very negative implications on their local stock indices. In reaction to this, then, here's what it looked like in terms of the overnight session. So you can see then some of these bigger tech names listed in Hong Kong have seen a decent bounce in overnight trade. This is indexed to 100 rather than the share price in itself, but the Nasdaq Golden Dragon China Index— if you might not have heard of that, but that basically tracks Chinese stocks that are listed in the US, and obviously they're the ones that have been big casualties after that car-hailing firm Didi really ignited this latest shift from Beijing and has weighed on these tech stocks. Wednesday's reprieve followed a 3-day plunge that has basically in total raised about 800 billion of Chinese equity value. But as I said, all of them have bounced overnight and Tencent have actually risen about 7% in overnight trading. As a consequence, the Hang Seng has traded up about 3% as well in overnight. Session. So equity markets this morning going into the European Open actually looking a little bit buoyant. If anything, the DAX here, I'm just keeping an eye on 15,577, which was that previous support and resistance point on that double top we've had from going back to the beginning of the week. And there's the R1 on the daily pivots today, so just mindful of keeping an eye on that. And on the downside this trendline of the last 24 hours. US equity index futures as well, a little bit positive. The Nasdaq underperforming a touch on the disappointment from Facebook, which we'll touch upon in a minute. But the idea being a kind of continuity from Powell, no hawkish surprises on taper, with China coming back to alleviate concerns on the crackdown, has got equity index futures moving a little higher here going through 7 AM London time. This morning. Why is the NASDAQ underperforming? Well, one of the big components of that index, Facebook, which accounts for roughly around 5.7% from an index weighting point of view of the entire index, they're actually down— well, let's have a look— down around 3.5% or so in aftermarket trade. You can see here they kind of nosedived, fell off the cliff, and steadied out at around 360 in post-market trade. Now, why did that happen? Well, by the numbers, they beat on both EPS and revenue by a decent margin, uh, $3.61 against $3.04 on the EPS and $29.08 billion against $27.87 billion on the revenues. Um, however, daily active users, so a very important metric for the firm, came in at $1.91 billion below the expected $1.95 Monthly active users 2.9 million against 2.97 that was expected on the street. Most notably, the company expects increased ad targeting headwinds in 2021 from regulatory and platform changes, notably what we've heard announced most recently from Apple in their new iOS updates, and they are expected to have a greater impact in the forward Q3 than what they've had in Q2. So that outlook and those concerns from those headwinds is what bumped the shares lower. But as I said, despite a little bit of a dip last night, the Nasdaq is following suit in sympathy with some of the more positivity that we're seeing emanating from those other factors I just discussed. As well, to boot, the next thing is away from the Powell relief and the China intervention, you've also got a little bit of progression finally on the US infrastructure plan. And so the US Senate voted 67 to 32 to move forward with a bipartisan infrastructure bill after a bipartisan agreement which was reached on the major issues of the infrastructure plan. And Senate Majority Leader Schumer commented that the vote— that his, his goal remains to pass that bill and budget framework before the August recess. So finally, after toing and froing, they've managed to push this at least another step forward in the right direction. The deal was reported to include $550 billion US dollars in new spending and infrastructure projects, which will amount to around $1 trillion when factoring in other expected funding such as transportation projects as well. So a couple of positive elements there to get things going this morning. Um, just wanted to mention this, uh, I don't think it's particularly that relevant in terms of the day trading environment I mean, from an oil perspective, you could say it's just another variable that lends a supporting hand to the market at the moment, which is on the front foot for the time being, because it means then this notion of Iranian supply coming back to the market is a long way off. You know, if you go back to the briefings that we were delivering 3 months ago when everyone was getting excited about the prospect of the US talking to Iran and then the flood of new oil that would come when they reach an agreement, and at the WTI crude was actually falling on the back of this short term. You know, we were always of the view that constructing a deal was going to be difficult, and it's proved exactly that. And so although it's gone a little bit quiet after a bit of a stalemate following several rounds of talks between the US and Iran about re-establishing that 2015 nuclear accord agreement, Iran's Supreme Leader spoke yesterday and and declared Tehran would not accept Washington's stubborn demands in talks to revive that deal and said the US had failed to guarantee it would never abandon the pact again. So obviously a lot of trust has been lost and will need to be re-established given the kind of pulling out of that deal from President Trump just a few years ago. So at the moment, I don't see any resolution to this anytime soon. Um, just trying to think, the appointment of Rajisi, the president-elect, still to come in. There's a few weeks to run until that does happen. There was a bit of speculation before that any concessions and kind of brokering of a deal might well happen before he comes in, in order to pass the buck then on Rouhani's tenure, if you like, to say that he made those concessions. So something to watch, but I wouldn't be expecting anything here, right here, right now on this front. And then as far as the day is concerned, this morning you've got German unemployment change and rate coming out just before 9 AM. You've got the German state CPIs happening throughout the morning as well. Eurozone business climate and sentiment data at 10 o'clock, albeit I would not be anticipating any real underlying impact for European asset prices on that data alone, but just something to be aware of. The ECB meeting account from their strategic review which is obviously a main focal point from the ECB meeting. The cat is out the bag. They've reconstructed their forward guidance kind of communication technique from that meeting just a few days ago with Christine Lagarde. So wouldn't necessarily be looking for a great deal coming out of those accounts of that meeting. And then you've got really what is the main event for the day, which is the US first look at Q2 GDP, which is expected to come in at 8.5%. 8.5%, uh, against the previous 6.4% in Q1. Now, 8.5% sounds pretty phenomenal, but it is actually a moderation from what we were seeing in the likes of the Atlanta Fed GDPNow model just a few weeks ago, which was well north of 10%. So things have tempered a little bit given some of the more now mixed, if you like, economic data in the US, seemingly just asking the question, are we hitting like peak growth rates now? Going forward. So a wide range though on the street. You've got 5.6% at the low to 11.9% at the high. So, you know, if we start punching at 12% plus GDP, I mean, that's going to definitely shake things up in a day trading environment. Do I necessarily think that will shift the Fed needle even at 12%? Perhaps not. But you're probably going to get an injection in the dollar, particularly given its positioning right now, which has been trending lower. So it's susceptible to some quite large snapbacks higher if we were to get a 12% print. I'd be expecting the same for yields. So the 10-year would come under pressure. Gold would get probably pushed back down quite hard, $20, $30 move. I don't think they're to the downside to put us back down, back into that lower bound of the recent range we've had this week would not be out of the question. But again, this would be statistically an anomaly and would be right outside of the top end of the most bullish estimate on the street. So probability-wise, if that outcome is low, Uh, but that's how I'd see things. And then you've got the weekly jobless claims, which to be quite honest will get brushed aside because everyone will be latching on to GDP for direction and they're coming out at the same time. Pending home sales at 3, and you've got $62 billion in a 7-year note auction, which has been one of those ones that's stabilized more recently in terms of demand, but was one which caused some concern just about 2 months ago or so. So worth keeping an eye on. for how well that gets received. In terms of earnings today, Amazon is really the biggest ticket on the bill. They're due to report after the close. In terms of the numbers, EPS expected at $12.47, and their AWS revenue is expected to rise at a very healthy rate, or a pace on the year-on-year basis. The company-wide revenue is expected to rise but at a slower pace though in recent quarters as analysts watch for their pandemic-induced boom in online shopping to slow. So the idea is, well, how much has that actually happened? Or is the behavioral patterns that have been brought into people's lifestyles as per the pandemic, have they proved to be more sticky? And, you know, if you're looking at a lot of mega-cap tech names that have reported thus far, I mean, Amazon is the last one to really complete the suite of the FAANG names, so, so to speak, then I would say not a lot seems to have changed. And actually, a lot of the demand placed upon these large tech firms, given the phenomenal size and increase in revenues that they're seeing, would show that a lot of the adoption of these services, it has been accelerated through the pandemic, seem to be here to stay. So be interested to see Amazon numbers tonight. In Europe, there's already been quite a few, in fact too many for me to comment on right here, right now. But Airbus, EDF, Total, VW. If you're trading the, the SMI in Switzerland, Nestlé reported this morning. And in the UK, Lloyds, Diageo, BAE, Anglo American. So UK, European, Swiss earnings season also starts to pick up a bit of pace now going forward. All right, that is it, gonna leave it there. Hopefully that was useful. Have a good day ahead. Any questions at all, feel free to drop me a comment. If you made it this far, thanks for watching it through to the end. And if you're watching on YouTube, really appreciate it if you could like, and if you're not already doing, subscribe to the channel. That would be amazing. All right, take care guys, have a good day.
More from Anthony


Inside the Biggest Banking Stories You Need to Know This Week (Anthropic, Diageo, Private Credit)


Inside the Biggest M&A Deals You Need to Know This Week (UniCredit, GameStop, eBay, Eli Lilly)







AI Breakthrough or Hype? Anthropic’s Claude Mythos, Tim Cook Steps Down & LIV Golf Collapse