Chinese GDP exceeds expectations but is it a surprise?
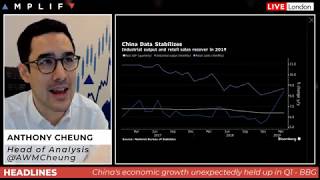
Chinese GDP, industrial output, and retail sales all beat expectations, but the market barely reacted. Netflix added record subscribers but cut Q2 guidance; IBM posted its worst revenue in 17 years; Qualcomm jumped 23% after winning back iPhone modem chips. Oil inventories drew 3 million barrels against expectations of a build.
Chapters
Okay, so very good morning. It's Wednesday the 17th of April. I hope everyone is well, and it's good to be, to be back. I'm going to be talking about a couple of things to get up to speed on, some Chinese data from overnight. As you can see here on my screen, I'm sharing with you. I'll talk you through that. And some thoughts about what I think that, that means for the future. Then we've got some updates on the trade side between the US and China, a couple of corporate earnings to be aware of, and then the oil inventory data last night from the API helping bump prices up a touch this morning. And we'll have a look at that as well as the calendar for the day ahead. But just quickly, just going over the initial charts here for the setup for the open, and it's relatively, I'd say, neutral. One thing as well, for a tip I guess for any of the newer traders, is I've been away for the last couple of days, and certainly when I come back after a spell away from markets, although I must admit I don't completely unplug as much as I probably should do when I'm on holiday, One of the things is, is that when I first come back, I'm very— I am very conscious of the fact that probably there's a couple of narratives I need to catch up on, on the various different macro stories. Obviously, the charts technically is the one thing that I wouldn't have seen whilst being away because I can stay on top of the news by just looking at various different financial publications and using Twitter, but the charts have obviously evolved and so Again, the point of this is what I like to do is not rush things when I come back, and I think that should be quite similar for those who are— again, unless you're a very experienced trader, you've got to get your, your kind of back in your rhythm. It's almost like getting your confidence back up, that type of thing. And so it as well, taking into consideration the timing seasonally, is Easter. One thing walking over the London Bridge this morning on the commute in is that it was incredibly quiet. Uh, and often this is a reflection of this time of year when people take advantage of the, obviously, the bank holidays around Easter and take an extended couple of days off. And so this needs to be, I believe, layered into your strategy and decision-making for the coming days for sure. I would say then probably today and tomorrow could have the propensity to be relatively quiet, barring anything unexpected because a lot of market participants are away at this point of the year. So yeah, a few, few things just to be aware of from a more broader overview. But as I said then, things are relatively quiet this morning despite some, some economic data in Asia overnight where, if I just switch over, essentially Chinese real GDP, industrial output, retail sales, all three measurements exceeded expectations. I think the GDP number was 0.1 higher than expected. A lot of this is— I wouldn't say massively surprising, and hence the reason why you've not seen a, a kind of very positive kind of response to this in the European Open this morning is that I'd say most Wall Street analysts were expecting GDP to kind of gravitate around this kind of mid to lower 6% region. So it's not massively surprising Uh, it's a little bit of a reaction effect, granted maybe a little bit sooner than some were expecting, of the various growth, uh, pro-growth policies that have been implemented from the government and the central bank. So a little bit of a bounce in this data, I guess, supports this overall, uh, kind of more positive story that's helped the equity markets globally recover. Uh, and I have seen that, you know, as I've been away, the S&P 500— I'm sure very pleasing for, for Sam while I've been away— has just continued to kind of chip away at the getting closer to the all-time highs. And, you know, the S&P is a chart here looking on the daily continuation that I think has responded so well to not just these kind of macro stories that have been ongoing from the Federal Reserve's dovishness to the improvements in the trade war situations. But the technicals have worked incredibly well as, as well. I mean, even if you were going from that trend line on the retest that we had back on the 25th of March, the golden cross where the shorter-dated overlaid the 50 on the 200 DMA, the way that the market has kind of broken and then acted as a platform back on that 2866, which was the previous resistance and support back in the summer of last year, targeting then the run to 2900. Some profit taking, a break, come back, retest the level for them to push higher. And, you know, I'm— as I understand the corporate earnings that have come out, and we'll talk about a few that have come out overnight, the banks have been pretty mixed to get things underway, but overall nothing to really detract from the point that, you know, it wouldn't be shocking to believe that this market can continue to just creep up towards having a test at this all-time high now that we've come this far. And I can't really foresee too much in the way of barriers to that happening in the kind of medium term. Obviously, big things to monitor on the back of that would be the trade war for sure, but as we're going to discuss in a second, that's still remaining quite positive. And I guess with this kind of overall situation and the, the kind of episode that we had in Q4 of, of 2018 getting more and more distant memory, and as the market continues this kind of fairly assured recovery, well then gold's got to come under a little bit of pressure to factor this in. I can see here that what yesterday was quite a crucial break, it looks like that we had Yesterday afternoon looked like it came in around the open here, which was a break on its respective S1, but also looked like the prior day's low. So yeah, maybe a trigger point technically for a push lower potentially going forward. For the day then, I'd be keeping an eye on the— well, really two points of technical interest perhaps. The trend line forming from yesterday evening UK time to the overnight Asia-Pac session and then the, the resistance now potentially a support level at around that 1280.5 in the futures, which was the, the kind of range high after the fall that we had after the COMEX open. On a daily continuation, obviously this is, uh, it looks all the more, um, explainable for a technical breach being the main catalyst probably for the break lower yesterday. You can see here that not just from what, the beginning of the month of April. This is kind of a very similar area to where the market has responded on, on previous occasions. So the break yesterday— gold does have the— is an instrument that responds quite violently when these levels do get broken. And you can see it just kind of pop lower there. Any movement down lower probably would be looking around this level here. It's kind of 68 65 type region, just where I've got that ellipse on the kind of trend line as well from the price activity going back from the, the tests that we've had in August and November. So, um, yeah, any further pullback here also draws in this kind of price action here, here, and here that I'd be keeping an eye on if we continue this kind of overall global positive, positive kind of view in the market. Cable, I'm quite pleased and obviously quite shocked that, you know, having been away, I don't actually have anything to say on Brexit. There literally is no news I've seen this morning when I've gone through the newswires that would warrant me updating you on. So that's all I'm going to say about the dreaded B-word for the moment because I'm sure it's going to return As I understand, they're on a bit of a recess at the moment after that extension was granted beyond April 12th. So let's get straight into a couple of the other news stories. This is one that's kind of headlining on Bloomberg, and it's talking about Trump stirs alarm that he may be giving China a new trade weapon. This is the— where we're up to at the moment with the trade discussions. It seems as though that they've agreed on various different points that will reform the kind of premise of the deal on different areas on the trade side. But it's about this enforcement mechanism will be reciprocal, which is highlighting a couple of concerns by a few people. This being the fact that the US have been very much pushing for what would be rolling, kind of every potentially quarter updates to see whether China are abiding by the rules. And having an open policy then that they can make various different enforcements if China are not upholding the deal that's been agreed. Now the problem here is that as part of the negotiation, it's looking likely then that China will have a reciprocal clause where if then the US are not doing as they should, then China can also counteract them as well. Which would be, I guess, logical from a negotiation point of view, but obviously does put the US in a slightly precarious position where obviously China does carry equal amount of power, you could say, as to what the US does. But maybe this is what's necessary to get the deal over the line. One thing for sure, I don't think this is really hugely surprising. I'd say this is probably normal business practice in order to get this deal over the line. It'd be highly unusual for it to be tilted so heavily in one country's favor, and hence the reason probably why the markets kind of digested this news fairly comfortably this morning. The other thing that was quite interesting and probably warrants just a slight mention here is that Trump gets trade setback after the World Trade Organization ruling that may foil the US strategy. And what this is talking about is is the WTO's first ruling on national security will stand uncontested. Now what this is about is about Russia and Ukraine, and basically they— Russia and Ukraine said they won't appeal a landmark trade decision which the WTO upheld Moscow's right to claim key exemption to international trade rules that allows governments to take any action it considers necessary for the protection of its essential security interests. Now, the WTO, in summary, have been very reluctant to get into this political debate, uh, but what's happened here is Trump obviously has used, uh, the premise of national security as his reasoning behind why he initiated in the first place this trade war with China. Um, and so Ukraine says the decision that's happened in their case, may help curb unjustified protectionism, which has really been one of the core issues brought about from a kind of top-level point of view. So has this been a bit of a setback for Trump? I don't necessarily think so, but I think it's just something to be aware of because it is the first ruling on national security from the WTO, and it will stand uncontested at this point. Point. The whole idea here about will it limit potentially the reasoning behind him being able to bring forward type of action in the future. Larry Kudlow sounding a little bit like a broken record. This is just the administration's, I guess, verbal management of this ongoing situation. He quote, very good progress being made in these China talks. So absolutely nothing really new there. All right, moving on, let's have a look at something else. I mean, the trade story I think is, I guess, ongoing. I'd say status quo. Nothing from everything I've just discussed really changes the mold a great deal. So if anything, we remain in this whole holding pattern of kind of mild positivity on that issue. That though does help the narrative for crude oil oil. We've had something come out overnight for crude, and obviously Tuesday night we get the API inventories. So the ellipse I've got here on the chart marks up the release at half past 9 last night. And as you can see here, we popped a little higher. We added, what, from the opening price to the high, about 20 cents or so to price activity. And we've grinded it up in the overnight session. I'd say probably from a global growth perspective, possibly the Chinese data just helping reassure some investors as well on the demand side, possibly. And we've drifted a little higher as I speak though, just breaking the late Asia-Pacific range slightly. So a little bit of a pullback from the most elevated levels that we've had in WTI earlier this morning when we first came in. Quite usual, this, this is probably a combination of the initial European entrance Here we retest the high at 6458 intraday, which is kind of a byproduct of the Chinese side, but the API is overnight. And then we've just had a little bit of profit taking perhaps on, on that move and just breached now that late Asia-Pac range, just exacerbating some of that recent price movement. On a longer time frame though, obviously this is a, a pretty key area technically for, for crude at the moment. We've got up to around this 64.5, 65 level on the handle, obviously psychological, and that brings into play the previous points of, of support that we've had. So I think this is a reasonable and logical target that obviously Sam and I have been looking at for some time on this pretty persistent rally that we've had in crude. And what's happened overnight, we whether or not it's going to be— and it hasn't as yet been justified to really kick on from here— as being the API inventories. So the numbers last night were bullish in a sense that crude— if I make this a little bit bigger— crude number was a drawdown of 3 million. Expectations on the street were for a build of 2.3. Cushing, a draw of 1.5 million. Gasoline, the 9th draw in a row, a draw of just over 3.5 million distillates, a bill of 2.3 million. So yeah, data helping kind of add to the idea of the tightness in the market, if you like. But I haven't really read anything new this morning from any OPEC-related nation. Did you accidentally summon me? Suri's trying to get in on some briefing action here on my watch, but Yeah, nothing other than that to report really. I guess the topside level that I'd be watching here is the 64.5, 65. Now there's two ways of really looking at this. Overall, I would say that I actually think this is a pretty good area. I would say between— if I just remove this rectangle here— if the DOE infantry numbers this afternoon are relatively in line this rectangle I've just drawn, I'd not be surprised to see the market remain in a little bit of a, uh, consolidation in this area. So if I just kind of mark this up here, let me just remove this rectangle and remark it. So kind of this area here, I'd expect the price to remain around 63 to 64.80 type of level. The only risks to this perhaps, uh, could be a technical breach of the trend line should we get up to it. But I don't really think that that's time-wise— we've got enough time to get to that point. Downside support point 63, I think, looks pretty firm given on the balance of the technicals and the fundamentals. Um, and so it's just really the DOE. If we had a shockingly large drawdown, which of course with this data given its high degree of volatility is is not uncommon, but I'm talking about if we had a drawdown of maybe minus 10 million type, which would be statistically a slight anomaly but a possibility, albeit a low one, that could be enough to get us above this technical level here at around 6479 in the futures. If we did get, let's say, a 20, 30, 50-cent break, I think that could add then as a decent platform form for then the kind of next move up. And I guess logical target here I'd probably be looking at is just the 65 handle. I'd say that would be probably a pretty logical and easy move for the price to get to quite rapidly if we broke 79 in the futures, which has held the price action so far this week. Beyond that point, then we'd probably looking up at the 74 mark and then not higher up and we get down to those September lows at around 6686. But there's no way we're going to get up there. Well, I say that, there's a very low chance we'll get up there as soon as today. But as I said, the balance lies in the DOE's. But I just wonder about the market's risk appetite or ability from a volume perspective, just given the Easter holidays looming. All right, couple of earnings reports, and I'll run through these from a very kind of top level of approach, just so you're aware of them. I won't go into the kind of granular level detail, but Netflix, one of the FANG names, of course always draws a bit of attention, just given the fact that, if you can believe it, Netflix shares have rallied about 30% since the beginning of the year. So very much like in the case of 2018 when we were originally hitting all-time highs, Netflix, these kind of growth-related stocks very much outperform the benchmark S&P. And that being the case again so far in 2019, their shares overall dipped 1%, so they were a little bit disappointing overall. They actually, actually posted their strongest quarter ever. What happened was their video streaming service signed up 9.6 6 million subscribers in the first 3 months of the year, which was ahead of forecasts. However, for Q2, they said that they're going to aim for a net addition of 5 million subscribers, and that is way lower than analysts have predicted of 6 million. Um, now not only is the guidance a little soft, um, perhaps then one thing that people are looking at here about the reasoning why they're guiding lower on their subscription rates, which is key to their model of which people typically invest in these types of future potential growth stocks is competition. And what's happened is that Disney last week have unveiled their own new streaming service, about half the price of a standard Netflix subscription. Apple, of course, came out with that event in March where they unveiled a new streaming service. None of these of which Netflix have said they see as really competing with them. The one thing that's probably going to be more the cause for concern here is that Netflix have been upping their prices across various different markets. One of the biggest and key ones of course has been that of the US and also parts of mainland Europe as well. So yeah, Netflix, interesting as a release very small movement overnight. It's not been to the size of what we've seen before in 2018 where the shares have flown 10, 12, 15% in after-hour trade. I'd say the story's kind of moved on since then, and that kind of, in a sense, I think summarizes this earnings season overall. IBM was another one I thought I would mention. Their shares were down overnight. They're obviously a sizable company. They reported their worst revenue in 17 years. A particular weakness was seen in their cloud and AI technology division, which they've kind of pinned a lot of their future hopes on. And so as a byproduct of that, the marketplace is quite a great emphasis on that particular area, and its performance of which was disappointing. One company though, the buck the trend, Qualcomm— not the biggest company in the world, but a sizable one. And again, this isn't really transferable from an index trading point of view, but from a single stock, their shares jumped 23% overnight. I mean, that is huge as for a one singular move. But it's been a pretty huge story that's broken for Qualcomm overnight. They've basically won a major victory in wide-ranging legal dispute. Now, as far as I'm aware, this has been going on for, for a long time, and they've reached a settlement that's called for the iPhone to once again use Qualcomm modem chips. Now, what happened was, as this legal dispute was going on, Apple had been using Intel chips, but overnight following this legal ruling, Intel now have pulled and have now stopped altogether doing modem chips for for phones because Qualcomm— Apple now needs to use Qualcomm's, uh, and as well as part of the settlement give back payment because it's gone in favor of Qualcomm in the ruling. So yeah, big news for them. Their shares up 23% on the back of that overnight. Uh, final things to mention, uh, because I know a couple of you look at the antipodean currencies A little bit of a disconnect has happened between the Kiwi and the Aussie. The Aussie very much trading on, on generally the front foot, having appreciated overnight on the back of the Chinese data that came out. On the flip side though, the New Zealand dollar dropping to a 3-month low as their local domestic CPI number did disappoint against market expectations. So just to make that clear. All right, quick look at the calendar. Uh, what have we got for the, for the session ahead? Well, 9:30, uh, it's a cluster of inflation information coming out of the UK. Obviously the headline reading being UK CPI. It's expected to creep up. The median consensus is for a 2% reading, up 0.1 from 1.9. We've got a range of 1.8 to 2.2%. This is what this looks like in recent times. So we are looking out for actual continuation of improvement in inflation. So although you might think demand generally should be falling given the uncertainty about Brexit, what there has been a lot of in recent economic data that's been fairly apparent, particularly on the, the more manufacturing side, has been this idea of front-loading in order to get ahead of potential disruptions that a no-deal or a very messy Brexit could have. And so if anything, demand side has been held up relatively well. Consumer confidence, albeit low, hasn't really detracted too much from people's spending overall. And wages have continued to be relatively robust in comparison to recent years. Is which helps mitigate that kind of low confidence issue. So yeah, I'm not expecting huge movement on the back of this. It's probably one of the things to look out for, for this morning. Um, although as I said, I'm not expecting big moves in cable on the back of this. I would of course not be in a position or recommend being in a position as the data comes out because there is the ability for it to move, probably cable, a decent 20-30 pip move if it is an outlying number, possibly even more if we were to break the upper bound of the range. I guess 131 handle, 131.05 in the futures, has been the resistance that's held markets from the overnight session. And then the intraday low from yesterday, I should say very early in the Asia-Pacific region, was down here, which brings into play— if I just mark it up— this kind of low point from what was yesterday. Well, the overnight session, excluding the slight breakout that we had overnight from the range low from the 9th to where we were here, I'd probably be looking at that range, 130.76 to the pivot uh, something to be aware of in cable today. Uh, finally for the US afternoon, what else have we got? Um, well, you've got Eurozone, uh, final HICP just before that to be aware of. Those are final readings, so not expecting too much movement on the back of that for European assets. Uh, for the US session, uh, international trade goods balance, uh, again not expecting too much from Canada though, the currency, obviously the loonie, very responsive to any updates that we get there. And it is inflation readings alongside trade balance. So if you are looking at the CAD, that definitely will be a market mover. But otherwise, pretty quiet on the US side until we get the oil inventories a bit later on at 3:30. Speakers again, let me just make this a bit bigger. 2 PM this afternoon, Mark Carney, the Bank of England and one of the ECB members will be speaking at a global financial system conference. ECB's Lautenschlager, who sits on the executive panel, being German, typically sits on the slightly hawkish side, albeit given she is not the head of the Bundesbank but on the supervisory board or the executive board, she really— relatively, does she say anything market-moving? She tends to be a little bit more clustered with the kind of the general stance of the central bank. So I don't anticipate too much risk around her speech. Then you've got Fed's Harker, a non-voter. Fed's Bullard, probably the most interesting one from the US speakers today because he is fairly opinionated, likes to put forward his viewpoint, and he is speaking on US economy and monetary policy, but he's not talking until 5:30 this evening. North American earnings reports Again, nothing I would say here that's going to shake up from an index futures trading point of view in the equity space. All of these are relatively, although mid-cap, aren't going to have that ability to really move markets either from a sentiment or a size point of view from an index weighting perspective. All right, that is it. I'm gonna leave it at that, let you guys get on with things, and I wish you a great day ahead. I'll see you in the chat room. Any questions, let me know. Just to be clear, Sam is away today and tomorrow, so if there's any questions, please feel free to put them in the chat room. Happy to help. Tommaso here as well. All right guys, have a good day.
More from Anthony


Inside the Biggest Banking Stories You Need to Know This Week (Anthropic, Diageo, Private Credit)


Inside the Biggest M&A Deals You Need to Know This Week (UniCredit, GameStop, eBay, Eli Lilly)







AI Breakthrough or Hype? Anthropic’s Claude Mythos, Tim Cook Steps Down & LIV Golf Collapse