Fed Division On Taper Timing & Bank of England Preview
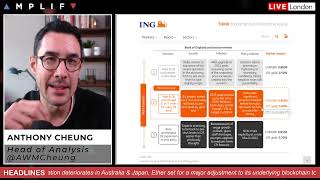
Fed officials sent mixed signals on tapering timing, with hawks Waller and Bullard pushing for sooner action while Daly and Clarida sounded more cautious, roiling markets across stocks, bonds, and currencies. The Bank of England meets at midday with no policy change expected, but traders are watching for clues on QE and sterling could move sharply on guidance.
Chapters
All right, very good morning to you. It's Thursday, the 5th of August. Hope you're doing well. In this briefing, going to talk a little bit about the roller coaster price action we had yesterday. A lot of division, of course, emerging from Federal Reserve officials about the idea of, of what would constitute the timing on tapering and policy normalization. And then we're going to look at the Bank of England, obviously the meeting happening at midday. We'll look at what to expect, key things to look out for, and what might then create subsequent market reaction for sterling in the FX market. A few other updates as well to go over with COVID the situation in Australia and Japan, and then a look at the day ahead as well from other data points like US jobless claims coming out later on this afternoon. But first things first, let's just have a look at the charts. And this morning, after yesterday's quite volatile price activity following some of the data points like ADP and ISM comments out of the Vice Chair of the Fed, Richard Clarida. Things are very quiet this morning, and in fact we're pretty flat across all products. So in the currency space, pretty much unchanged. As to as gold, T-notes still down a touch following the bigger prevailing move lower we had with the pickup in yields following the Clarida comments and data yesterday. And equity markets, we actually finished a bit mixed yesterday on Wall Street. We were down 0.5% S&P, the Dow was down 0.9%, outperforming was the Nasdaq, which finished in marginal positive territory, up about 0.15%. Crude oil is flat, but it's kind of still nursing the general downward trend that we've seen materialize throughout the course of this week. So we're trading at $68 handle at the moment, just coming down in close proximity to last night's kind of levels of support late in the European afternoon and US late session at $67.89, trading $68.07 last But look, let's get straight into it. Let's talk about Clarida first. So yesterday, um, Richard Clarida— and we'll talk about the composition of the FOMC because that is important to determine why and how the market reacts— but Richard Clarida yesterday said the central bank was on track to begin interest rate hikes in 2023 with a possible taper announcement later this year. The comments obviously came after hints the US Treasury may cut their bond sales this fall. ADP employment was at odds with the record ISM Services Index growth that we had, indicating persistent hiring obstacles despite then the improvements that we've had overall in the economy. So yeah, definitely. First off, Clarida, this is why, again, to refresh your memory, you really need to be hot on your FOMC members because we have had Kaplan speak overnight. So Kaplan, who's a non-voting member at the moment, said that and reiterated tapering should start soon and be gradual. And so definitely a hawkish comment by, by saying that it should start soon. But look, Kaplan is right down here, not only a non-voter like Bullard, but with Bullard and Waller being the two people that have really been the outspoken hawks that we've seen earlier this week and at the back end of last week. They are literally the three most obvious candidates to take that type of stance. Now, the reason why Clarida is so important is twofold. One, because Clarida is the vice chair, and the vice chair, same with any other central bank, tends to be fairly aligned with the chairman or chairperson themselves. And so if Clarida is thinking that, the market tends to make the assumption that that's probably what Powell's thinking. And Clarida and Powell definitely sit much more kind of center dove in terms of on the scale of hawks and doves. So definitely nowhere near as dovish as the Kashkari or Brainards of this world. But definitely seeing Clarida come out and make such comments is part of the reason why you saw such an immediate reaction to that yesterday. One of the things then, having a look here, you definitely needed to be on your toes yesterday to take advantage of some of that price action because, I mean, this is just looking at the euro and just talking through the general day. We did see shortly after the European Open a bit of dollar strength came in, which weighed on the pair. You can see a bit of extension on that wick on the breakdown of some of these previous points of support and the market ran down lower. Only then to recover. And ADP came out obviously, and that created this move. And ADP was quite a substantial miss on expectations, and obviously that's seen often as the precursor for payrolls, and a lot of people looking at that for direction. You know, if you think about what Waller was saying from the Fed just the other day, he said that yeah, they could, they could start tapering as soon as October, which is super early, but it would be conditional on seeing two very strong back-to-back consecutive jobs reports, and the ADP one sets that up not to materialize. Correlation questionable between the two data points. One being weak doesn't necessarily— the other will repeat, but definitely that would have propelled some of the market thinking yesterday. Then you had ISM come out and the headline figure exceptionally strong, but the Carida comments came out and we saw the absolute reverse. So then dollar strength and then here we are at the moment. So yeah, 3 really distinct phases to that euro move, which meant for very seesaw price action. So perhaps a day of opportunity for the more activist trader, but certainly, you know, otherwise if you're new to the marketplace, you know, this can be quite a tricky environment to navigate. And, you know, one thing we are seeing at the moment is quite a lot of division amongst the Fed members. But what that generally says to me then— and when I say division, we did have overnight, kind of late, 11 PM London time or so last night, Fed's Mary Daly spoke. Now, Daly is a voter, and she said her model outlook is the Fed will be able to taper later this year or early next, but emphasized data dependency. So a little bit more kind of measured in the sense that, look, we need to see the data shape up to constitute that, rather than just being explicit and we should be tapering at this particular calendar date. Um, but again, going back, looking at the sheet, Daly definitely sits again alongside Powell, Clarida, Daly on the slightly more dovish side of proceedings. So, you know, all, all in all, you might say that the division is a bit confusing But to me, it just says that we're getting ever closer to the formalization of tapering. So it's not as if tapering is just going to be taken off the table because maybe COVID's rising in certain states in America, which is still the case. I don't think that's the case. I think it's— we are going to taper. It's just a matter of the nuance of when exactly that is going to be initiated. And what you're starting to see then is a more and more gradually the hawks are there and the doves are coming to that, that position. But it will take a bit of time. I think data dependency really is the key thing. And I think just given the mixed bag of data yesterday, it puts all the more emphasis on payrolls being quite important. It's almost like it's becoming significant ammunition to support the argument for both camps. Bad payrolls, well, the doves feel vindicated. Look, we remain data dependent, we'll continue to track the economic recovery and continue, but now's not the time quite yet to be initiating more detail on tapering. And then we look to Jackson Hole. If payrolls comes out super strong, then again, the hawks are going to feel that they've got validity to support that view and we should be pushing ahead And then the market might continue to price in quicker the fact that Jackson Hole is going to be the initial kind of starting gun then for the tapering to really start being discussed in more depth at that point. So for me, payrolls now has taken on, given what we had yesterday, kind of even more importance. And so yeah, excited to be doing that. And if you're watching this live on YouTube, if you're watching this on YouTube, I'm going to be covering that live on the channel, so don't forget to subscribe to the YouTube channel, um, hit the bell icon, you'll be notified as soon as we go live for that as well. But it'll be around 1 PM London for the release. All right, well look, let's jump straight into the Bank of England then. What are we expecting? This is happening at midday and the Bank of England are set to take steps toward policy or tightening monetary policy. So a couple of things to be aware of here, and I did talk about the Shadow MPC yesterday and they were super kind of bullish in the sense that— I should say hawkish— in that they should stop QE just given the economic improvements that we've had. But I definitely don't think that is the case, and the Street agrees with me. The consensus is that there's not going to be any policy change today. So what is it that we're actually looking for? Well, there's kind of room to be cautiously optimistic given current developments we've seen in the economy. But two real major points, really. There's the Delta variant, which although, you know, we're a— as an advanced nation, we're way ahead in vaccinations comparative to peers. But the idea being is that the Delta variant is still, you know, very much present right now. And so that's point one. And then point two is the idea that until more of the nearly 2 million people on the government's furlough program are back at work, it's hard really to determine then what type of unemployment that that might constitute when that starts to roll off in the coming months. So with those two points, it kind of lends its hand to, yes, probably there's enough for the hawks, like what we've seen in recent commentary from Dave Ramsden and Michael Saunders, to constitute the fact that they might call, probably will call, for an end to QE today. but the rest will probably say now's not the time. And so therefore vote to just continue, um, on that QE process at this point in time. So again, just to re— refresh your memory, here is the, the board as it stands. And what we're looking for today is, remember, with the Bank of England, you get the statement, you get the minutes, you get the vote split, and today we get the monetary policy report, which is their outlook and forecast for growth in GDP. So this is one of the more busy events for the, for the Bank of England. The actual policy one, the rate, is kind of a no-brainer, so you can, you can scrap that one. The vote split could constitute an initial market reaction for the pound. The consensus here is for a 6-2 split to keep QE as it is, the dissenters being Ramsden and Saunders. If you got, let's say hypothetically, Broadbent joined them as a trio and then the split was 5-3, that definitely would inject a lot of pace in the pound in the immediate reaction. If you get a unanimous and it's 8-0, the opposite would happen and the pound might come under some quick pressure and snap through some of its relative technical support. And actually on that point, you know, just having a look from the technicals on sterling at the moment, pretty much locked in a range for the time being here in sterling. As you can see, this has been the low since the week really has been underway. So just awaiting that bank decision to see what happens. Certainly a vote split would, would help us bump back up towards the top end of this range of which we were testing yesterday. But a unanimous 8-nil vote certainly would break down through here and likely be retesting down that lower bound from what we had on the 28th, if not up to that area of resistance we had back on the 26th, 27th toward the S2 on the daily pivot. So How long and how sustained these types of price spikes might be, though, are largely constituted around other factors. So for one, the depth of the minutes and discussions, but then also we get the latest forecasts coming out. So the Bank of England are going to unveil its new quarterly forecasts, and on paper the story is still likely to be fairly upbeat. So Looking at this, this is the ING crib sheet. I have shared this on Twitter if you'd like it in more detail to have it to hand when the event happens. But looking at the base case that ING are looking for, and to explain this graphic, you've got the actual policy decision on the left, you've got the, the kind of main staples of the forecast, so growth and inflation, and then the policy outlook. And then going from top dovish to bottom, most hawkish scenario. Excuse me, let me share my screen. So here, most hawkish to most dovish, uh, so most dovish to most hawkish scenarios, top to bottom. Growth, inflation, policy outlook on the left-hand side. So the base case scenario here is you get a vote split, and so that's the first point we've talked about. Then on growth, Q3 growth scaled back, but economy still back to pre-virus levels by year end. On the inflation side, 2021 peak revised up to circa 3.5%. Remember, inflation has been surprising to the upside in latest UK CPI prints. So don't take that as a real factor to, to kind of scare you, thinking, wow, that's a major kind of bullish signal. They see future inflation higher. The market is already well adjusted to the fact that inflation is probably, in terms of the Bank of England's guidance, outdated from when they last issued their previous forecast going back, um, a few months back. And then on a policy outlook, reiterate significant progress needed before stimulus removed, no hint on the rate hike timing. So that's the base case. Hawkish outcome on that side would certainly be hints more explicitly at a rate hike next year. On a dovish side, cautious about premature tightening of monetary conditions, uh, and so forth. The other point that a lot of analysts have highlighted as well is to look for any comment on balance sheet guidance. And what this is talking about, to try and make it just easy to understand, is about quantitative tightening. So already giving guidance about when we do stop at some point in the future QE, what would be the conditionality to then start allowing bonds to mature without reinvesting and therefore the debt holdings of the bank start to decline and the balance sheet starts to reduce, which is another process in the normalization, um, kind of synchronization, if you like. I don't think that's probably going to happen today. It's probably a little bit too soon. There's probably a few obstacles we need to tackle yet, and the baseline being is that we're not actually expecting them to do any real policy changes here. So Yeah, these are the things we're looking for. Um, obviously, um, we'll be coming— we'll be covering this, um, during the, the actual live session on Amplify Live if you'd like to join us. Um, but otherwise, quick roundup of some of the other news flow to be aware of. On the COVID side, Sydney has reported its worst day of COVID-19 pandemic with 5 deaths and a record rise in locally acquired infections. Um, so that Delta variant. Still, they're having difficulties getting that under control at the moment. And Japan, um, has expanded its emergency restrictions to 8 more prefectures overnight to fight the, the latest outbreak. On the actual calendar, it is pretty quiet this morning, so really just leads us up into midday for the Bank of England. Don't forget, because this is a monetary policy, one of the quarterly reports from the Bank of England with their forecasts. It means you will also get the Andrew Bailey governor press conference happening at 1 o'clock. So the rate decision, minutes, and vote split all happening at 12, and then he will speak 1 hour after. Otherwise, from the US session, Challenger layoffs, just another small input in towards then forming a better view for payrolls on Friday. Initial jobless expected to drop back down to 384 from 400K last week. And then from a speak perspective, the hawk Waller comes back speaking on central bank digital currency though, so, um, not expected to comment on the economy or tapering, but given his— how vocal he's been on that, we're keeping an eye out. That'll be at 3 PM. Fixed income supply out of Spain and France this morning. And then from an earnings perspective, Um, they're probably already out, but I'll leave that for you guys to just have a look at. But so you're aware, some of the DAX giants— Bayer, Siemens— this morning have reported as well, just so it's on your radar. All right, that is it. I'll leave it there, let you guys get on with the day. Um, I will share a link to the crib sheet as well in the link to this video when it goes up on YouTube, so Check it out if it's useful and have a good day ahead. Thanks very much.
More from Anthony


Inside the Biggest Banking Stories You Need to Know This Week (Anthropic, Diageo, Private Credit)


Inside the Biggest M&A Deals You Need to Know This Week (UniCredit, GameStop, eBay, Eli Lilly)







AI Breakthrough or Hype? Anthropic’s Claude Mythos, Tim Cook Steps Down & LIV Golf Collapse