Markets Stablise But Can The USD Strengthen Further?
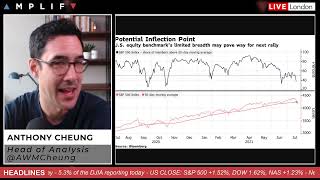
In this July 21, 2021 market briefing, the presenter reviews the recent rebound in U.S. equities after a COVID‑Delta‑driven sell‑off, emphasizing technical support from the S&P 500’s 50‑day moving average. He links market behavior to the Delta variant’s impact on economic reopening and the Federal Reserve’s likely accommodative stance, noting that the pandemic shock may shape tapering timelines. The analysis then shifts to foreign exchange, highlighting a modest rise in the DXY, technical dynamics in GBP/USD (Cable), EUR/USD, and AUD/USD, and the broader implications of a stronger dollar for these pairs. Precious metals are examined, with gold and silver showing divergent moves despite the dollar’s strength. Crude oil is discussed in light of unexpected API inventory builds versus Cushing draws, setting the stage for upcoming DOE data. The briefing covers corporate news, notably Netflix’s Q2 subscriber beat but weaker guidance, and the political backdrop of the stalled U.S. infrastructure bill. It also notes improving semiconductor supply, its effect on auto‑chip shortages, and recent gains in U.S. automakers. Brexit developments are summarized, focusing on the UK’s new trade‑border strategy with the EU and its impact on the pound. Finally, the presenter outlines a quiet economic calendar—ECB rate decision, flash PMI, oil inventories, a large U.S. bond auction, and earnings from Coca‑Cola, Johnson & Johnson, and Verizon—while stressing that macro themes will continue to drive short‑term market moves.
Chapters
Okay, very good morning folks, it is Wednesday the 21st of July, so I hope you're doing well and good to be back in the hot seat again. Looks like I've missed quite an interesting 2 days in the markets and yeah, last night we finished up 1.5% in the S&P, around 1.62% in the Dow and 1.23% in the NASDAQ 100 and so reversing in large part a number of the losses that were observed on Monday as people started to freak out a little bit about the global impact on the recovery, given the emphasis on the Delta spread of COVID-19. So things stabilized yesterday. This is looking at a chart of the S&P 500 and with particular emphasis Bloomberg were putting on last night on the 50-day moving average, which you can see on the bottom chart on the pink line, which the market's responded to well, really going all the way back through year to date and in fact taking us back to really January, February, March, May, and June, as well as then earlier this week having tested at that key level before some dip buyers have come back in. Now, in terms of where we're trading at the moment, I mean, we were looking at the S&P chart, I think it was yesterday morning in the briefing, and on the daily, obviously a nice respect of that rising trend line with that 50 DMA just helping technically find a bit of a footing on the downside. I did find the narrative of COVID a little bit difficult to comprehend of being such a weighted impact, and I think yesterday and beginning of the week really goes to show just how behavioral the market is, because the Delta variant, as we know, is highly transmissible, more so than any other permutation of the virus so far. And it was always going to become the most dominant strain of COVID-19, and subsequently then likely to impede economies' ability to reopen perhaps on the predefined schedules that they, they were putting out. And so I don't think it's really wholly surprising, but certainly it's, it's caused the market to question what the next 6 months of this year looks like. And so I think the, the Monday dip was a little bit like calendar, and then the kind of trigger points all fell in place and the market started to just trade with the momentum. So coming in yesterday, you know, the most important mechanism of course is that you know, from a policy setting point of view, which ultimately is, is key for the medium-term direction. If anything, this just plays into the hands of the Fed to keep accommodative policy for as long as possible, really, to ensure a smooth recovery. And this Delta kind of spook, if you like, at the beginning of the week is the key component, of course, of which is going to define the pace and time of of tapering. So I think, uh, respect of the bounce, technical indicators, I think fundamentally, I think perhaps Monday a little bit overdone on the behavioral side, um, people just chasing that move downward. And so then seeing a nice bounce from yesterday's session, um, elsewhere otherwise from this morning, the other thing is looking at the dollar. The dollar, despite what I've just mentioned about the Fed, um, the dollar continues to remain a little bit firmer. It's just popped up a little bit as UK and European participants have come into the market. We're trading up about 0.1% in the DXY. But on the daily chart, this is looking at the DXY, and we were looking about a week ago on that trend line going back from, I guess this was September of last year, the retest that we had at the end of March, beginning of April, and that was shackling some of the dollar's appreciation um, earlier in the month. But a bit of a breakout of that does now technically mean I think the Dixie's got a little bit of room still to go on the upside. And that's going to be quite telling, of course, for these major pairs. I thought Cable was particularly interesting because we were talking about this key level of testing that double bottom of the March-April low. It's on the daily chart in Cable. And you can see then yesterday a breakdown of that saw us have a quick run down to that level that was last printed going to the early February, the 4th of February, of which we respected pretty much to the tick before finding a bit of a floor. Still trading at the moment around the 136 handle, and so within a 25-pip or so proximity to that low. So it still warrants watching that at the moment, as I said, with some technical space in the Dixie for upside. And with that as well then means that the EURUSD pair is also a little bit susceptible to a retest down at the lower bound of its recent price movement. Yesterday's session low does coincide with around the S1 on the daily pivots in the futures, so worth keeping an eye on that as well. But looking a little bit heavy here with some space on the technicals for a bit of a deeper move, um, to materialize, at least for the time being, in those major currency pairs. The other one, of course, you know, wrapping in the COVID situation, this is looking at AUD/USD. On a, on a daily chart. And Australia has really been battling on the COVID front in New South Wales. We've had Sydney on repeated rollover lockdowns because of the spread of the Delta variant, and then also Melbourne as well. So two of the most populous areas of Australia. And despite the economic improvements that we're seeing, you know, really spectacular jobs market return that we've had, that's consequently led to some more of the hawkish tone of late from the central bank. The idea being that the second half of the year is probably going to look materially different from a growth perspective, and all of this getting baked into price. And so again, from a technical perspective, we've still got a little way to run until we get down to really the late November lows in AUDUSD, which would be around 72.66. We're trading at 73 handle at the moment. So The similarities across these major dollar-based pairs is that there's, there's some room here perhaps for an extension of some of the directional trend that's been materializing, materializing of late, at least until the dollar index starts to find a bit of a resistance point a bit further up. We're trading 93.12 at the moment. 93.50 is the key area which would, which marked that late March, early April top in the Dixie. Interesting from a correlation point of view, something to be aware of despite the dollar strength at the moment. And I'm focusing much more on where we are at 7 AM this morning in London. Precious metals have actually picked up, and so gold and silver, which would typically move in an inverse relationship to the dollar, that's not happening this morning. So worth keeping that in mind and updating that in terms of the way that you're looking at correlations in the very short term. Gold's just popped up to have a bit of resistance met at its pivot, but just eradicating overnight losses and back to pretty much flat on the session. And a pretty similar drill for silver, which actually silver had a nice technical move through. Let me just quickly mark this up. So just take off my marker. So silver's just kind of broke out of that range that was relatively holding through the latter part of yesterday's session. Just popped through there, and the pivot— when the pivot level was also a pretty strategic point technically of resistance, and that's just helped us extend the, the gains up to the nearest clearest point, which was the R1 and the previous top of that range that was seen before the downward move that came when the US entered the session yesterday. So nice technical breaks there of moves helping in the precious space. Again, that move there, the break of the secondary level with the pivot, and then a momentum-chasing exit at the first point, the R1, with those previous highs. So worth bearing that in mind for, for silver. Other asset classes, how are they looking this morning? You've got WTI crude, obviously got, got hit quite badly over the last couple of sessions with the whole COVID demand implications. And we've had a bit of a recovery yesterday, but we're still trading generally lower. So we're locked in a bit of a range at the moment between pivot 6634 and the upside late US high coinciding with the R1 on the futures market today, the daily pivots at around 6763 or so. So just looking at that as the near-term price activity at the moment, you can see quite a prevalent candle here of a negative fashion that was printed at half 9. And the rationale for that, of course, was that we had the crude oil inventories from the API last night. We saw a build of 806,000. Analysts were anticipating a drawdown around 5.5 million. So a very surprise build there is what jolted prices lower. Cushing was a drawdown, though, of 3.57 million. That's pretty deep. And gasoline a build of 3.31 million build. So quite conflicting signals there on the data, quite a knee-jerk reaction lower overnight. And the reference point now is set for the DOE this afternoon in the inventory data, but not too much in the way of a lasting reaction there, but certainly did bump prices a little bit in the overnight late session. All right. Well, let's get stuck into a couple of headlines and talk about a few different things. And going to kick things off first with Netflix. Netflix had their earnings last night and we did see some quite large gyrations in their share price in extended trade. They added 1.54 million customers in Q2. That was actually above analyst expectations of 1.12 million and their own April estimate that they issued of 1 billion. So they exceeded as far as Q2 was concerned, but their outlook was what caused the initial fall of in excess of 6% in aftermarket trade. And that's because they expect to sign up 3.5 million new customers in the period ahead, trailing the 5.86 million that analysts were projecting. So significantly lower amount for the forthcoming quarter. Their shares did initially drop about 6.6%, but actually if you look at them thereafter, they recovered quite quickly. The intrigue generally over their plans to delve in the video game market somewhat helping offset the weakness in its core business. And their shares actually pretty flat in the end, in fact. So actually, if you think about it, I think it was pretty astute timing really. They put out that news on the gaming side last week, they would have known full well what their subscriber numbers were going to look like, and so why not put in this tantalizing prospects of tapping into this humongous market of gaming to offset then quite a negative period ahead in terms of your core business. So some could argue fairly well managed there from Netflix, but they've obviously got to deliver on the goods. And I think it was into the end of the year when they're anticipating getting this video game side of their business up and running. Something to be mindful of on the infrastructure side. Um, this kind of drags on again. Where are we with this? So Senator Majority Leader Chuck Schumer's attempt to begin Senate debate today is still unfinished. Bipartisan infrastructure bill is on track to fail. The Republicans saying that there's no way a deal can be reached by then, that they won't vote to open debate without text spelling out the deal. Schumer on Monday scheduled a Wednesday test vote to begin debate. It would need 60 votes, including 10 Republicans, if all Democrats and independents voted Yes. So I'd say the likelihood of this is that they're not going to kick off those discussions, those deliberations just yet. Again, from a politics point of view in the US, it's kind of they have a vote to have a vote, and then that leads to initial opening conversations before they then start to get into the nuts and bolts of the actual voting on the deal. So a lot of the Democrats looking at this as a potential opportunity to just push things forward. And so that then they can start discussing and fleshing out the deal. The Republicans want something more definitive on the table. So this isn't really, I would say, cause for concern, and markets clearly aren't reflecting that at the moment. And I think that remains the case. This is kind of just dragging its heels a little bit, but we'll monitor it as we go further forward. But I don't think it's likely to begin that debate today. Updates pending. Another thing that I thought was particularly interesting was this: the Biden administration officials said yesterday that they're starting to see signs of relief for the global semiconductor supply shortage. And this is particularly important, of course, because it is that supply shortage which has been the chief reason that's really elevated used car and truck prices, which, as you'll know, has made up the proportional impact of the underlying CPI price pressures in North America, but also globally experiencing the same thing here with used cars, um, in the likes of the UK as well. So the thing that they're talking about now is commitments from manufacturers in the US to make more automotive-grade chips for carmakers that have had to idle their production and thus leading to those price squeezes that we've been seeing. Shares of Ford, GM, Chrysler's parent company extended gains on the back of that news during US trading hours, and they all touched intraday highs at the point of when that hit. But I'm looking at it more from looking to just address a pressure point at the moment that's leading to a lot of these inflation pressures, these kind of pandemic idiosyncrasies as we were discussing last week. On the Brexit side, as I showed you, the pound technically on a daily chart is looking a little bit bearish at the moment, so worth keeping that in mind for any price recovery that we see short-term intraday because we've now got a pretty decent roof to price that was a strong floor year to date. So things are kind of stacking up a little bit against the pound. You've got COVID cases which continue to head north, but this is largely as expected. But some of the modeling now suggesting that things might well start heading in the direction that was probably worse than what many had pre-calculated. So definitely we wait for those numbers to really ratify that. And the other thing is the amount of people who are getting pinged to then self-isolate. I mean, I don't know how many of you guys watching this are talking to people just generally in your life, friends and family, but it seems to me like everyone's got pinged. And I know a lot of parents having a young child who are at school and things like that, seems like most of school years they're also at home, and obviously that impacts parents' ability to be able to go, go to work and so on. And so I do think that that comes, as I was discussing earlier in the week, with economic impact in that respect, because the number of self-isolated people is expected to grow substantially over the period ahead, particularly now that we've gone through the latest unlocking, if you like, of restrictions. So that, and now Brexit making a comeback as And it's likely to hit the headlines again today. And the reason for that is the UK is to put itself on collision course with Brussels by unveiling a new set of demands that would radically overhaul post-Brexit trading arrangements between Britain and Northern Ireland. So again, that contentious issue of how to deal with the trade with the Irish Sea and Northern Ireland land border with, with the Republic. In a move that officials called a wholesale change of approach, Lord David Frost Cabinet Office minister, will outline the strategy that seeks to eliminate most of the checks on the Irish Sea trade border that came into force in January. And they're using, I think it's clause 16 of the actual document that they had signed on this initial agreement, which is, you know, without going into details, it's kind of like, well, if this condition isn't met, then it means that this clause can be actioned and hence the overhaul can be made. And so that's obviously going to be a highly contested point from the Europeans' point of view, what David Frost is going to try to enforce. So it's just the latest, really. I don't think in itself is particularly surprising, so therefore I don't think it's particularly that impactful. But it's the cumulative impact that we're seeing at the moment for sterling, uh, just stacking up with then the space technically, I think, for the dollar to see perhaps a little bit of further upside in the short term, which when looking at those major currency dollar-based pairs pairs does show that there's a little bit of room there for continuation of the, the current trends as they exist, barring anything unexpected at this point. So let's have a look at the calendar for today. It's pretty quiet, in fact, and we've known this throughout the whole week. Um, tomorrow you get the ECB interest rate meeting, which is always going to be quite interesting, and then we've got the flash PMI data on Friday. So this week, from a calendar perspective, has definitely been quiet, but that doesn't mean obviously the market's not been without some substantial price movement, which has typically been led by these more top-level macro themes, of course. But now we've had the kind of the negative scare move, the risk-off, and then the risk-on return yesterday. Things have kind of leveled out a little bit. So be interested to see how today plays out and whether or not we just kind of go in cruise control a little bit and wait for the ECB then tomorrow and that data on Friday. Today's calendar equally so is pretty dull. There's really nothing going on today from a data perspective. You've got the DOE oil inventories as per normal at 3:30 London time this afternoon. From a fixed income perspective, you've got a German auction with a US $24 billion 20-year bond auction at 6 PM this evening. From a US point of view on the earnings front, a couple of interesting Dow companies Verizon, Johnson Johnson, Coca-Cola. So collectively they would account— I did the numbers this morning— for 5.3% of the entire Dow Jones Industrial Average index, just between those 3 companies alone. So they're all reporting, I believe, pre-market. So definitely worth keeping an eye out for those. Yep, Coke, J&J, Verizon, a few others as well of a more mid-cap size as well reporting today. But keep an eye out for those pre-market collectively for an ability, perhaps depending on the outcome, to move the Dow future. And that's it. So going to leave it there, let you guys get on with the day. Hope you've had a good one so far this week. Glad to be back. Normal service kind of resumes, and I will catch you guys in the Amplify Live chat room. All right, take care.
More from Anthony


Inside the Biggest Banking Stories You Need to Know This Week (Anthropic, Diageo, Private Credit)


Inside the Biggest M&A Deals You Need to Know This Week (UniCredit, GameStop, eBay, Eli Lilly)







AI Breakthrough or Hype? Anthropic’s Claude Mythos, Tim Cook Steps Down & LIV Golf Collapse