More Record Highs In US Stocks But Is The End Coming?
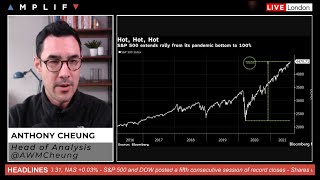
US stocks hit record highs with a 100% gain since March 2020, but the presenter warns a sharp pullback is likely given low volatility levels. Asian markets are weakening amid Delta lockdowns and Chinese military drills near Taiwan, while gold shows a technical breakout toward $1,800-$1,830.
Chapters
Okay, very good morning. It's Tuesday, the 17th of August. Hope you're doing well. I'm going to get you up to speed on the close on Wall Street, where we saw another consecutive— the 5th in a row, in fact— record close on the S&P and the Dow last night. The S&P finished up 0.25%, the Dow about 0.3%, the Nasdaq a slight laggard basically flat on the close. And as you can see to the side of me here, this is a graphic of the S&P 500, and it has now extended its surge from the March 23rd bottom that we saw on the initial onset of the global pandemic last year to where we closed yesterday— a 100% gain from that low. So fairly symbolic there overall. And one thing I would say straight at the get-go in this briefing is that it wouldn't surprise me at all if at some point in the coming sessions or weeks that we see quite a significant singular down day, and people will be very nervous about what that means, and you'll get very much a spun narrative about, you know, the bubble finally popping and these sorts of things. But honestly, I think that it will probably be healthy if there is some type of pullback at some point in the future. We have seen things like the VIX, for example, have been tracking particularly low levels, although options on the VIX would suggest that people are positioning themselves for that day to come in due course. So again, just to be clear, when the market tends to have these particularly narrow, low-volume ranges and we grind out fresh highs and we see consecutive higher prints then at some point or another we get quite a, you know, stairs up, elevator down syndrome. And, and that probably is coming at some point, but it doesn't detract from the fact that we'll probably continue on the, on the path that we have done going forward. But a couple of things then to be aware of, because talking then an extension through into the Asia-Pac session, things certainly not quite so positive, and actually shares were lower in Australia, Hong Kong, China overnight. A few things to be aware of from an overall top level in China in particular. We've seen some economic data obviously yesterday which would constitute a slowing in the momentum of their economic recovery. We've also seen overnight this story, which is essentially Chinese market regulators issuing draft rules overnight aimed at stopping unfair competition on the internet. So just firm further formalization of some of that, um, the catalysts that have been causing negative volatility or negative stock price movement, particularly in the tech sector in mainland China and Hong Kong listed shares. So Tencent was down 3.5%, and yes, overnight Alibaba as well was down about 2.5%. And then you've also got mobility curbs to fight the Delta strain, which is souring the mood as well. Overall in Asia. So we have had in the overnight session, uh, Japan— their government confirmed they're going to seek to extend the coronavirus emergency in Tokyo through to the 12th of September and would extend it in 7 other additional prefectures. And we've also had similar news out of Australia, which I'll touch upon with the RBA minutes in a moment. But otherwise, elsewhere, another thing that you might have read is China's military have said it launched exercises in air and sea near Taiwan. These were live-fire military drills, and this in response to external interference and provocations by Taiwan's independence forces. And this comes, of course, after the US was selling arms to Taiwan, of which then has conflict with China on the sovereignty of that particular region. And so there's a couple things that are going on, and that means in terms of the mood this morning at the European Open, uh, fairly quiet. However, after that pretty spectacular recovery from the initial selling pressure that we saw in US equities from the, um, NYSE open yesterday, we pretty much rallied all the way through into the close. So a bit of a fade then from that in the overnight session, which I don't think is too untoward. So the S&P, NASDAQ futures seeing a little bit lower and the DAX future in step following that general pattern. The DAX future short-term probably worth just keeping half an eye on this level here in the futures at 15,848, just coming close to, to that at the moment, which is the lower bound of the trading range that was seen from yesterday's session. Any breakdown of there, given the way that the DAX tends to move, could see quite a quick spillover down toward 15,804, which was also the S2 on the daily pivots. So worth just keeping a half an eye there on the DAX. Otherwise elsewhere, the 10-year up marginally, 3.5 ticks. Uh, gold has seen a bit of a, a decent breakout this morning, breaking out of the late US session and Asia-Pac range. It's contributed to a bit of a pop higher. This is irrespective of dollar movement, so much more of a technical catalyst for for that explanation behind the gold pop this morning. And on the daily chart for gold, I think we're at a really interesting point here. So this level here, if I just quickly mark it up once again, so those highs that were seen in mid-June, support levels through much of the month of July, we saw the breakdown of course on the better than expected NFP that we had back on the 6th of the month, and we're right back up to test on that, that key area again at 17 kind of 91 in the futures. So I think the daily close here will be important for the bulls to push back up north of 1800 and to bring about again the prospects of moves towards kind of 1825, 1830 on the upside, which would be these highs previously seen last month, or close below to keep us perhaps in a bit of consolidation between this 1791 and 1775 level in this area here. So definitely quite keen to watch that throughout the rest of the session. Other things to be aware of though in terms of the news, and we have had in the overnight session the RBA minutes. The Aussie dollar did weaken in overnight trades, down about 32 pips in the futures market this morning. The bank said it will continue to review its bond buying program based on economic conditions and the health situation as the nation faces lockdowns to combat the Delta variant of coronavirus. The board considered the case for delaying the tapering of bond purchases to $4 billion Aussie dollars a week, currently scheduled for September. And as such, then the combination really of the fact that the COVID situation is deteriorating and they're putting then the weighted bias on their decision-making on that as one of the preconditions, and then also the fact that they considered delaying tapering explains why the Aussies are down touched softer this morning. As I said, Australia as well tackling its own COVID situation. COVID-19 cases are set to rise substantially in Sydney in the coming weeks despite a prolonged lockdown. That was according to authorities in a statement released overnight. They've warned that soaring infections could already put hospitals under enormous strain going forward. Elsewhere, just briefly, latest Fed comment coming out of Eric Rosengren, who is, I must just state, a non-voter. He said he would be supportive announcing another start to tapering in September, conditional then if the US gets another strong labor market report. That labor market report, of course, coming in just around 2 weeks' time now. And then jumping over to vaccines, something to be aware of is that Pfizer and BioNTech have submitted early stage data. To US regulators showing that a third dose of COVID-19 vaccine led to higher levels of protective antibodies when given 8 to 9 months after the initial regime. Um, the companies expect results from a larger final stage trial evaluating the effects of the third booster dose shortly. No set timing, but something to just be aware of. And this also leads us into then this idea of boosters. The US strategic plan, according to sources familiar with the discussions, the Biden administration plans to begin administering COVID-19 booster shots to Americans as early as mid or late September, pending authorization, authorization from the US FDA. So pretty similar timing to what we've heard here in the UK as well. Looking further forward then, in terms of the actual schedule for the rest of today, there's quite a few things to be aware of. We already had the UK data, but it's really had a very much a zero effect on the British pound. Nothing really too exciting there. The ILO unemployment rate came in 0.1 lower than expected at 4.7%. Average earnings ex bonus 7.4%, in line with expectations. So moving kind of swiftly on then, 10 o'clock we get the eurozone Q2 flash GDP estimate and the employment figures as well. And then the focal point will be on US retail sales, which will get at 1:30 Industrial Production at 2:15, NAHB Housing Market Index at 3, and the Weekly API Inventories at 9:30 this evening. As far as US retail sales are concerned, the month-to-month expected at -0.2%, as you can see here, which would be an about-turn from the prior +0.6%. Supply chain issues in the auto sector is said to be weighing on vehicle sales, will be a main culprit for potential downside. However, the core measure is expected to have risen by +0.2% if you strip out then the auto component. Um, analysts at RBC had noted that the month started out strong in terms of— this is a measure of July— but they've seen high-frequency credit card data showing that spending had slowed towards the end of the month of July in itself. So definitely keeping an eye out for that. As ever, just be mindful of the range of the data any revisions to the prior month's figures as well. For the industrial production figure, expected at 0.5%, should post a decent increase with manufacturing likely rebounding after the general decline that was seen in June according to analysts at ING. They also note though that supply chain issues will continue to exert a strong headwind though for growth in that particular sector for the time being, albeit we are looking for a positive number today. Overall, as far as these numbers are concerned, do I think it's going to be a game changer in terms of moving the needle for tapering? Probably not. But nonetheless, I'd definitely be keeping a close eye out for 1:30 for those numbers when they hit. Other things to be aware of, you have got Fed Chair Jerome Powell is speaking today, but off topic, speaking on Fed's work and economic education at a town hall meeting. So not expecting anything explicit on policy, and I very much expect that to be the case given the fact that he's going to be queuing up now and pretty much keeping a tight lip until we get to the Jackson Hole Symposium in around 2 weeks' time at the end of the month. Dove and non-voter Kashkari is going to be speaking at 8:45 London time this evening, so just before the close on the NYSE, but again, very much expecting the opposite of what we've heard from some of the more hawkish Fed members. Hawkish comments about September kind of approval of tapering and so on. And then from an earnings perspective, it's probably worth bearing in mind that Walmart and Home Depot do report today pre-market. Home Depot at 11 AM, Walmart to follow up an hour later at midday. If you combine those two companies, they, they contribute around 9% of the overall index weighting of the Dow Jones Industrial Average. So Definitely worth keeping an eye on them and just to generally see how well the, the brick and mortar retailers are performing at this point in time. And then from a supply point of view in fixed income, a few things to be aware of. You've got some German Schatzauktion, longer dated gilt auction. And that pretty much wraps things up. So pretty short and sweet, but I hope that was helpful. As ever, you can refer to my more in-depth full notes on my Twitter handle. Otherwise, I wish you a good day ahead. Take care.
More from Anthony


Inside the Biggest Banking Stories You Need to Know This Week (Anthropic, Diageo, Private Credit)


Inside the Biggest M&A Deals You Need to Know This Week (UniCredit, GameStop, eBay, Eli Lilly)







AI Breakthrough or Hype? Anthropic’s Claude Mythos, Tim Cook Steps Down & LIV Golf Collapse