Morning Briefing - 17th September 2018
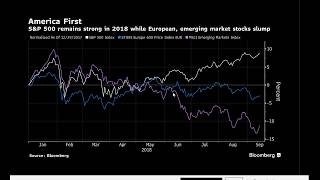
Trump threatens $200 billion in China tariffs, reigniting trade war fears. Shanghai Composite hits its lowest level since 2014 as emerging markets sell off. The S&P 500 sits near all-time highs while European equities struggle with Brexit and political uncertainty.
Chapters
Okay, very good morning, Monday 17th of September. Hope everyone had a, a great weekend. Um, just getting straight into a bit of a recap of some of the major news items from the weekend and what we're looking out for in the week ahead. We'll go through the, the calendar as well through Monday to Friday. Uh, but overall this morning, pretty, pretty tepid open, not too much really for me to comment on in terms of fresh news. Certainly nothing that you're not really already aware of because the predominant focus remains on the US-China trade spat. And after what looked like some positive developments last week have quite quickly come crashing back down again. So as a consequence, we've seen renewed selling pressure in the likes of the emerging markets. China also moving lower overnight, and that's kind of crept over and and spilled into some negative sentiment for the European market open this morning. So looking in the center left, the DAX seen negative this morning, a little bit of support found through the initial opening volatility at the S2 level. The Euro Stoxx also slightly— well, not as bad a performance as the DAX, but again, low on the session. This follows some slight losses seen in the US index futures. As a net result then, T-notes seen up but still hugging around pivot about 2 ticks, Bunds sub-pivot up about 4, gold pretty flat. In the major currency pairs, the dollar index is essentially unchanged, and that is largely reflected in the major currency pairs as well. EURUSD absolutely flat at the moment, and cable sub the pivot level, which has provided a degree of of resistance thus far, up around 17. We'll have a look, a couple of Brexit-related headlines as well from the weekend's press. So straight into the headlines then. China-US tariff talks at risk after Trump's latest threats, according to Wall Street Journal. This comes after reports have been in circulation that the US is poised to trigger tariffs on $200 billion of goods. So this is kind of renewed threats on what otherwise was Trump intonating he was welcoming China back for trade talks. Obviously, he tweeted on Friday and pretty much dismissed that, and we're back full circle to where we were in the first place, which is the kind of threat of escalation, which translates into a negative in terms of intraday market sentiment. One thing to be aware of here is obviously China's potential retaliation. They've already really communicated that everything is in place. And should the US pull the trigger on this, which we're expecting if it is to come either today or tomorrow, then they already have listed all the different US products which they're going to also be targeting. So again, at the moment, China not being the aggressor but retaliating in kind for the type of measures, or at least levels, of which the US are looking to implement. Is this going to go away anytime soon? Probably not. I mean, if you just— I was just looking at Trump's Twitter account this morning to see just what kind of things that he's been tweeting, and it's absolutely the kind of the staging ahead of the midterms, which obviously is only in a couple of weeks' time. So the types of tweets that he's doing: 'Best economic numbers in decades. If the Democrats take control, kiss your newfound wealth goodbye,' followed by 'Consumer sentiment hits its its highest level in 17 years this year. Sentiment fell 11% in 2015, an Obama year, and rose 16% since the election. So it's #TrumpTime, as issued by the man himself, no less. The point being here is that Trump is right. The economy, by the economic data points, has been responding. Confidence is high. Talked about this last week. The economy is growing. Inflation, if it is to be a continual pattern, if inflation does back off as per what we saw in the CPI data last week, then ultimately this restricts the Fed from tightening too quickly and ultimately adds another potential upside catalyst to US equities. And when we start looking at the US equity market, I mean, we are right close proximity to the all-time highs. I mean, this is the S&P 500. You know, this was the, the big shakeout that we had on that inflation scare in February when we had that pop in wage data and everyone thought, wow, we're going to see real aggressive policy tightening, not just the Fed but synchronized globally. That's completely kind of fallen away at this point. And then if we look to where we are at the moment, we are right within a whisker, sitting at around the 2900, only about 20 points shy of that record territory. A little bit different setup for the Dow. We've got a little bit further to go until we get up to the same kind of conversation of record all-time highs. The Nasdaq as well is still off a tiny bit, but it's the benchmark that people refer to, and certainly Trump will be, will be talking about. I've got little doubt in my mind that at some point, whether this week or in the next weeks to come, that we're going to get up for a retest at that point. Just given how things are playing out at the moment. Um, quick look at some of the other charts then of significance, and this is kind of just again reinforcing this idea that the US is outperforming. I mean, you can just imagine, and what already is the case, for the political argument where America is really outperforming against the MSCI Emerging Markets Index, which which is this kind of purple line, the divergence which has really opened up over the last couple of months as Trump's really ramped up this trade war, has in some respects at least to bring back home to Middle America, is playing in the US's hands. And you can see here in terms of the Euro Stoxx Europe 600 price index, pretty much sideways, if not slight negative, because Europe obviously has its own difficulties at the moment in regards to what is predominantly a political situation, whether it be Brexit and the risk for the EU, or whether it be German migration issues and potentially runs on the coalition of Germany, all the way through to obviously the Italian situation that we've had and the knock-on effects for potentially Spanish banks on the fallout from the Turkish crisis. So Europe too has, has seen some, some weakness, and it only goes to fuel further the kind of standout nature of the performance at the moment economically for the Americans. One quite interesting statistic and something to be aware of is that the Shanghai Composite actually printed its lowest level last night since 2014, this being a technical point of support we've been aware of for some time, and given the nature of the index has just been creeping ever lower, it almost was inevitable. But the— from a technical point of view, what can be quite interesting here is if we breach this level— now it's gone through it— then, you know, do we run lower down to kind of 2500 direction? Would be— would certainly spark potentially more further episodes of selling of EMs. Across the board. And so certainly needs to be watched at this point. The knock-on ramifications, of course, for any concerns in China is in the metals market. And again, we're seeing this, and not too much of a surprise because those industrial-related metals have been tumbling. Just looking at the recent sessions here, nickel down 3%, copper down 1.5%, aluminium down 1.2%. In Shanghai, contracts were mostly lower, with zinc down close to 2% as well. So, you know, if you remember, if any of the guys recently who went through my commodities lecture, obviously China is absolutely pivotal on the demand side for a majority of these industrial metals. They probably make up about 50% of that equation. So an economic slowdown or a hard landing and collapse of their economy could be absolutely devastating for demand of these these particular products. Read across then, if these were to continue— not that I would say it's a clear defined opportunity this morning— is you just got to keep an eye on things like copper. It's often a traded asset then with a read across into the likes of the Australian dollar. So worth keeping an eye on that as well going forward. Okay, Brexit. Latest things that we've had, uh, nothing too groundbreaking. Again, there's a big political obviously event happening, first of which that kicks off for the Labour Party on Sunday this week, and it's going to be closely followed there in the week after by the Conservative Party conference going into the beginning of October. So you can expect the Brexit headlines to start heating up again. Boris Johnson, usual Telegraph piece condemning kind of Theresa May and this Chequers plan. Michael Gove and Liam Fox though being a little bit more supportive of the PM, still fighting her corner, at least for the time being. But this is the type of headline that we're reading this morning: May bracing for key Brexit talks as Johnson fires latest warning. The main thing here is that there's key meetings happening I think on Wednesday, and also happening from the European side on Tuesday, where they are going to be discussing Brexit in quite a lot of detail, and it involves all EU 27 members. Now, there was quite an interesting report in the FT at the weekend. This is what this kind of subheading says: the EU may let UK check goods crossing Irish Sea to Belfast. So the big obvious sticking point to progressing talks at the moment has been that of the Northern Ireland issue. And the FT reported on Sunday that the EU was considering allowing British officials rather than the bloc's inspectors to check goods heading to Northern Ireland from mainland Britain to help de-dramatize the broad— the border issue. Checks could also be handed away from the border using trusted trader schemes, according to the report. And according to EU diplomats, British negotiators have hinted they'd be ready to make concessions once May has navigated a crucial speech at the Tory annual party conference in October. So I think, you know, the EU diplomats are fully aware that Theresa May's got to toe the kind of Brexit line for the moment in order to keep her party together, to get through then any rebellion led by the ERG and Boris Johnson. If they give her some breathing room and make some positive noises, as they have done in recent weeks, This then helps keep her in power, and they would much rather negotiate with Theresa May than they would with a more hard-minded Brexit government. And so I do think you're likely to hear some more conciliatory tones from Europe to help assist her to keep her leadership through this quite tough period of the Tory Party conference. Then, on the, on the balance of her giving them some concessions in these talks, with chiefly the Northern Line issue being the key one. So at the moment, although you might get these kind of quite critical headlines on Theresa May, I do think though from the most important thing, which is who is running the UK government at the moment and Europe, I think the threats of downside price action may be lesser. And actually, if you look at the, the CFTC's latest data of market positioning speculative future contracts, then actually the market was heavily short sterling. And that has been moving subtly but significant in a sense, in that people are, are moving out of being so overtly short the pound. So as we're getting some more of these kind of comments, and which has led to the pound clawing back of the weakness that we're seeing in mid-August. I think we could see some more upside here. We do have obviously some key data coming out this week in the likes of CPI. We'll have a look at in a moment, but I guess first test is can we get back up to that, that high we printed really just last week at 131.57? And I think we can. Obviously the CPI will be critical whether or not that will materialize, of course. One person you probably read this morning, certainly if you're a Londoner, Sadiq Khan calls for a second Brexit vote. Again, this is all very much just politics at play because coming ahead of the Labour conference, there's obviously been Jeremy Corbyn in it himself in the Labour Party has caused quite a lot of division in regards to what should happen next and this this opposite call for a people's vote on a final deal and the Mayor putting his weight behind that group. I can imagine, I can only imagine what the people outside of London must think of Mr. Khan this morning. I'm sure they're not particularly happy. But another senior person within the Labour Party kind of following suit. And so it's quite interesting, actually. I think for me, the Labour conference has been a little bit underplayed. I think it could be quite interesting, actually, and scientists should be aware of. But unsurprisingly, once again, you're going to hear lots of these types of political-related headlines as we go through this week. Looking at the calendar for today, the session is relatively quiet as per normal case for a Monday. And so main thing to have a lookout for, we've got HICP for August, but these are final readings, so I wouldn't be looking for too much out of this data at 10 o'clock. And in fact, there's really not a lot on the calendar at all from a scheduled basis. What I'd definitely be focusing my trading strategies around would probably be about sentiment and digestion of the latest pressure in the EMs again, which has been created by this renewed fallout from Trump being quite, quite confrontational on the trade talks with China. If the US want to take that as then an escalation, then you could see some more negative time of flight to quality price action materialize. In that case, you'd be looking for I guess some strength in the US 10-year, gold, and then equity markets maybe under a little bit of pressure. But let's see, I'd have to really— would want to— I think if I was allocating attention on the intraday, I'd be looking towards the US session to really get a better sense of where this market could go today, because I think overall we're pretty flat this morning, and I think other participants are kind of in a similar mindset. Looking at the week in its entirety though, a couple of interesting things that are happening. Haven't really talked about Turkey, didn't really read much about Turkey at all over the weekend, but Russian President Putin is meeting Erdoğan today in Russia. And so just given the nature of the foreign policies at the moment, it's probably worth just keeping an ear out for any interesting commentary. Otherwise, there's we're going towards Tuesday, uh, you do have ECB's Draghi, and he is speaking on Tuesday and Wednesday. Um, not expecting much from Draghi at all actually this week. We had the ECB obviously, uh, last week, and I think we are pretty clear on what the, the party line is from the, the ECB, what's going to happen and when. I think there's sufficient clarity and transparency in that regard. So, uh, of course I'd always keep an ear open when Draghi is speaking, but I'm not expecting any fireworks. Uh, Wednesday you've got the Bank of Japan interest rate decision. Uh, I'm not really looking for, for much from there, but as per usual, any tweaks to specific wording around their, their parameters of the QE program could be quite interesting. Uh, otherwise attention will turn to the UK inflationary situation because we get UK CPI. What does UK CPI look like? Well, This is the, the, well, this is the US reading. Let me just bring up the, the UK CPI last print that we had. It's here. We had obviously quite a big drop-off, and it's been relatively benign from what was only several months ago was a slight panic about this, you know, heightened inflation disparity against wages. But what we've had is a little bit of a convergence between those two indicators. And so UK inflation, I would, I would suggest, is probably going to remain static at around these levels. Of course, a lack of demand, just given the political uncertainties weighing on consumer confidence, could be quite interesting to see how that, that plays out. So that's on Wednesday. You've also got Bank of England's Haldane, who's the chief economist, is also going to speak be, be speaking. On Thursday, you've got the Swiss Central Bank decision. You've also got UK retail sales. So really, from data points in the UK, not only on Wednesday you're looking out for those, those Brexit talks, any comments that might materialize from those discussions, you've also got CPI and retail sales. And then one thing here that could be interesting for the EMs— Turkey are set to unveil their medium-term economic plan. On Thursday. And of course, the markets have been quite sensitive. If you remember when the Turkish central bank really got the bazooka out last week and aggressively hiked interest rates, actually momentarily European assets also rallied in a slight relief that they were taking very strong action to counteract the likes of surging inflation. That didn't last long, but nonetheless, it just goes to show overall broader market sensitivity sensitivity to Turkey and the EMs. And then on Friday, to wrap things up, we get the, the flash manufacturing service PMIs coming out of Europe and also from Japan and the US as well. So that's a week in it as a whole. I would say quite a few interesting data points specifically on the schedule, but more broadly it's going to be Still the regular themes of the US-China trade talks. The Shanghai Composite closed this morning at the lowest level since 2014. Any Brexit political commentary, but I do feel like we're getting a little bit of news fatigue on that issue. And the most important two players, that being Theresa May's government and Michel Barnier on behalf of Europe, I think will continue to press a more conciliatory tone, which could add at least some political stability. And if we get not a dramatic fall in retail sales, which some might be looking for, and CPI remains relatively level, then potentially some further upside could be on the cards for sterling as the week plays out. Okay, gonna leave it at that, let you guys get on. Uh, Sam is around, so I will ask him to go through some charts technically and to post them into the chat room. He's also going to be writing the, the weekly strategy report where he'll go over some long-term levels of significance as well. Okay, have a good day and a good week, and I'll catch you later on. Thank you very much.
More from Anthony


Inside the Biggest Banking Stories You Need to Know This Week (Anthropic, Diageo, Private Credit)


Inside the Biggest M&A Deals You Need to Know This Week (UniCredit, GameStop, eBay, Eli Lilly)







AI Breakthrough or Hype? Anthropic’s Claude Mythos, Tim Cook Steps Down & LIV Golf Collapse