Morning Briefing - 23rd July 2018
The presenter delivers a concise morning market briefing for the Trading Live audience, beginning with a personal congratulation to Amplify Trading director Anthony Cheung on becoming a father. The core of the briefing reviews recent FX movements—dollar weakness, pound and euro gains, yen strengthening—driven largely by Donald Trump’s comments on the dollar and emerging geopolitical tension between the U.S. and Iran. The speaker highlights the Bank of Japan’s rare policy‑change discussion, suggesting a bias toward yen strength, and previews the ECB’s upcoming meeting, expecting a balanced “Goldilocks” tone from Mario Draghi. Upcoming U.S. drivers are outlined: a busy earnings week, key macro data (existing home sales, GDP) and a SOMA/SUMO day that could tighten liquidity and lift the dollar. Brexit news is noted as relatively muted. The presenter advises traders to treat the day as quiet, stay patient, and avoid aggressive positioning until clearer catalysts emerge later in the week.
Chapters
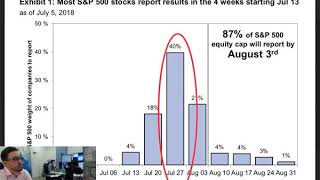
Good morning, it is Monday, 23rd of July, just gone half past 8. Start with some very positive news. Director here at Amplify Trading, Anthony Cheung, is now a father as of Friday about 3 PM. So congratulations from everyone here to you, Anthony. As I'm sure you were listening on Thursday and Friday, I'm sure you are up at the crack of dawn eagerly anticipating this briefing as well. So congratulations, I'm sure you're going to be absolutely fantastic, um, and I'm sure everyone in Trading Live will say congratulations as well. We'll start going over, uh, the stories from over the weekend, what could drive the markets today and this week. Um, might be worth noting that probably this morning and the rest of the day is going to be a relatively quiet one. The data calendar, uh, very quiet. It's not really until the, the latter part of the week that it gets perhaps a bit more exciting. However, that was the case on, on Friday where it was expected to be a relatively quiet day, and then the man that we'll talk about in a bit more detail today opened his mouth again and the market has actually started to move. In a summary of, uh, last week, if we just have a quick look over, uh, at some of the markets here. You've got— let me just move this into picture so the camera's not in the way. You've got the, uh, the pound here. So we had some relatively weak data throughout the week from, uh, from the UK. Retail sales, uh, numbers, um, on a couple of the days were worse than expected. Uh, and here you can see just consistently around 9:30 the, the pound was, was dropping against most pairs, including the dollar that we've got on here. And then we came into sort of Thursday around 6 o'clock, we had the comments from Donald Trump, which we'll sort of go over again, stating that the dollar was too strong at this sort of time period. And since then, the pound has pushed higher, really going from, you know, 130 up to almost 132 this morning. So the dollar continuing to weak, the dollar index. We talked about the 95 handle quite a lot during the briefings last week and throughout the day, that we've retreated from there now down to 94. Just a bit above 94.09 of current trade. Euro, similar picture from those comments on the Thursday evening. We continue to push higher, almost to the high that we made on the 17th, touching that and almost breaking through 1.18 handle in the futures as well. S&P slightly more range-bound last week. The, the stronger or you know, weaker dollar comments, if you like, not really having an influence on the S&P as such. But today and for the remainder of the week, you know, quite a few— well, not necessarily today, but for this week in general, quite a few earnings coming out. So for the S&P and US equities in general, worth just keeping an eye on, on the latter part of the week when it's going to be slightly more busy. Gold on that weaker Um, dollar from Thursday, you can see, pushed higher. However, just finding a bit of resistance, uh, around sort of 1235 in the futures. Quite a key sort of area, which, which was the, the sort of the lows that we made on the 13th before breaking down, um, on Tuesday last week. And that's sort of acting as a ceiling now. So one to bear in mind for gold there, finally having a bit of a correlation with something— the weaker dollar from Thursday helped, helped push, uh, this market just a bit higher. Um, worth having a look at the, the sort of the timeline of, uh, of Donald Trump and his comments on the, on the US dollar. You see, when he came into office, it was, uh, you know, nicely above 100, uh, 97.86 on the election. So when he came into office, uh, in, in January, he started to talk it, uh, down, saying it was already too strong. And then we had obviously that it was too weak as well, as well. So comments contradictory to, you know, months gone by. But now, yeah, around 95, Donald Trump saying that the, the US dollar is, is too strong. So going through the week, and I was saying to the guys in-house, I think if we're getting consistently more of this kind of chat then we could start to see a shorter-term turn into a more medium-term trade of sort of selling the dollar, if you like. So one to keep an ear out with your sort of your Twitters and obviously on the squawk as well, any comments regarding the strength of the dollar just to bear in mind. Mnuchin over the weekend did try to talk down Donald Trump's comments, but this morning we've already seen a bit of dollar weakness with, like I said, the dollar index just down a touch this morning as well. Going over to sort of the weekend news, and I'm sure some of you would have seen this coming in, it all got quite heated between Donald Trump— shock, horror— and Iran. So this tweet here this morning, or sort of late last night I should say, to Iranian President Rouhani: never ever threaten the United States again or you will suffer great consequences the likes of which few throughout history have ever suffered before. I mean, that is, you know, it's pretty, pretty deep. We are no longer a country that will stand for your demented words of violence and death. Be cautious. So, you know, those geopolitical, uh, sort of risks coming back into the market. If we have a look at, uh, you know, gold this morning hasn't really done too much, you know, although like we were saying last week, is it really a safe haven at the moment? Perhaps not. Um, oil, on that you would expect a bit of movement, but that's not really the case. Quite range-bound really since where we opened on, on Friday morning. Uh, kind of haven't moved. So for those, uh, those comments, you would expect to see a bit of movement, not to be the case, uh, for now. Other stories over the weekend, uh, if I'd switch quickly, switch over this, um sort of came into focus really sort of the back end of the session on, on Friday, uh, with comments from the, the Bank of Japan to debate policy change in July. So that meeting, uh, concluding on the 31st, so a 2-day meeting, 30th and 31st, so end of this month. Um, so it was quite unusual in the fact that it came out, uh, UK, uh, late in the day, but of course over in Japan that was more, uh, 11 PM midnight kind of time. So quite a, uh, an interesting stance to, to have it so late just before the weekend. But yes, going into this here to debate policy changes, and now this, you know, would be the first change to, uh, policy since 2016. You can see if I just put this on a 5-year, you know, the rate has changed completely the same, no real um, uh, sort of move from, from their part. So this has been perceived quite hawkish. We have a quick look over, um, at, uh, the dollar-yen. And of course it will be the same for many markets. Has come under pressure, uh, here. Obviously the yen strengthening, also you've got a bit of the dollar weakness as you can see from Thursday. If I had to circle the Trump comments here. And then you have the Bank of Japan comments, which have seen it come off those highs that it's been at for, for quite some time. Uh, the article I'll post in the chat, uh, as well. I think you would have been sent it in the, in the email this morning. Reuters, um, article exclusive, um, from, uh, last Friday, but getting a bit more sort of notice over the weekend as we've, we've gone through, uh, that there. So yeah, you can see first Bank of Japan policy tweaks since 2016. So, you know, sort of trying to develop the bias almost for, for the day ahead, I think you've got to go with looking for the yen strength ideally. You know, maybe when the market sort of picks up a bit, uh, I would also favor this market perhaps more than say the pound or the euro, just to do with the fact that you've got, you know, strength on one side and a bit of weakness on the other. So one to keep an eye on going forward, not just today but the, the week as well. Um, we have a look over the Nikkei, and this is just the, the CFD. If I just bring that into picture here, you can see really from those comments as well, and this morning we've, uh, continued to push lower. Uh, the trade war talks from last week, uh, didn't really, you know, amount to too much. As you can see here, S&P pretty sideways as of recent. The NASDAQ, you can see as well, I mean, just looking at the pivots there to give you an indication, it's been a topsy sort of turvy week. We did make a new all-time high and have drifted down since, but, uh, those trade war talks not having the biggest effect to the downside, uh, in what is going to be obviously a very data, um, uh, sorry, not earnings-driven week. Here you can see the charts, the week ending July the 27th. So most S&P 500 stocks will report results in the full week starting the 30th of July, 40% this week. So do expect some sort of movement from, from the, from the US equities as we go through the course of the week. So in response to obviously Donald Trump kicking off, Iran's Rouhani warns Trump about mother of all wars. So it's all getting a bit bit personal. Um, remains to be seen if it can have a sort of impact on, on the move of, of markets. At the moment it is rather, uh, limited, uh, as well. So keep an eye over the weekend as well. We've had a couple of, uh, Brexit-related stories. It's— I mean, to be honest, it's been a quiet morning, relatively sort of quiet weekend, other, you know, than this. It's me— really been a continuation from what we saw to the back end of the session. So yeah, Brexit-related stories, you know, it's more, you know, had Raab come out and say, you know, some relatively positive things that they're, you know, ready to, you know, they won't pay the bill if there's no, you know, sort of trade deal. So, you know, for now the market's not really interested. Going back to the pound here. You know, if anything, it's pushing higher, but more to do with the dollar. So Brexit-related stories, not too much going on. Uh, you know, in the Sunday Times there was an article saying a lot of the sort of, you know, Brexiteers, if you like, if there is no deal sort of reached, uh, you know, a lot of the supporters are going to go, you know, UKIP, far right. But, you know, in terms of market movement, those sort of stories not really going to do too much. I was having a look this morning about possible exit dates for Theresa May. I mean, she's come through a lot, so, you know, how much more can she take, or is this just gonna make her stronger? And stronger remains to be seen. So 2018 is obviously only got about, well, just under 4 months remaining, just over 4 months remaining, I should say, and favorite to sort of go this year before looking to go on. So obviously the next election scheduled is not until 2022 anyway. Whether there be one before or not, I think could perhaps seal her fate either way. Um, but yeah, remains to, to be seen there. Just having a quick look over the sort of the, the charts for now. Mention that the data calendar is, is relatively light today, so I'll bring that up in, in just a moment. Um, but you can see here the DAX, which opened a bit lower, has now sort of recovered to fill that gap. Oil, we mentioned, quite sideways. S&P likewise over the sort of the last few hours, having if anything, you know, opened, uh, lower in your sort of initial Asian session trading. The dollar still relatively weak, but in terms of actual movement, it's only up slightly, uh, in terms of the euro and the pound against that pair as well. Coming into the, the sort of the back end of the week, mentioned today is quiet. You do have the ECB meeting, um, on the 26th this Thursday. Obviously got the Fed and Bank of England next week, so that's something to sort of look out for. Deutsche Bank, if I just bring up a tweet, or I'll just, I'll just talk about it as I don't have the, the link up. The impression from recent press stories is that the ECB thinks the market is priced in its new policy stance too dovishly. We expect Mario Draghi to aim for a Goldilocks tone at the 26th of July press conference, so this Thursday, not too hawkish, not too dovish. So while, you know, perhaps not going to be the biggest meeting of the year, something to bear in mind on that Thursday morning going into the meeting could be relatively sort of range-bound, and if anything, maybe sort of a hawkish tone. But we are pushing higher of recent days, so remains to be seen how much of a reaction we can get from that. Also going through the week, you've got this a bit more US data to come out. You've got the big one on Friday, GDP. So in terms of data, what's really going to move or has potential to move the market the most, that would be this Friday as well. I'd be looking out, other than data, for, you know, any sort of more comments on the sort of, well, Trump on the strong dollar. Is he still trying to talk that down? If that's the case, you know, I can see this, uh, the sort of weakness continuing for a while. The 95 handle in the US dollar index has held for now, is quite good resistance. Got a lot of earnings coming out this week as well, uh, to be aware of, um, that could really sort of drive things going forward, uh, as well. Um, so if I just bring up the calendar Just give me one second. So yeah, here's the calendar for today. You know, you do well to, to sort of find, uh, less on an actual calendar than we have here. You have, uh, the only thing potentially data-wise that could move it, 3 o'clock, existing home sales. Although, you know, I'm not expecting to see too much, uh, from this. Speakers, so we've got Broadbent to be aware of, neutral, but a voter, just so, you know, something to just bear in mind when that could come out as well. Also, one thing of interest, if I just switch over to this here, yeah, so this Friday we have a SOMA day or SUMO day, System Open Market Accounts, or the Fed reducing their, their balance sheet. And it's just something to, to bear in mind. This picture here, as you can see, is relatively old, but it has the dates of, of these SUMO days or SOMA days. Um, and on days where there's sort of a large and negative impact on, on US liquidity, you, relatively speaking, you're going to get an increase in the dollar. So you can see here, just going back to sort of October last year, um, we started to see a bit of an increase, uh, in the dollar on, on average, and the liquidity obviously dropping quite a lot. So the next one of those comes this Friday, I believe. Um, so something to bear in mind going into that day, you may start to see a bit of, uh, of dollar strength into the afternoon in terms of sort of a short-term move. So setting up the, the sort of the week ahead, would expect very much that this one, uh, this morning and today is going to be a quiet one, uh, much more in terms of activity or potential activity to come through earnings, US data into the week with the big sort of GDP on the Friday. I'll be looking out as usual for sort of Brexit comments, although really over the last sort of 3 trading sessions there hasn't really really been too much going on there. Gold, which has been reduced in sort of correlations and safe haven status, has, has finally started to sort of move with the strength or weakness of the dollar. So for those, uh, looking more medium term, it's not, uh, well, it doesn't look too bad, uh, as a sort of a potential long continuing, uh, the recent trend of the last couple of days perhaps. Um, but gold, yep, coming to those sort of multi-month lows. If I just bring gold in to the picture, which hasn't really been a hedge against inflation, hasn't really been a safe haven, continued to go lower here. So if we do start to see, um, you know, this weaker dollar, it might well be that we can get a push through the sort of December low, which you can see off there's really good support. And I think if we can close above that 1236 futures level, the only way is up for a while. And then, you know, sort of targeting above 1250, 1267 on the futures, uh, wouldn't seem perhaps too far away. Um, going into sort of the rest of the day here, I'll get the, the strategy report sent out as soon as possible. Any questions on the charts, please do let me know. But just a word of warning, I would expect it to be relatively quiet, so not Being too aggressive on a day like today or being super patient waiting for any sort of comments to come out, I think would be, would be wise to do. If I don't speak to you in the chat, I hope you all have a good day and a good trading week.
More from Anthony


Inside the Biggest Banking Stories You Need to Know This Week (Anthropic, Diageo, Private Credit)


Inside the Biggest M&A Deals You Need to Know This Week (UniCredit, GameStop, eBay, Eli Lilly)







AI Breakthrough or Hype? Anthropic’s Claude Mythos, Tim Cook Steps Down & LIV Golf Collapse