Oil Advances Most In A Month On Expectations Of Supply Decline
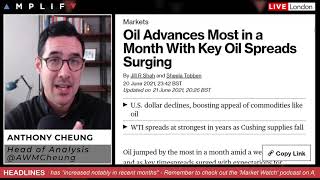
In this market briefing, the host provides a comprehensive update on U.S. equity markets, energy sector performance, and oil price dynamics following recent Federal Reserve hawkish commentary. The S&P 500, Dow, and Russell 2000 rallied strongly, led by energy, financial, and industrial stocks, erasing prior losses. WTI crude broke out to around $73.5, with technical targets near $75.3 and $76.9, driven by backwardation, a 2.6 million‑barrel drop in Cushing inventories (Genscape), and expectations of tighter U.S. supply as the economy reopens. The host analyzes Fed communications—Powell’s prepared testimony, New York Fed President Williams, and regional presidents Bullard, Kaplan, and Dallas Fed—highlighting a hawk‑dove split and its limited immediate market impact. Currency moves are reviewed: the dollar index recovered to the 92 level, affecting EUR/USD and GBP/USD ranges, while gold shows a bearish channel with key support near $1,773.5. Geopolitical headlines include North Korea’s diplomatic stance, ongoing Iran nuclear negotiations, and a forthcoming strategic stability dialogue with Russia, all deemed unlikely to move markets today. The briefing concludes with a concise economic calendar covering U.S. existing home sales, Eurozone consumer confidence, API inventories, and speeches by ECB and Fed officials, plus Powell’s congressional testimony and a $60 billion note auction.
Chapters
Very good morning, it is Tuesday, 22nd of June. Hope you're doing well as ever. If you are watching this delayed on YouTube, then don't forget to like and subscribe to the channel. If you want to get this briefing early, don't forget to check out amplifierlive.com. But getting straight into it and looking at the heat map on the close on the S&P 500 yesterday, really strong rally in fact that we saw across the major indices, eradicating pretty much all of the losses that seen following the hawkish tilt from the Fed last Wednesday and the follow-up hawkish comments from Bullard that dented equity sentiment on Friday. So the S&P was up around 1.4%, the Dow actually outperforming, helped by the fact that energy, financial, industrial shares really led the comeback. The Dow up 1.76%, the NASDAQ was up just 0.6%. Commodity stocks that were hit hard last week, we're really seeing the best of those gains, and the small-cap Russell 2000 in fact outperformed all of them and was up up just over 2%. One of the major areas here, kind of sweet spots, so to speak, is the energy sector. You can see here glowing the most green. So you can see the likes of Exxon were up 3.6% at the close last night. Chevron, CVX, was also up around a similar margin. And so let's take a look at oil prices. And those continue to move higher. So here on the intraday view, you can see we had a bit of a breakout. And a nice platform for price on the pullback. It came back to that same level of what was the high point of resistance, uh, back on Thursday of last week, initially in the APAC session last night, Sunday going into Monday. And then we just managed to continue to move higher here and now at the high, finding a bit of resistance up at $73.28 for the moment. But if you look at this on a daily chart, you can just see where we're at on the bigger picture now with oil and continuing to just move up at the moment. And from a technical perspective, you've got that high, the top from summer of 2018, as the next kind of target here. We're trading at $73.56 at the moment, that would be up at $75.28. And then the overall larger upside target, the October '18 high, would come in at $76.90. But oil then, really quite a focal point at the moment in terms of advancing the most in a month on a couple of different things. A few people are looking at some of the recent dollar weakness that we saw, particularly going back to yesterday's session, albeit I must say that the Dixie is just actually firming up, reversing some of those moves for the moment. So worth keeping that in mind. But the other thing is key time spreads surged. Now what we're looking at here is a case of backwardation, meaning that the near-term contracts are more expensive than further out in the future. But why this is happening is expectations of further supply declines at the biggest storage hub in the US. And so data provider Genscape— so if you're an oil trader, there's kind of 3 major phases of information you get on a normal weekly basis: Genscape on Monday, APIs on a Tuesday, and then you get the DOE on a Wednesday. And Genscape reported a 2.6 million barrel drop in stockpiles at Cushing in Oklahoma last week, according to people with knowledge of the reports. And inventories at the hub already at the lowest since March of 2020. So a tightening market. And remember, the US is in full reopening mode at the moment. Remember, just last week we saw the likes of those highly populous areas like California, New York kind of taking the lockdown shackles off and completely now reopening fully. Given that over 70% of the people in those areas have now been vaccinated. And so, yeah, continues to, to, to play out in a very positive fashion for, for oil prices. And of course, all of this coming in context of OPEC not budging at the moment and continuing to lend its supporting hand from a supply pact point of view. So yeah, definitely WTI spreads at their strongest in years now as Cushing supplies continue to fall. Some of the dollar fluctuation as well, particularly downside coming yesterday, just helping propel prices higher once again. So helping that energy sector in the S&P. But having a look then at the equity market, one of the things here that was quite evident— I've marked this up just to give you a visual cue of where, what we're looking at. And here we are. I mean, these ellipses here mark where we were trading before the FOMC announcement on Wednesday. And this is where we're trading right now. And despite the excursion to the downside that we have on the double whammy of the hawkish 2 hike 2023 dot plot and then Bullard's follow-up on Friday, Monday's rally was pretty extreme. In fact, one of the best single-day rallies you've had in a couple of months, and it's taken us all the way back to basically flat. And, you know, actually, when you look at this, the all-time high is here, only around 30 points above where we're trading at the moment. So, you know, despite people getting a little bit spooked about the hawkish tilt that we've heard from the Fed, you know, equity markets still remain pretty robust at the moment. And a lot of that does come on the back of more comments from the Fed. We, we knew that Fed commentary— I mean, there's a lot of speakers this week, and that's quite typical of a communication tactic from the central bank to try and kind of just steady the ship after we saw quite an extreme reaction last week. And we've got a bit of a fight breaking out here between the hawks and the doves at the moment, because the text for the testimony to US Congress about COVID-19 response— that's happening today in terms of Powell speaking live, but the prepared text came out last night by the major newswires. This is quite common. I was at my desk maybe half 9, 10 last night when the, when the news came out. And basically there's nothing too substantial that I'd say that Powell has said, but just to go over some of the main stuff, he said the US economy continues to show sustained improvement from the impact of the coronavirus pandemic and ongoing job market gains, but inflation has increased notably in recent months. And he continued to talk about the fact that he sees that dropping off and reinforcing that transitory view. Separately though, on the back of this, the New York Fed President, um, Williams came out— this is an FT piece last night as well— and said that the US economy does not justify a policy shift. So for me, putting these two comments together, and given the fact that these two are two of the most senior, most important people on the FOMC, both Powell's prepared testimony, Williams' remarks suggest the top, top brass, if you like, at the Fed are definitely much more cautious on the prospect of quick policy changes compared to those of what we've heard from more regional level presidents like Bullard and also like Kaplan. So the Dallas Fed president spoke yesterday. He's a well-known, probably the most outlying hawk anyway, did say favored starting the process of reducing bond purchases sooner rather than later. But again, given his stance generally on policy, that doesn't come as a surprise. But I think tactically this is all part of the plan for the Fed, is the way I see it. You've kind of got these outlying hawks sounding hawkish, and, and rightly so, because there are elements in the economy that would justify that. And, you know, I was just having a look at the Bloomberg High Frequency Index in combination with the Atlanta Fed GDP tracker. And although we're going to see Q1 GDP final reading this week, I mean, who really cares about that? That's old news now. Looking at what those trackers are saying for Q2 GDP in the US, it's going to be in excess of 10%, you know. So there's, there's these kind of reopening pains to go through which are going to cause pretty explosive growth in the short term at least before we average out. And so yes, some of the hawks are being hawkish and the center ground is being held. So for me, this is kind of— we're just leaning in that direction, which I think is probably appropriate. But at the moment, the market's taking a degree of assurance and relative calm, having reversed a lot of these moves on the fact that, look, the status quo at the moment is inflation is transitory and we're not going to move anything very quickly. But, you know, the seed has been planted now, and I think the hawks are doing that purposefully because change will happen in time. And we still stick to the timeline of a more in-depth kind of discussion on tapering to emerge come then the signals in Jackson Hole to be formalized in September for the whole tightening process or reduction of bond buying to commence the beginning of next year. So yeah, a couple of things there. But just, just flicking back to the charts for a moment before we look at some of the other geopolitical news that I think is worth touching upon. So quick look at the currency pairs. The dollar index right now as I'm talking is now up about 0.2%. So in fact it's pretty much reversed the Dixie, the losses that were seen during the US entrance yesterday. So we're back to pretty much flat in that move now, trading at around just around the 92 handle. So as such then, that's just providing a bit of a cap for EURUSD in the near term. You can see here, so still upside, keeping an eye for a firm level of resistance at 1.1943.5. Any further pullback here— we are trading sub-pivot in the euro future at the moment— be keeping our 1.1904.5 and then down to that double bottom that was printed Friday, Monday at 1.1867. So at the moment you could argue this is a range and we're kind of midpoint of that at this present point in time. The dollar strength just helping on that recovery in the DXY. Euro-dollar just, just grind back down for the moment. As far as cable is concerned, quite a nice technical response that we saw on the daily chart yesterday. So again, pretty reminiscent of the euro in reflection of some of the dollar recovery that we've been seeing the last couple of hours during the Asia-Pac session. On the daily chart though, nice bounce off that previous low that we had at the end of April. Which is around the 1.38 psychological handle as well as that technical support area. And you can see 1.38 has been an inflection point for price on a number of occasions through 2021, so it's a meaningful level. And we saw quite a decent bounce off that for the time being. But again, short to term, um, I'd be keeping an eye on the dollar for the moment with a lack of real sterling catalysts. Meanwhile, elsewhere, just a quick look at gold. I've just been having a look at this price pattern here in gold that I've been looking at, um, which is this on, on the downside. This trend line has held so far, nice test and, and support being found at around that level. And so we're in close proximity to the lower bound of this kind of channel for the moment. So I'm quite keen to watch that. Got the pivot just below, but we didn't really see too much support on any breakdown in price until we get further down to this level from the Monday morning low and the Monday kind of US morning low, which would be around the 1773.5 level in the futures if we break the, the recent pattern here in the pivot level. Otherwise, on the reverse near term, we've got to get back up and through this kind of range here. You can see these areas of support that have played out quite nicely through Monday and also in the Asia-Pac session to then kind of print that, that upside of that channel, which has been that rising trend line going back from last Thursday, the test on Monday, and in the overnight sessions. That's kind of the setup I'm looking at in gold at the moment. In terms of the driving forces as to what could be the trigger points there, again, dollar fluctuation and movement is going to be quite, quite key. On a geopolitical front, it's kind of the three 3 forces at the moment. So you've got North Korea, Russia, and Iran. These are the kind of main talking points when it comes to the US, um, at present. And starting off with— this is Kim Jong-un's sister, of course, and she's come out and dismissed the prospects of an early resumption of diplomacy with the US, basically just saying that their expectations and ambitions are misaligned, essentially. I won't comment as yet as to what I think of that until I run through all three, and then I'll give you the summary. Um, elsewhere, the White House has said it has no timeline on reaching agreement on the Iran nuclear deal, and it will continue to negotiate. That's of course coming off those Iranian elections we talked about yesterday. And then the US State Department says it is preparing strategic stability dialogue with Russia, and it is in the process of scheduling those conversations at the moment. So on all three fronts, not really a great deal surprising. I think it's way too early yet to be brought back to the table after current, uh, journey of those meetings after several rounds with Iran. I think that's still got some way to go before we get to anything more of a definitive agreement. As far as Kim Jong-un's sister is concerned, that's probably the least surprising of the three. They're just keeping a fairly firm hand at the moment, and I don't really think Biden's got too much appetite to reengage with North Korea at this point when he still has to really deal with, with China first, then Iran kind of second on the geopolitical matters, and then probably Russia third. So North Korea is kind of there and present, but also tends to be almost a proxy for US-China talks more than directly specifically about North Korea. So perhaps this is just part of that, that usual political play from, from China at the moment. And then, yeah, the Russia side, following those meetings from Biden and Putin last week, this is probably what you would expect. So fairly lukewarm, but warm to a certain degree. And so it's just about when they're going to talk again. So for all three of these, I don't see any impact for the, for the market open today, but probably prudent to update you on those matters. As far as the calendar is concerned, it's, it's pretty quiet. In fact, for today, there's really nothing at all coming out in the UK European morning from a data perspective. Therefore, leading on into the afternoon, we get the US existing home sales report and the eurozone consumer confidence flash reading for June. And API inventories come later on in the evening as per usual. From a speaker's perspective, um, chief economist at the ECB, Philip Lane, talks about the resilience of the euro at 3 o'clock. There will be a text release and Q&A. Fed's Mester, a voter next year, will be speaking on monetary policy. At 3:30. Fed's Daly, who's a current voter, she'll be speaking at 4 PM, and ECB Schnabel will be speaking at 6:30. And again, as far as, um, Jay Powell's testimony to US Congress on the COVID-19 response, that does happen at 7 PM London time formally. But again, we've already had the text out last night, so not expecting that to be a market-moving event. And then you've got $60 billion coming into, you know, note auction, just to wrap it up for any of you fixed income traders. So that is it. Not gonna go any further, gonna leave it there. Any questions at all, feel free to reach me in the Amplify Live community or on YouTube. Just drop a comment, happy to help. But otherwise, have a good day ahead. Thanks, guys.
More from Anthony


Inside the Biggest Banking Stories You Need to Know This Week (Anthropic, Diageo, Private Credit)


Inside the Biggest M&A Deals You Need to Know This Week (UniCredit, GameStop, eBay, Eli Lilly)







AI Breakthrough or Hype? Anthropic’s Claude Mythos, Tim Cook Steps Down & LIV Golf Collapse