S&P 500 Puts In Its Second-Best Start Of A Year Since 1998
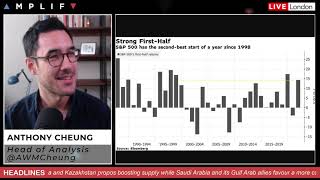
The S&P 500 gained 14% in the first half of 2021, its second-best start since 1998, with mega-cap tech like Google (+40%) and Microsoft (+21%) leading. The dollar posted its strongest month since June 2020 on hawkish Fed signals, while oil rallied 50% from sub-$50 levels as US stockpiles fell at the fastest rate since 1982.
Chapters
All right, very good morning to you and welcome to the second half of 2021. Can't believe it's flown by this quickly, but as usual then, we'll have a bit of a quick review of how the first 6 months have gone. And despite a lot of the tension more recently about this idea of what more sticky inflation could mean, the Delta variant and the new spread that we're seeing that could jeopardize global economic recovery. The S&P 500 has actually put in its second best start of the year since 1998. Uh, and a few other stats: the gauge now has notched its longest streak of quarterly gains since 2017, having rallied already some 14% this year. So as you can see here, now off to a really strong start, um, and Looking at one of the other things here is the overall year-to-date performance of some of the individual sectors that we've seen and looking at individual companies. And you can see, despite a bit of an idea of earlier in the year, a rotation out of some of these growth big mega-cap tech names and into other value areas, in fact, yes, everything has gone up, but growth, the show's not over just yet. And so even though they're talking about rate rises, again, don't forget they're talking about another 2 years out on the time horizon. And so the likes of Google, you know, I just said the S&P was up on the year 14%. Google's up 40% on the year to date. Microsoft up 21%. Facebook is tracking up about 27%. There's some really sharp gains, but the fact that the rates market is anticipating to increase over time when yields are moving higher. You know, a lot of those banks have also seen some really sharp moves. Wells Fargo up around 50%, um, Bank of America up around 36%. And in the capital market space, some of those big banks as well— GS up 43%, MS up 34%. So all in all, the gravy train continues for the time being, um, and Yeah, and looking at the, the performance from what we had yesterday, there's a couple of individual sweet spots. Talking of Wednesday's session, you can see here Walmart just glowing green. They finished today up about 2.7%. That came after they reported they would start selling prescription-only insulin analog. And there's some other hotspots. GE, they got added to Goldman's top idea on their stock pick list. they were up about 3%. Uh, Boeing as well, which is a fairly sizable firm, also saw some pretty decent gains yesterday after a German defense ministry announced a military, um, or maritime control aircraft order. And that came after United Airlines unveiled its largest ever order for new planes as well from the firm. So a couple of things there just helping as well, um, because if you actually look at where we closed yesterday, you know, we're still right up there, the S&P 500 of course, has traded at record all-time highs again, um, as far as the overnight session is concerned. And I was talking to this, or about this move yesterday, to a couple of the traders, and we were looking at that, that kind of trend channel that we were observing in yesterday's briefing, and the fact that that was that horizontal key line, the daily pivot yesterday. And for me, that breakdown was purely technical, and we were talking about it when we were down and around the S1 as you know, this, this is often the mechanics of how markets work. It doesn't always need to be a news catalyst for sure, and a technical breach of levels can add then to whether you're trading the kind of breakout or momentum strategy. And then fundamentally though, very unlikely, we were saying at the time, that that move would be sustained given the fact that there isn't any real new fundamental rationale to keep price suppressed, to keep moving lower. And when we're trading up at all-time high levels, it's not uncommon to see a little bit of profit taking as well. So with the technical trigger for the downside, I think a lot of people just use that as an opportunity to re-enter short-term to push us back up to all-time highs again, of which obviously we busted through in late— in the Wall Street close. And then that's acted now as a bit of a platform for price to continue to push on up during the APAC session. And so For now, just keeping an eye on these prices at these most elevated levels once again. A couple of bigger things as well coming out. We'll look at the calendar for the day ahead in a moment, but of course non-farm payrolls as well looming on Friday. In the FX market, while I'm on the, um, when I'm on the charts, in terms of the 6-month performance from the beginning of this year, the dollar has been seeing a really good performance of late within that period. And in fact, the dollar had its best month in June since March of 2020. And you remember March 2020, after some initial volatility, that was when the dollar really rallied on the back of the notion of it being the global reserve currency when we went through the worst part of the equity sell-off when we had the onset of the global pandemic. So that was the last time when the dollar put in a type of performance that it's seen since June. And just having a look at the EURUSD currency pair here on a daily chart, you can really see how the narrative has changed. And you'll remember, this here is June 16th, was the initiation of this first candlestick here. And you guys remember what that was, of course. That was the hawkish FOMC two-dot indication for 2023 rate rise, and the idea, the admission that they see inflation a little larger and hanging around a little longer than previously anticipated in their projections. And as such, That's really been the major trigger point over the last couple of weeks, um, in a few different asset classes. And for sure, EURUSD, you can see here, this is quite a key moment today about where we close. You can see we've bounced on 3 occasions from this level in the euro, but we are getting a bit of a divergence, of course, in the fundamental dynamics here between the ever more increasingly sounding hawkish Fed against, at the moment, a much more passive, more dovish-sounding ECB because they're just not making the same kind of hawkish noises to any degree of what the Fed are. And that's because obviously the eurozone, a lot more fractured in terms of the general national economic performances of the different nations, and also it is dealing at this present point in time with the latest outbreak and the uptick in the Delta variant as well, which is seen as a considerable risk. And that's likely to keep the the ECB's hands steady for the foreseeable future, whereas in the US, of course, we're talking every day about, you know, when are we going to start talking about tapering, when are we going to start hinting towards more rate rises, and so on. So here, technically, I think it looks interesting for the euro because if we continue this type of situation at the moment, fundamentally it's in play, that divergence which plays favorable for further downside. Technically now is where it's at, and technically it does look vulnerable and any further movement lower, the 118 kind of 11-18 handle would be the next obvious target. And we're looking about 50 pips lower from where we're trading at the moment, of course. Um, similarly then, the, the pound is doing the same kind of thing. There's been the eventual grace period extensions on some of the Brexit protocol around Northern Ireland and trade, but you remember what we were saying a few weeks ago, that was never going to go any other way in our opinion. So I don't think it's really that, that important, to be quite honest. But looking at the daily on the pound here, um, at the moment it really is that again, the, the fact that the dollar is putting in the performance at the moment, and that's weighing on these counterparty currencies. And so here, 138 handle has been a key milestone of support going back to late April, and also back when the dollar was appreciating. This was here, this was the base, this red candle of the hawkish Bullard comment initiated by here, this candle. So this move from 1.30— 1.41 to 1.38 was on the back of the hawkish Fed week and the Fed and the Bullard comments. And we're right back at that area at the moment. So when you're looking at the euro as well, at least this potential for that momentum, you know, if cable starts to also see a bit of head of steam on the breakthrough 38, then all the more conviction you might have to hold then for that euro move down to those lower bound levels we just looked at. So some key levels there in the FX markets to have a, have a look at. So eyes will be on the dollar. And obviously if it doesn't happen today, tomorrow is going to be a really key one. These are key technical levels that we're sitting at at the minute on a higher time frame. And so if the payroll number comes out tomorrow and it's a strong one so we start talking about a million-plus type job figure, uh, and robustness within the actual overall report, well then could that fuel further belief of the more hawkish rhetoric and then therefore appreciation further of the US dollar? And with these, those pairs sitting at fairly technically support-vulnerable levels, that could be a nice trigger for, for continuation of those short positions. Otherwise elsewhere Gold, you know, we looked at this yesterday and there's a really key area we've been looking at this week. And again, same top-level macro narrative. It's all about the Fed and the US and the hawkish rhetoric. So here you can see gold the same. Gold's just been a really nice kind of tracker of the inverse relationship with the currency, the dollar, at the moment. And so as the dollar's appreciated, just like those major pairs, gold's come under considerable pressure since the FOMC meeting on the 16th of June. And earlier this week— so this is going back 2 days ago on Tuesday— we traded through, and we did yesterday trade through that key area that I've been keeping an eye on around the $62 mark in gold futures. But we closed at that level, so we haven't closed below it. And so now technically I think that's just given a bit of light relief here for the yellow metal. We've just traded back up a little bit on the upside this morning, and we're currently up $6, trading at $77, having got down from as low as around $50 in the last two sessions. So I think technically this is looking a little bit more supportive now, having failed to breach that mark so far this, this week. But again, payrolls might well dictate that dollar movement, and subsequently move then will be the next kind of catalyst for movement in in gold. All right, quick look at then a few different things. Obviously a lot of people talking about OPEC at the moment. A familiar dynamic is really opening up with the alliance with Russia, Kazakhstan proposing boosts, which they've kind of done before. We've been here before, it's very familiar territory. Saudi Arabia and the Gulf Arab allies favoring a more cautious approach. This is according to delegates in Bloomberg, or who Bloomberg were talking to last night. While the group is expected to return some barrels to the market in August, obviously nervousness is still present on the back of the latest outbreak of the Delta variant, which is at the moment seeing an increasing global spread. For the, for the time being, the balance being there is our people, our nations who are large energy consumers like the US, for example, Have they been inoculated enough and is the economy reopening fast enough? That would constitute then one way or the other to add some more supply or keep it as it is, is the, is the debate. Possible supply hikes are being discussed for August and September according to Kazakhstan's energy minister. Not that that person is particularly important, but obviously they are very closely aligned with Russia. And last time they were giving a bit of a pass to increase just fractionally by a few hundred thousand barrels per day. Collectively, Russia and Kazakhstan kind of go as a team. They're a pairing in that sense. So I'd put a little bit of weight in those comments. As ever, the usual rules of engagement, I would say, with OPEC news, you're going to get further intensification of rumors and hearsay that might add to a little bit of the choppiness intraday for oil. And as ever, you're not going to have to wait for a formal decision. You're probably going to get more clarity as we go through the next 24 hours of whatever end outcome decision will be. As far as oil is trading at the moment, it's just wait and see. We're pretty much in a range at the minute between really $72 and, and the higher $74 price point. And so until we get more, more information on this, I just think we're going to respect that range for the time being. Some other things though to be aware of— well, this, this is oil over the first 6 months. I just wanted to quickly flash this given the fact that we talked about equities, we talked about the dollar. This is looking at WTI crude and Brent futures. And yeah, quite a, quite a phenomenal story actually over the last 6 months. If you take where we were and going back to the base from October, November time to where we're trading at from the year to date, which was around as far as WTI is concerned, sub-50, and we're up obviously up near 75 at the moment. So yeah, really solid performance there we've seen in WTI crude. And in fact, in terms of the streak, it's the best half for WTI crude we've seen since 2009. And again, it's all really— simplifying it— is based on the reopening trade. Um, other, other thing to mention on oil was what I thought was quite interesting was this. Um, so in the US, over the last 4 weeks, total stockpiles including the Strategic Petroleum Reserve, the SPR, have fallen at a rate of 1.15 million barrels per day, marking the largest 4-week decline on a rolling basis in the EIA's data going back to 1982. So again, just to make that clear, so stockpiling on a 4-week basis in America is being drawn down at its fastest pace that we've had in a very, very long time, which again goes, goes to show this overall tightening in the market on the back of the, the faster acceleration in the pickup in demand comparative to the fairly static situation on the supply side. And hence the reason the price is trading up at a multi-year high, up at around the 75 region. But again, this is the balancing act between the decisions that that mainly dynamic between Saudi and Russia need to play. The Saudis generally more cautious, let's keep it as it is, whereas the Russians, for kind of similar reasons to this, are saying like, right, we should, you know, demand is adequate, we should be, we should be relaxed, relaxing the, um, supply a little bit. And, and why not? I think if I was in Russia's situation and I was at a negotiating table, I would know that I can manage my budget at a much more lower price I know the Saudis can't because of their quest for general diversification in the period ahead. And so therefore, I would hold their feet to the fire. They will bulk, and I'll get a few extra 100,000 barrels over the line. I don't think necessarily from a trading point of view that's going to move the price to a great deal, because I think a lot of it is baked in, in terms of the 500,000. If you don't get the 500,000 or anything short of that, well, I think we could, we could definitely push up and start retesting, hitting highs again. So if I was the Russians, I'd be doing exactly the same type of thing, causing a headache, rolling over meetings. The Saudis will roll over and they will concede and they will give you what you need, which is a few more hundred thousand barrels per day. And then you just keep the supply pact intact, but you've got away with a little bit more of a concession than you were in the day before. So that's kind of what I'm expecting on that regard. The other thing here is a word that gets mentioned is Iran, and this is another key component that's in focus with determining the price of oil at the moment. Negotiation— negotiations over Iran's nuclear program are facing the prospect of renewed delays, is what we heard yesterday. And so the likelihood of a quick return of the nation's supplies are being kind of pared back. And remember, there's a lot of debate about how, how quickly can Iran in actuality, given the distinct lack of investment that they've had, the infrastructure— it's not like they just turn a tap and the nation starts pumping out an extra couple of million. It's a lot more gradual than that. However, they do have quite a large strategic stockpile offshore which they could start to bring back in, albeit I'd see OPEC having a big problem with that if they ever considered that being the case. But again, just the connection here being that a breakdown in dialogue, meaning that the further away the deal is, well, then that just puts off any notion of Iran bringing more oil back to market anytime soon, is the basic premise. Envoys negotiating over Iran's nuclear program will not reconvene as planned in Vienna this week, and apparently the talk is that they aren't even sure when the 7th round of diplomacy will be scheduled, according to 4 people familiar with that discussion. Who chose not to be identified and were close to those talks. So it's off for the moment. Timing is quite key, though. I would say that's not that surprising given timing of the OPEC meeting. I still think that it'll be interesting to monitor Iran through July before the inauguration of Raisi, the new president-elect, comes in in Iran, because I think tactically that does play true. I think if they are going to sign up back to this 2015 nuclear accord with the US and Western powers, that it's better to do so between July and August before the inauguration to pass off any concessions to Rouhani to, to maintain your political kind of capital as the new president-elect coming in. So it's something to watch going forward, but for now it's, it's delayed. The other thing then is, is China. A quick mention, overnight you do have some Chinese data. Again, I do not think that this this is a factor for the market open this morning. But to make you aware, the Caixin Manufacturing PMI for June came in at 51.3. That was a touch softer than expected. And so, as the headlines suggest, then, factory activity expanding at a slightly softer pace in June. The resurgence of COVID-19 cases in the export province of Guangdong, as well as supply chain woes, drove output growth to its lowest in 15 months, is what Reuters had reported overnight. More so, though, on the geopolitical side. You might have seen some of these shots from last night. Quite remarkable scenes actually coming out of Beijing last night. And this because President Xi Jinping warned against foreign bullying and China were marking their party centenary overnight. Xi pledged to build up China's military, committed to the reunification of Taiwan. This is a very contentious issue, of course. And said that social stability would be ensured in Hong Kong. Now, separate news that you've seen, but definitely related to this, is that the US and Japan have been conducting war games and joint military exercises in the event of a conflict with China over Taiwan. Now, this stuff is definitely not a coincidence. Obviously, the, the Chinese Party having this centenary event is a big kind of domestic deal. It's a chance for them to really, you know, galvanize the public on their, the mission that China has, and particularly on that One China policy, of which they see the sovereignty of Taiwan. And so the US and Japan conducting war games at the time of which they're celebrating their centenary is all absolutely, you know, calculated in terms of why they're doing this. You know, does this bring us any closer towards new levels of confrontation? No, this is just how politics is done, in my opinion, in that region. And so I wouldn't get too nervous about it, but just wanted to bring to people's attention who are not used to looking at this type of news flow that these things are not happening in isolation. They're all happening at this particular one point in time for the same reason, which is there's a lot of, um, political capital on the line, and there's an ongoing more top-level discussion and friction at the minute between the US and China, and all of this feeds into that kind of narrative. Okay, quick look at the, the day ahead. What have we got on the agenda? Um, it's this morning we have the final manufacturing PMI data points, so not anticipating too much out of those, to be honest. The OPEC meeting, yeah, I'd be looking out for news and, and tweets and so forth as we go throughout the session. I definitely don't think you're going to have to need to wait till 3:30 and 5 for more definitive confirmation. That's rarely the case, but those are the timings if you need to be aware of them if you're trading the energy market. Otherwise, in the US session, you've got the initial jobless claims expected to fall back down to 390 from 411. And then you've got the ISM Manufacturing PMI, which is expected to remain relatively unchanged from a headline perspective at 61. However, keep an eye as ever on that employment constituent. It's just hovering above expansionary territory of 50 last time out. And of course, people will be looking at that closely as a, as a kind of a contributing factor to give better insight as to how the labor report from the BLS might perform in NFP tomorrow. As far as speakers, a couple actually to be aware of. So coming up shortly, ECB President Christine Lagarde speaking at a hearing on monetary affairs, text to be released. So keep an eye out for that, 8 AM London time. And the Bank of England Governor Andrew Bailey speaks at Mansion House with text to be released, and that'll be at 9 o'clock this morning. So for any FX traders, euro sterling with these key levels looking as I said, fairly vulnerable at the moment amid just the ongoing dollar strength. I'd definitely be keeping an eye out for, for some of these comments, um, given that technical setup of those charts. Fed's Bostic, who is a voter, speaking at 7, and then supply out of Spain and France and the UK later on today. But that is it. So gonna let you guys go on with the day. Have a good one. Come on, Andy, it's only round 2. Um, but yeah, a little glimmer of the old Andy Murray came out last night, which was great to see. So good job, Andy. And, uh, yeah, have a good day, everyone.
More from Anthony


Inside the Biggest Banking Stories You Need to Know This Week (Anthropic, Diageo, Private Credit)


Inside the Biggest M&A Deals You Need to Know This Week (UniCredit, GameStop, eBay, Eli Lilly)







AI Breakthrough or Hype? Anthropic’s Claude Mythos, Tim Cook Steps Down & LIV Golf Collapse