Stocks & Commodities Having One Of Their Worst Weeks This Year
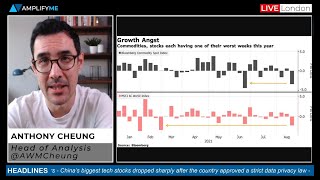
Global stocks and commodities had their worst week of 2021 as central banks signaled tapering, China cracked down on tech companies, and COVID resurgences hurt energy demand. Oil fell to the low-$60s, the dollar hit a 9.5-month high, and Goldman Sachs cut its Q3 US growth forecast to 5.5% from 9%.
Chapters
Introducing the new Tesla Bot humanoid. Yeah, I'm not kidding you. This is Elon Musk's latest publicity stunt, um, with him saying last night at an AI Day event that he's going to be creating a new humanoid bot to do physical tasks to assist human beings. I'll talk about that a little bit more in a moment. It's Friday, 20th of August. I hope you're well. Let's get straight into it and talk about the briefing this morning. And yeah, it's been a, been a real interesting week, really, actually, in terms of asset prices, particularly that of stocks and commodities. As you can see here, both are having their worst weeks this year. In fact, if we actually look at it, and it's been a combination of those things I discussed yesterday, obviously a trigger point and catalyst being the slightly more hawkish commentary on the timing of Most of the officials hinting towards tapering this year. We have got once again overnight just the latest sell-off in Chinese tech. Once again in the overnight session, it happened once more. China's biggest tech stocks dropping sharply, this time on the approval in China of strict data privacy laws. And this has prompted renewed concerns about the intensity of that ongoing Beijing regulatory crackdown. This is looking at the last kind of 3 years of the Hang Seng Tech Index, which includes those big giants like Alibaba, who hit a new record low again overnight, but Tencent as well. And you can see, having been north, well north of 10,000 at the beginning of the year, we're now below 6,000. So quite incredible what's been, been happening there. Then we've got also COVID that continues to be kind of weighted factor on the likes of stocks and commodities. And obviously some question marks over the efficacy of certain types of vaccines, which we were talking about with Pfizer yesterday, about the speed of which then the, the efficacy rate declines over time. And that has then the Delta variant dampened the outlook for US fuel demand and being one of the key reasons for, for definitely energy prices to have moved lower. And we've been seeing multiple consecutive down days in oil. It's stabilized a little bit this morning, but generally holding around the $63 handle. So far cry from where we were trading just a few weeks ago. Um, elsewhere, the dollar index as well continues to track up at a 9.5-month high as well. So on the daily charts, we're just thrashing out that previous high, as you can see here. If I just move it into screen, so and jump this over to a full screen. If I put this on a daily, it'll start to make a little bit more context as to the kind of hesitancy at around these levels that we have had. But we are now trading above, which was the third— uh, well, the 31st of March high on the peak, and we just managed to get above that this morning. Dollar's pretty flat, but just generally adding to and holding to the gains that were seen yesterday in the overnight Asia-Pac session. And that does provide generally now perhaps some, some headway on the upside still to continue for the, for the dollar amid that more hawkish commentary we had emanating from the minutes earlier this week. And, and certainly then from an asset class perspective, that's weighed on, on commodities, albeit they have stabilized this morning overnight. So we are respecting a relative range top right here in gold futures and pretty tight range between the pivot and the Asia-Pac highs only around a 30-cent range or so, um, at 6373 and 6404 in the overnight, uh, trade. As far as the close on Wall Street was concerned yesterday for equities, it was pretty mixed, really seesaw price action. And one thing I would say now is the calendar's really light today. It's actually not a great deal going on, and that does tend to then move investor attention short-term to just general overall sentiment. And being a Friday going into the weekend, it's going to be interesting to see, given the fragility of sentiment at the moment, how we hold up for the rest of, uh, today. Um, COVID side of things, yeah, things still not looking, um, particularly good at the minute in the US. There was a couple of things I was tweeting about you might have seen last night. Um, US patients who are dying in US hospitals at levels now not seen since February. Uh, that number now is north of 1,000, and the numbers could worsen as intensive care units overflow in parts of the South. And what some of these articles were talking about is that in Alabama, for one, there is now more people in ICU statewide than there are staffed beds available. Florida, Mississippi, Georgia, Texas are all using more than 90% of their ICU capacity at this present point in time. And then elsewhere as well, on the, on the side of COVID Australia's New South Wales has reported 642 locally transmitted COVID-19 cases. So that's meaning then that the state premier has announced they'll extend the Sydney lockdown to the end of September and impose curfews as well as masks to be worn elsewhere outside. And, and the Aussie dollar's really suffered With that commodity decline in combination as well with the ongoing continuous rollover as they try to tackle and contain the COVID outbreak has really weighed on that currency. And in fact, the Aussie is down around 3.5% from this time last week, and we're now trading at the lowest levels since early November of 2020 there in the Aussie currency. Sticking with the Antipodeans, the RBNZ governor came out overnight, and despite what has been going on more recently with the national lockdown in a very kind of onerous response to what had been quite a small outbreak, of course. The Governor Orr has said, of course, October is a live meeting. So still trying to keep that flame alive of the prospect of tightening policy in the near term. COVID cases, he said, alone would not prevent the RBNZ from tightening policy. It would take a significant shock to demand to change that view. And worth noting, overnight New Zealand have extended the national lockdown until midnight of August 24th. And what has all this meant? Well, obviously playing into that narrative of just weakening demand for oil is this idea then that we've hit kind of peak growth already. And we were talking about this in the last several weeks. Goldman Sachs economists were coming out last— or yesterday— they've lowered their tracking estimate of US economic growth in Q3 to 5.5% from 9% due to the impact of the Delta variant. However, they have raised their fourth quarter estimate to 6.5% from 5.5% on the prediction that virus fears will diminish and services sector recovery resumes and inventories are replenished. And so actually, they're kind of seeing it's a recalibration of the shape of the recovery. So more weaker in the near term in Q3, but actually accelerating harder on the catch-up through Q4 and beyond into 2022. So worth being aware of that kind of bank outlook. A few other things just wanted to mention as well from a single stock perspective. I have had quite a few questions recently requesting that I could talk about single stocks a little more. Uh, as I've said before, Eddie is the man for that single stock analysis, but certainly I can bring to you some of the main headlines for sure of things I just find interesting and, and things generally moving the market. And one company that was outperforming yesterday, and in fact the NASDAQ did outperform its, its relative peers. The S&P was up just 2/10, the Dow was actually down 2/10, but the NASDAQ finished up about 6/10, 1%. So it was the best performer yesterday. And Microsoft shares, I think, were up about 2% at the close. So they, they really outperformed and helped drag that index up given how big a company they are. It came after they increased prices on a bundle of popular products for businesses, and this is known as Microsoft 365, and it's the first kind of more substantial cost change that the company has implemented for the Office product in about a decade. And so given how widely adopted that is and that kind of recurring subscription model that they have, particularly for businesses to use, with multi-users and things like that. Certainly that's gonna, that's gonna help and explains that pop we had in prices yesterday. The other thing is, I thought were quite interesting was Amazon. They're planning to open full-on department stores. Now we've seen this before, they've opened up sort of more Amazon Go, more localized shops in certain states in America, also in UK, kind of checkoutless shops where it's all done electronically. But the company's latest move to bricks and mortar comes after Amazon this week, of course, has eclipsed Walmart in overall sales to become the world's largest retail seller outside of China. The Amazon department store strategy is this— is set to expand sales of Amazon's private label clothing, household items, and electronics, as well as independent brands. But I would say be interested to see how they, they fare in private label clothing. Clothing, a particularly competitive environment, of course. And, uh, and we'll see how people acclimatize to wearing Amazon clothes. I can't see myself doing that anytime soon. The other thing I thought was quite interesting was Facebook. They've unveiled, um, I mean, these, these shots are slightly childish. It feels like I'm playing the Nintendo Wii or something, but This is kind of the mockups that they were talking about unveiling, a virtual office app called Horizon Workroom. And it's a new free Facebook app designed to allow employees to work together in a shared imaginary office through their Oculus virtual reality headsets. So creating this kind of metaverse where people can come and this is kind of the next evolution for the post-pandemic world where people will still want to operate in the long-lasting, more flexibility of having the virtual environment as well as the physical. So I thought that was quite interesting. And then the final thing, of course, was the whole Elon Musk situation, which was what I briefly flashed on the screen, which I just thought was classic Elon Musk. He said basically Tesla are going to build a humanoid robot called the Tesla Bot. They announced yesterday. Context is always key when it comes to Elon Musk. I mean, he's, he's the master kind of puppeteer, and in the sense of he really knows how to capture the media's interest. And in fact, he was speaking at AI Day, and my understanding is there, that's where actually there's a lot of technical chat, particularly around automation, but particularly in the motor vehicle division, and it's them trying to attract talent. But obviously throw in some dancing man and then suggesting that, you know, this is going to be the latest thing that they're going to work on and bring to market next year. I can tell you now that's not going to happen. I mean, the promises that Elon's made over the years, these are kind of side distractions to help in the branding, the marketing, and it's definitely a strategy that I think has worked well for him. So yeah, all jokes aside, I just thought it was quite another stroke of genius from Elon Musk. But what I was a little bit disappointed in, to be quite honest, was that that wasn't Elon Musk and he rips the face off like Tom Cruise in Mission: Impossible. A little bit disappointing, but we'll have to wait for the next event, I guess. As far as the calendar is concerned for today, there's not a great deal going on. As I said, and we've already had UK retail sales come in and they were weaker than expected. The pound hasn't really reacted, but the pound is sat on the kind of wrong side of an area of support technically for this morning on what has been a continuous downward trend, obviously weighed by the strength of the dollar. You can see here cable has really come under some pressure over the course of the last week. And we were trading this time last week up at around 138 toward 39 handle. We're now heading towards the 136 mark. And again, we're just having a bit of a test around the, the double bottom of the Asia-Pac session. Now, the retail sales was weak. There's a little bit of context to be aware of there. The actual number month on month minus 2.5% versus expected plus 0.5%. 4%. Non-food stores reported a fall of 4.4%, driven by secondhand goods stores and computer and telecom equipment stores. I think food sales were also declining, coming down, backing off from the jump, unsupported nature of food we're seeing on the back of the Euro football tournament. And then automotive fuel sale volumes fell as well, about 3% over the month, the first fall we've seen since February of this year after heavy rainfall in early July impacted road traffic volumes as well. So I don't think it's too big a deal, to be quite honest. The market certainly is looking at it that way because largely unreactive, but definitely fits that overall directional narrative, which has been lower cable, but generally all of the peers against the dollar lower, given the relative dollar strength being the determining factor in the currency market. Looking elsewhere for the rest session, yeah, US, nothing really coming out. Got some CAD retail sales, Baker Hughes rig count, and that's pretty much it. And so a kind of slight word of warning, as I said at the beginning of the briefing, that always then typically starts to tend to shift people's view to just the broader sentiment. So just given how things have played out, certainly we'll be keeping an eye on the equity market on the open on the NYSE and also to see, as they are at the moment, oil, gold, silver, things like that have stabilized. But I think we'll start probably to see more definitive directional movement as we go into the US session later on today. So perhaps a little bit of caution and conservatism is prudent this morning. All right, that is it. Remember as well, it is Friday, so our head of trading is away at the moment, so I'm going to be joined by Eddie Donmez, who you will recognize, I'm sure, from the channel. Um, he and I are going to jump on and we're going to talk about our thoughts generally about the sell-off we've had this week in some of the things I've discussed. I'm going to talk about Afghanistan a little bit and my general view on that going forward and any implications for markets. And then Eddie's going to talk a little bit about a few single stock stories as well. So make sure you jump on Apple, Spotify, Google, whichever platform you use, just search for the Market Watch and Amplify. It should come up. And yeah, enjoy! Have a great weekend, and I will see you on Monday. Thanks, guys.
More from Anthony


Inside the Biggest Banking Stories You Need to Know This Week (Anthropic, Diageo, Private Credit)


Inside the Biggest M&A Deals You Need to Know This Week (UniCredit, GameStop, eBay, Eli Lilly)







AI Breakthrough or Hype? Anthropic’s Claude Mythos, Tim Cook Steps Down & LIV Golf Collapse