The Trading Week Ahead: 4th - 8th Nov 2019
Market briefing for November 4-8, 2019. US-China trade talks and a Fed rate cut support risk-on sentiment. Watch the UK election, Christine Lagarde's ECB debut, US ISM manufacturing data, and Chinese trade figures.
Chapters
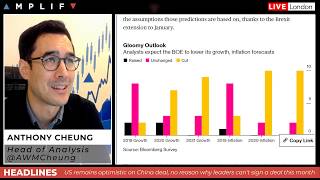
Okay, very good morning to everyone. Monday, 4th of November. Hope everyone had a good weekend. I hope any rugby fans have drowned their sorrows by now. But congratulations to Lewis Hamilton, one off now Michael Schumacher being the greatest F1 driver of all time. I'm sure Charlie will be thrilled about that. But having a look at the markets this morning, obviously Monday, gonna have a look at the usual calendar and try and figure out where the potential ebb and flow of the, of the next 5 trading days might come from. As you can see, always quite busy. Interestingly, later on this evening we're going to get the first speech from Christine Lagarde, having taken over now from Mario Draghi as the head of the ECB, as her president role. So she's not going to be speaking though to a bit later on, 6 PM. Then other things overall US data very much key throughout the week, European as well. Any manufacturing, PMI, and this morning, these are all final readings, so not looking really for too much of a catalyst from them. And then obviously you've got an update on Brexit because we get Parliament dissolved on Wednesday as the election campaigning gets fully underway. So before that though, we're going to have a look at the charts this morning and we've got some relative risk-on atmosphere sphere to proceeding. So equity markets already extending on gains following a positive session overnight in the Asia-Pacific region. So fixed income futures are trading to the downside this morning. If I just change this to the US 10-year, uh, trading down about 8.5 ticks in the bottom right. Bunds are down 32. Gold selling off as well this morning with the equity rally. Predominantly all of this coming on the back of continued optimism over the state of the US-China trade dialogue from comments at the weekend. I was just having a look at a couple of charts. Gold just seeing a bit of a downtick. I was just looking at a trend line from towards the end of last week, just breaking that, coinciding with some of the overnight Asia-Pacific price action on the lows, just causing a bit of a run to the downside through $1,513. So just looking at $1,510 spot for as the area where— just going to quickly mark up— you had the initial high on the 28th, touch on the low print on the 31st, and also resistance on that same day. So be looking around there as an initial target on the downside if we continue to, to move lower. And then you've got that actual low that was seen around 6 PM on the 1st in the wake of the payrolls number at 1509.5. As I said, equity markets still punching up at record highs. If you're looking at some of the US indices, I mean, looking at the daily continuation here of the S&P, uh, obviously last week we saw a meaningful break above the, the previous all-time highs, and we just continue to add at the moment. I guess on the top level macro themes, elimination of any subsequent risk from developing or escalating trade war, at least for the time being, we're in the positive part of that trade war cycle. And that, in combination with the Fed continuing to remain fairly accommodative with its third cut executed, keeps equities fairly buoyant. Looking on a more intraday perspective, probably the doubt— more bottom end of the range around 3068.75 would be an area of decent support now, now that we've made this kind of further push in the overnight Asia-Pacific session. Kind of gap, mild gap up. We then rallied up to that point, and that's acted as a nice level of support as Europe's come into the market earlier this morning. You can see around here, 7 AM, before then that eventual push-up. So I guess from a— again, there's no technical previous historical levels of significance given we're at record territory. So really, I'd say the R1, the intraday high, and that low point from overnight Asia-Pacific European low will probably define the range for the moment. So it could well be, uh, it wouldn't be that surprising to see a period of consolidation somewhat perhaps within that type of range in the S&P 500. Elsewhere, the Dixie a little firmer, uh, dollar index up about 0.1% for the moment. So some moderate downside seen in both major currency pairs to get things underway. I was just having a look at the euro chart here in the currency market. Um, if we continue to push down, we're sub the pivot at the moment. Then there's that area we were looking at last week. The market did respond to it quite well. This would have been on Friday amid some of the payroll volatility that we had. So any further downside, we're keeping an eye on that secondary level, but then also the low that we're seeing down here on the first switch will coincide with around the S1 today. So overall, relative risk-on atmosphere to get the week underway. Again, follows on from the, the decent payrolls report we had on Friday and the positive session we had overnight in the Asia-Pacific region. Uh, just going back then straight into some of the headlines, and then we'll revert back to the calendar to wrap things up. So this is some of the, the things people are talking about. This is the ongoing trade dialogue between the US and China. Commerce Secretary Wilbur Ross expressed optimism that the US would reach a phase one trade deal with China later this month. President Donald Trump on Sunday told reporters at the White House that a trade agreement, if one is completed, could be signed somewhere in the US. Again, this is because of the delay of meeting that was supposed to happen in Chile because of the civil unrest that was happening at the APEC meeting. Then on Saturday, after a call between the officials, Chinese state media reiterated the nation's core demands, including the removal of all punitive tariffs. For China, they quote said, removing all the additional tariffs is a core concern that has not changed and will never change. Even if there is a first-phase deal, the core concern should be reflected. Again, Beijing, what do they want? Well, they want the US to do away with any new import taxes due to take effect on the middle of December, December 15th. On goods including smartphones. And again, that, that deadline, probably reason why we've got this degree of optimism on this trade side, because that is still quite a way off, what, a good 5 weeks or so until we get to that point, or 6 weeks. And obviously the other big risks for markets that may come as well around that time, whether it's the UK general election or the Fed rate decision, all seemingly happening around that mid-December timeframe. So all looking good thus far, but I would recommend that as we go through the week, this continues to be a fairly fluid situation. It doesn't take a lot, given that we're in a positive state of mind and where participants' kind of focus is on this issue. Wouldn't take much then to see a bit of a pullback if things start to unwind in the dialogue between the two nations. Otherwise, having a look at Brexit, what's the latest here? Well, obviously everyone's looking at the general election now, uh, with Parliament set to dissolve on Wednesday, meaning that really that gets fully underway. This is one of the polls on the weekend coming out from, I believe this was YouGov. Let me get the right one. That's the average Westminster. This was the YouGov one, had Conservatives at 39%, so up 3 points. Labour were up 6 points, uh, 27. Lib Dems down 2, Brexit Party down 6. So quite interested to see a pretty decent bounce back by Labour here in the latest polling. One thing though, and a couple things to be aware of, the more I read about this general election, the more I think that polls are, uh, are less and less relevant really this time round. And the reason for that, uh, are kind of twofold. One is some interesting things here. This was a graphic out of the FT that I saw at the weekend, and it was talking about how local battles in 2019 UK election will be tighter than ever. And basically the FT have done a data analysis going back from 1918 to 2017, so taking a 100-year kind of sample of all the elections that have happened. And typically the median seat has been won by a total vote share of 53%. And that makes sense because if you think about it, I think since the early 1920s it's always been the Conservatives and Labour that have won UK general elections. But however, this time round it's much more divided. And why is it divided? Well, that's because of really this— UK politics is obviously completely polarised at the moment where all other issues are kind of off the table, and really this is a vote of of whether people really want to leave or remain. So it's kind of Brexit or no Brexit that really defines this. And political allegiances are the weakest that they've been in a long, long time. And actual political parties, how much of that is really part of what it is that you're voting on, it's really very little. What it is is a key issue, and what they feel most strongly about is how people identify with the notion of leaving or to remain, rather than their political allegiance to their regular party. Hence the discussion we had at the end of last week, why areas like Wimbledon could be targeted by the likes of the Lib Dems. So from an average seat basis, 'cause remember it's first past the post is how a UK election works, they're estimating in this analysis in the FT that this year the median seat could be won with as little as 39% of the vote. Again, given the fact that there's a much bigger division between the split of votes between other political parties, including the Liberal Democrats this time round. They did say as well as many as 15 seats could be decided by winning just less than 30%. This would be way down on the 53% that we had seen in previous elections. So some quite interesting facts there that I thought I'd share. The other things this week for the UK, we do have the Bank of England interest rate decision coming on Thursday, but I would say this is likely to be somewhat of a, of a non-event. And the reason for that is because Brexit has been kicked down the road again until obviously the end of January 31st, meaning that really there's little that the Bank of England can do in terms of altering or policy or their forward guidance. However, they are going to be releasing their growth and inflation forecasts. Remember, it's November So it's the quarterly inflation report for the BoE, and this is what analysts surveyed by Bloomberg are looking at in terms of potential changes to the outlook. You can see for 2019, 2020, '21, growth is very much expected to be cut. In terms of inflation, 2019, 2020, it's kind of unchanged, possibly for this year, just given the fact that we've only got 2 more months of the year. but then substantial decreases to the outlook for 2020 and '21. So it's— I don't think the Bank of England really is going to be that meaningful event, and as they say, very much expected is for a downgrade to both growth and inflation forecasts in the latest QIR. Nonetheless though, Mark Carney will be delivering his usual press conference, so that'll be something we'll be looking out for later on Thursday in the week. The other thing from the UK, from a news perspective, obviously John Bercow is now gone, meaning that the House of Commons will elect a new Speaker today. I think it's pretty much a one-horse race if you're reading the press at the weekend. His deputy, Lindsay Hoyle, is seen as the favourite to win the ballot according to the bookies. The Labour MP has framed himself as the antidote to Bercow and said his style of using humour can help defuse tensions rather than rile them, as his predecessor was often guilty of doing, as some opinion. So I guess the question is, from a trading point of view, does the House— does the nomination of the House Speaker have any influence or potential for the pound today? I'd say no. Of course, the Speaker is an important pivotal person because they shape the debate and the hearings that happen in the lower house of Commons. However, not only have we known who the front-runner is for some period of time, that shaping of the debate— really, we already know what the debate is going to be because we have clarity, and Parliament's going to be dissolved. So really, the election's the focus here, not so much the Speaker. Speaker may well come into play a few months down the line if Brexit truly is being kicked down the road again, of course. So that's pretty much the summary of the headlines overall. Going back just quickly then to this calendar to have a look at a few other things. Later on in the session today, you do get US factory orders. And from a US data perspective, Tuesday is probably the one that I'm watching with most interest. You get the likes of US trade balance, service PMI, IBD TIP economic optimism, but most importantly, you get the ISM non-manufacturing PMI. So just given some of the recent string of economic data from the US, I'd be particularly interested to see how that one comes out. Otherwise, looking in other nations from a data perspective, you've got the UK service PMI coming on Tuesday. So you get the construction number a bit earlier on, or later this morning, I should say. You then have German factory orders on Wednesday, German industrial production on Thursday. Thursday, which also will be quite interesting to watch, just given how heavy in contraction the manufacturing sector PMI has been for the German nation. And then on Friday you get Chinese trade balance and inflation readings to follow at the weekend on Saturday. From an interest rate perspective, do be aware you've also got the RBA. So it's going to be this time tomorrow. We already know the results because it's going to happen overnight in the Asia-Pacific Pacific session. Uh, rates not expected to change from the RBA, but nonetheless worth keeping an eye on the Aussie overnight. You also get the Aussie monetary policy statement to follow overnight on Thursday going into Friday morning. So that is pretty much it. Not going to speak for more than I need to. So I hope you all have a good week ahead. I'll be around on the desk all day, so any questions please do let me know. I'll probably mark up a few charts and just share them in the chat room rather than issue the normal weekly strategy today, just to make life a bit easier. Sam not here today, he'll be back tomorrow. So any of the remote guys on stage 3, if you just message me in Trading Live, it's the best form of contact. All right guys, have a good week ahead.
More from Anthony


Inside the Biggest Banking Stories You Need to Know This Week (Anthropic, Diageo, Private Credit)


Inside the Biggest M&A Deals You Need to Know This Week (UniCredit, GameStop, eBay, Eli Lilly)







AI Breakthrough or Hype? Anthropic’s Claude Mythos, Tim Cook Steps Down & LIV Golf Collapse