US stocks mixed as markets await US Q1 GDP data
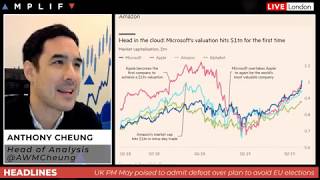
In this morning market briefing, the host (Speaker A) provides a comprehensive overview of the U.S. equity landscape ahead of the release of Q1 GDP data. He begins by contextualising recent S&P 500 price action, noting a brief intraday sell‑off that was quickly recovered, and outlines the current technical consolidation zone around the 3,000‑3,100 level. The discussion then shifts to corporate earnings, highlighting strong performance from Microsoft (which reached a $1 trillion market cap) and a flat Amazon, while calling out disappointing results from 3M (a 13 % drop, the worst single‑day move since 1987), Intel (first annual data‑center revenue decline in a decade), and mixed outcomes for UPS, Daimler, Deutsche Bank and RBS. A separate segment examines the rising trend of regulatory fines on technology firms, especially the multi‑billion‑dollar penalties faced by Facebook and other big‑tech companies, and the potential impact on long‑term investment theses. The host then provides a quick European earnings snapshot, noting profit warnings from German automakers and revenue cuts at Deutsche Bank after a failed merger. Brexit developments are covered, with an emphasis on Theresa May’s struggle to avoid a UK participation in the upcoming European Parliament elections and the strategic use of a June 30 deadline. Oil market analysis follows, describing a technical support level around $64.79 per barrel, a continued eight‑week rally—the longest since 2015—driven by geopolitical tension. The core macro focus is the upcoming U.S. Q1 GDP release. The host outlines the consensus median (2.1 % annualised), the range of forecasts (1 %–2.9 %), and the Atlanta Fed’s GDPNow model projecting 2.7 %. He suggests market reaction will be more pronounced on a downside surprise. Finally, the briefing notes upcoming sovereign rating updates, particularly S&P’s review of Italy, explaining the criteria that could trigger a downgrade and expressing confidence that a downgrade is unlikely given recent spread tightening. The session closes with a brief banter and well‑wishes for weekend marathon runners.
Chapters
Okay, very good morning. It is Friday 26th of April. Hope everyone is, is doing well. I'm just going to have a quick then look around the markets, going to have a predominant focus on, on corporate earnings. Of course, that's been the, the major theme for this week. I'm going to actually— before we look at this heat map talk about just a bit of a broader context of the week in the S&P 500, because yesterday, a bit of a roller coaster. We did see pretty aggressive drop shortly after the cash equity open, but then we recovered completely by the, by the time Europe had left. Before then, the kind of aftermarket movement came, and there's a couple of, of earnings in particular, Intel for example, which we can talk about, which was particularly bad aftermarket last night. But, you know, other than this, this kind of short-term volatility, I do think it's worth, you know, stepping back for a second and just looking at the broader picture. And by what I mean with this is just looking at where we are at the moment, you know, in the broader context. And it's, you know, an area of consolidation around these levels. You know, me and Sam were talking about this yesterday when we had a brief, uh, kind of conversation about what our thoughts were and And although, you know, from his point of view, he's still looking for a push beyond these all-time highs and eyeing up the 3,000 level. That's not, though, without some type of pullback. And this, this rectangle we've got here was what we were talking about yesterday, where, you know, the kind of most strongest point of support where all things being equal, maybe a little bit gets booked off the top here, but we pull back and then looking to go long. But in the near term, you can see there's some other clear points of interest where we've kind of settled at the moment in the futures at 23.5. That's that, you know, if I just run my mouse over, that's that previous area of resistance here and, and kind of support. But then if we broke back down, then you've got the next line, which is the psychological 2900 handle, of course, as well. So, you know, as much as there appeared to be some ebb and flow yesterday, I think kind of stepping out of that intraday noise a little bit on the more medium term Equity still looking good, I think, for the moment, despite what has been a bit of a sour ending to the week in, in a couple of corporate earnings. Mixed picture actually by the close on Wall Street. This is what it looked like, and as you can see, you've got some decent performance from the technology space, in particular Microsoft. Of course, they reported the prior evening, really solid numbers, and actually the gain of 3.3% with a pretty flat Amazon performance meant that Microsoft has bumped itself back up the table and it's hit its first $1 trillion valuation. Interesting, I guess, you know, Microsoft, the company which, you know, largely a lot of people hadn't been talking about, I would say, until the last kind of 12, 18 months. But, um, you know, my brother works in in the technology space nowadays, and he's been banging on about Microsoft for a long time about what they've been doing, particularly in the cloud commercial computing area. And definitely they've, you know, their share price looks the most kind of calming, if you like, comparative to say, look at Apple. I mean, what a roller coaster they've been on. And, you know, for a company of that size to see that type of swing in share price when it comes to someone like Apple You know, it does make me— would, or would make me a little bit concerned if I was a longer-term investor in stock price. You know, if I was picking— you know, if you were playing your bets in the long term, your kind of pension play, long only, just holding a stock for the next 25 years, then, you know, if you're going to pick Microsoft, Apple, Amazon, Alphabet— well, I don't know, Apple one is the one that makes me look most nervous. That's looking at the charts, you know, performance, not even getting into the nitty-gritty of the actual nuts and bolts of the company and its future. So yeah, I just thought it was quite interesting, you know, the old saying of slow and steady wins the race, and Microsoft definitely has bumped itself ahead at this point in time. Going back though to the, the heat map, there was one particular you know, it was quite a good day for representation of the kind of sector breakdown of an index like the S&P. You can see here you got the biotechs, healthcare generally as a sector performing pretty well, whether they're drug manufacturers or biotech or medical application firms. Technology, some of the majors, obviously Microsoft and Facebook were earnings-inspired. But then look at the industrial goods down in the corner. And there's one company in particular there, if I just hover my mouse over, you can see 3M. Now 3M, an industrial company, one of the biggest components within the Dow of course, they were down 13%. If I'm right, the stat is that it was the worst performance that they've had in a singular day since the crash of 1987, to put it in some perspective. I mean, I was looking at the share price though as much as the The news agencies, of course, love to band about those types of dramatic statistics. I'm pretty sure that that just puts them flat on the year. So yeah, if you actually look at their share price, they've obviously shot massively higher with the recovery in the market. Most of these tech stocks are up kind of north of 25% as it is, and the industrials a little bit lagging behind but still have made decent gains. So it puts them pretty much back scratch for the year. as its share price. A few other things that I just wanted to mention. I did see, it was actually ZeroHedge were talking about this yesterday, and I thought I'd comment on it because I just thought it was an interesting perspective. Now this, this chart that I'm showing you here is the size and the company involved with fines either from the FTC, US-based, or the EU. And this is looking then— normally when we look at this chart, uh, horizontal going from 2009 to 2019, so the last 10 years, we're usually talking about financial firms and whether it's, you know, FX manipulation tied up in the LIBOR scandal, you know, the inappropriate selling of financial products, subprime related, of course. You know, this has been such a recurring theme for the financial sector, but what I thought was just quite interesting is you know, tech fines have really ramped up more recently. And obviously the Facebook Cambridge Analytica scandal has definitely brought that data privacy issue to the forefront. And I just thought, given what Facebook was saying yesterday with them putting aside a multi-billion kind of litigation contingency fund, it's just quite something I thought that if you were, if you were invested in these types of companies in the longer run I would say that likelihood is the way that regulatory environment is going in the data space that you could probably imagine that this will continue, this kind of pattern. You know, just to put this into some kind of perspective, we're talking about fines to the magnitude of from $1 up to $15 billion. You know, these aren't small fry. But the one thing I would say, of course, is as long as litigation reserves are there in these companies And repetition, i.e., with the financial sector now, if a bank is subject to a large multi-billion fine, typically it doesn't move the share price these days because we're just used to it. These banks did a lot of, uh, by the law, quite interesting things, let's say, without putting myself in too much hot water. And so we're kind of used to that. That's just, it's a state of play. And, you know, is that to be the case with the tech sector? You know, if you were running a tech-oriented company, you're always going to be looking to push the boundaries in terms of utilizing data and information. And so the regulatory environment typically is always slow to catch up with that. All right, a few other earnings though that came out last night. This— well, before I finish, actually, 3M was obviously the big disappointment yesterday, but you also had UPS, which is quite interesting. Given the fact that, you know, some people look at that as a reflection for just general, um, the economic environment from a bellwether perspective, given how used their services are. I think it's a bit of a tenuous link these days, just giving how, you know, kind of powerful now Amazon has become. But Intel came out after market, and the data center unit of the firm posted a yearly drop for the first time in in a decade. They also said demand deteriorated from their earlier projections, so basically cut their guidance, and their shares were down about 7%. Interestingly, I just caught a talking head on Bloomberg and he was just talking about Intel, and he was saying how they're still heavily involved in the kind of server business, home computing, things like that. They're not actually that exposed at all in the mobile space, which obviously is where the game is at in the future going forward. And the fact that as well Qualcomm won, won that ruling with Apple to now recommence the use of their chips, which Intel was filling the gap, you can understand why people have got a little bit apprehensive about Intel, uh, in the kind of medium long term. So yeah, Intel was very disappointing. Uh, moving on to the other big name that came out though was Amazon. Uh, and all in all, Amazon was pretty flat, not really a great deal of aftermarket movement. That being said, they reported a huge beat on profits and matched estimates for revenues. However, their outlook again is, is something that people are looking at. So although they massively outperformed for the quarter, it's about the forward-looking guidance. Over in Europe, a couple things to be aware of for DAX traders. You got Daimler this morning. I'm looking at the opening calls here in regard to ahead of the cash open shortly in the next couple of minutes, but Daimler's actually seen pretty flat I would say that's based on the premise of the fact that Daimler— if I remember rightly, it was about 3 weeks ago— Daimler, VW, they all came out and basically gave a profit warning anyway. So it's baked into the share price. So the kind of factual figures coming out from the quarterly release doesn't really have or yield too much new information for the market. So Daimler sounds bad, of course. But the global car makers have— and this is very typical of earnings season— if you have bad information, they've already front-run this by coming out early, taking the hit, so that when the actual full accounts come out, they, you know, the, the markets are already fully aware of what the situation is. The other one is Deutsche. Deutsche is called down about 1.5% pre-market. They cut their revenue goal after merger talks have collapsed, of course, which we heard yesterday. That kind of commerce Deutsche deal has fallen down. I think that's pretty much to be expected, to be honest. A kind of collaboration of two banking giants like that's always going to have a complex time getting approval from a regulatory point of view. The bank suffered its 9th straight quarter of revenue contraction. And so, yeah, still, still one to watch, I'd say, is Deutsche from a, from a kind of stable point of view because it has obviously been one of the, uh, the dark spots of the European banking sector. On the other side of things, you've got RBS. I, I couldn't actually get a call for them, uh, if you're looking at the FTSE, but they did beat, um, profit estimates. But they again, forward-looking, um, much like with any bank within, uh, the FTSE and UK domicile, that you're going to have such implications from the outcome of Brexit in terms of the financial services performance for the UK. So yeah, they see Brexit challenges deepening, so a little bit pessimistic about the forward-looking, but I think this is pretty much top-level management of trying to manage market expectations. You kind of prepare for the worst, hope for the best situation. I think it's prudent planning. So even if their shares come off one or two, I think is probably a sensible thing. All right, moving off earnings, let's have a look at something else. Sam's here now, so I'll prep him up. Sam, you're gonna look at some charts, my friend, in the next few minutes, so just so you're aware. So yeah, let's— Brexit, this is the latest. And obviously from the beginning of the week, we've been talking about this idea that Theresa May was going to try to put forward instead of her her actual Brexit deal, which has obviously failed in Parliament 3 times. She was going to go through a more legislative kind of approach and try to bring forward this withdrawal rights bill, which then could be voted upon from the legislation point by point. It's a slight kind of technicality, if you like. Now, at the beginning of the week, there was some pressure on Theresa May. She needs to get this done basically within the next week in order to give Parliament enough time for that process to be complete so that then they can say, "We're not going to take part in the European elections at the end of May." Now, this is the latest headline, of course: "May is poised to admit defeat over plan to avoid European elections." So basically, the insiders and officials in the government are saying that basically time is running out. She wanted to avoid the EU vote, obviously. Taking part in these is going to be highly damaging for the Conservative reputation as a political party. You can kind of understand though, I actually think that this was almost inevitable. If you think about it, she's trying to broker a deal with the opposition, and if I was the head of the Labour Party, I'd be sitting there going, just, you know, absolutely no, let's just play it out because let's, let's go into the European elections because it's only going to be beneficial for the— not popularity for Labour, but a diminishing popularity for the Conservatives. I guess the risk here would be, does someone like Farage, who's obviously gearing himself up to gobble up the dissatisfied kind of voter, and also MPs in Parliament in that fact— so yeah, I'm not too surprised by this, to be honest, but it's looking like we're going to have to take part in those European elections. One thing I did see in here, let me see if I can find it. There was another now new date that you need to be aware of. If you just give me one second, I did read it this morning, but it was basically saying that there's another date in June where it kind of is the next kind of pivot point in these, these talks. I'll have another look. I've shared this article with you guys. Here you go. May's next target will be to pass the bill by June 30th. The day newly elected European Parliament members take their seats. So again, this is kind of, I guess, the next obvious kind of strategy. Okay, we'll take part in the elections, but then before the kind of first sitting of the, of Parliament in Brussels, you kind of then pull out all your MPs just before. So again, in these types of negotiations, if you allow any type of wiggle room like this is, which is really another soft date that you can go to. It's always going to be delayed. It just heightens the leverage that you have as a negotiation tactic. So yeah, the pound's not moving. I'm not surprised is the point. All right, another thing we're gonna have a look at is— and I'll save, um, I'll save Sam to go into oil in, in much more detail— but I was just looking at oil here. Obviously we, we've had a, um, a week where we've shot higher right at the beginning on the back of the, uh, the Iranian story. Consolidation and then a breakthrough technically yesterday in what has been as well a really robust dollar. Don't forget the Dixie is still trading up at this multi-month high at the moment. And so we pull back and we found some support at a pretty decent technical level. You can see here that resistance point through, through the best half, or the first half I should say, of April, uh, just acting out as a nice level for the bounce so far during the Asia region. Again, from the longer-term perspective, the thing that we've been looking at, of course, these, these kind of charts that we mark up on a, on a weekly basis, you can see, I think, this area here at 6479. So if we go back here, basically where we are on that multi-test resistance turn support, you can see here on the longer time frame that goes back to the August low and the June lows. So I think this is a really strong level here, that meaning two things. One, I still feel comfortable more from a directional bias for the long here from the lows, but if we break, then I do think we get a decent pullback. And again, the next kind of target would be the low end of the range here. So again, you start playing the next areas of consolidation. Any breach of that brings us back down to these areas really here, which would be the 63 handle, which obviously is quite a meaningful pullback. But again, to emphasize, I still think we're at a pretty strong point here from a support perspective. I'm talking about oil. Obviously, oil has had a decent run on the back of, you know, a lot of geopolitical tension, if you want to call it, in particular. And it is set to rise for the 8th week, and that does mark the longest run of gains since since 2015 from a, from a statistic point of view, just so you're aware. All right, moving forward, uh, this is kind of the main feature of the day because it's kind of lacking in, in European and UK drivers, and this is US GDP. So this is kind of being the main focus at 1:30. This of course is the advanced reading for Q1, and this is the median expectation, the red bar on the right-hand side. We're looking for— actually, it's been revised slightly. It's actually a 2.1% reading we're looking for, but we've got a pretty sizable range. The low estimate on the street is 1%. 1% obviously would put us back down to the lowest growth levels that we've had since all the way back at the end of 2015. On the high end of estimates, 2.9%. I mean, that would put us back to Q3 of last year, so not so long ago. So one thing I didn't mention this in the, the Monday strategy was the Atlanta Fed GDP. Well, let's just see if that has had any updates at all. This is called the GDPNow model. Again, if anyone's not familiar with it, brief overview, it's basically a, an economic model that mimics the same methodology of the the way of which the government calculates its GDP data. The only difference is, is that this model updates with new economic inputs as and when they come out. So it's kind of a rolling real-time reflection of the movement of what this should generate for the overall government reading as well. And the Atlanta Fed model here is generating a forecast of 2.7%. So on the balance, I would say then that there's, there's a, there's a potential upside likelihood to this data point coming out. And therefore, I would say arguably the bigger market reaction might come if we had a downside surprise, because most people probably will be leaning for an upside figure, if anything. Otherwise, the final things I wanted to mention here on the calendar was something a little bit different because we don't get it that often. Tends to come on a quarterly rolling basis, but you'll see at the bottom of your calendar you've got some rating agency updates pending. These will come after the European close. I think they normally come between anytime between about 5 to 7 PM. But from the UK's perspective, you've got S&P and Fitch. You know, when these, when these are listed as kind of rating updates these don't necessarily— and in this case actually not expecting, and is more often the case, not actually expecting any type of upgrade, downgrade. But what we could see is a change in the outlook. Outlook negative, positive, and so on. UK, it's already been prepped up, and I don't think really anything has materially changed enough for us at this point, at least to make enough from a rating agency point of change in their decision-making. The one that could be quite interesting— S&P is the kind of largest of the rating agencies, and Italy are due for their review. Now I was just looking on the FT this morning, S&P said last time— and so back in October, S&P left Italy a notch above the dreaded junk rating, so BBB, one step above Moody's and in line with Fitch. Now S&P said it could lower its ratings if it saw a material undershooting growth, a significant push higher in debt ratios, or a market deterioration in external financial conditions, with a nod to political uncertainties and their impact on the country and its banks. Now I would say with pretty strong assurance that they're not going to get downgraded, because if you were going off the conditions of which S&P have stated here If anything, the spreads on the 10-year benchmark have tightened, because if anything, I'd say although we're far from a political solution in Italy, it's definitely stabilized from what we were seeing several months ago. So despite us being in a technical recession, I don't think that there's too much risk to this, to be honest. But if it did happen and Italy was cut to junk, yeah, I might need to jump back on my my account later on this evening and see what's going on. Alright, let me hand you over to Sam then, welcoming him back to the fold from NYC. So with that, I wish you a good weekend. One final thing, if anyone is running the London Marathon this weekend, absolutely good luck. I wish you all the best. Not an easy feat by any means, so good luck. All right, take care.
Didn't you take like 5 hours when you did it?
Yeah, almost died.
Hi guys, good morning. Hope everyone's had a good week so far. Um, let's start off with a couple of the currency pairs. Just seeing this morning a touch, and it is only a touch, of dollar weakness as a couple of the pairs and gold in particular have pushed higher after drifting lower yesterday. Early morning. Just going to remove a couple of these here. It seems like the, the line in the sand, if you like, for the cable really is the, the high of yesterday, which is the high of today, uh, just recently, uh, acting as good resistance there. You've also got the, the R1 in the mix, but as a, as a key level goes, you've got to imagine if we keep testing here, uh, it's gonna get worn down and we could get a push through that, uh, to To the downside, I think if you're looking for a bit of a continuation, if you're not already short from that high of yesterday, which obviously would look pretty, pretty good right now, maybe worth getting on a bit of a trend line from those lows from yesterday, which you can see just failed to break down. And then into this morning, early hours, 2, 3 o'clock, looking for that break of what could be a bit of support from the morning, that trend line, and that could see a continuation of of this market, uh, moving lower. Similar sort of story for, for euro. Key level, uh, using one of the highs from yesterday. You've got the R1 in the mix, you've got the, the high that we made, uh, around half 3, uh, 112 handle on the futures. So as a good sort of zone, that should be somewhere that I'd, I'd be looking at. And same sort of thing for a continuation, uh, looking at potential for one of these sort of trend lines to to give way. And it might be that that and the pivot going leads to a further push lower. I think for this market, uh, as you can see, the, the trend really going back to the 18th has been to the downside. And each opportunity of any retracement over certainly the last couple of days has been a good opportunity to buy. So, you know, not too bad to perhaps look at that R1, all things considered. As an interesting area. But if you are looking for that continuation, which sometimes could be the safer play, looking for that, that trend line and pivot to go might not be the, the worst idea. A couple of, uh, smaller time frame charts I think to be aware of here. You've got the, the NASDAQ, which, uh, I'll just put this on a 5-minute. You can, huh, repost. Oh goodness. Um, if you have a look at the, the NASDAQ here, just going from the, the low of this early morning and see we're just testing and we're actually looking perhaps to, to break this trend line now. Um, it could be that if you get that breakthrough, obviously yesterday evening with the earnings and whatnot pushed down, we had a bit of a recovery from this morning, but a breakdown of that might see a further push lower. Interesting support from early hours of this morning, uh, could be the target of that as we're looking to, to just have a little breakdown of that. Another chart on the 5-minute I think worth having a look at, and mentioned oil and the really good support that we did have, uh, but with that trend line from that low, you can see marks up quite nicely with the test that we had at 5 past 3, 5 past 7, and 5 past 8. So just having a look at that a breakthrough of, uh, that trend line similar to the NASDAQ, you might then get that, that further push through. And just to reiterate that support level that Ant mentioned, you can see just how important those resistance points were going back to the beginning of, uh, of, of April of this month before that breakthrough on the 22nd. We just retested that now. So on the 5-minute, we'll be keeping an eye on that trend line to see how that holds. And yet again, another good test of that. The S&P yesterday, a good solid support that we had from resistance back on the 21st, 3rd, and you can see a good farewell or a failed test lower of that held quite well. Similar to NASDAQ in the sense that I probably would get a trend line on from those lows. You haven't got the third test just yet, but if that was to come into play, that's something I'd definitely be, be keeping an eye on. You can see S&P just on the low of its morning. So let's have a quick look back at the NASDAQ, which you can see, just putting that back, is just testing. So it would be worth, you know, keeping an eye on it. Obviously the volume is going to be slightly lower, but that breakthrough now might start to see things just weigh down slightly on that as well. Dow Jones has had pretty good, uh, support level You can see as an area goes, it might be worth— well, as your sort of key level to keep aware of for the downside, the low that we had on the 15th, the 18th, and yesterday as a really key point on the futures coming in at 26,300 or just a bit above. That would be my sort of area that the bulls would really want to take control of and defend again this week. We get a breakthrough of that, you've got to imagine the the highs that we had back on the 10th come relatively quickly. But yesterday, the, the support levels we saw early in the week for the Dow Jones, NASDAQ, and S&P held pretty well. But stocks just on the back foot a touch at the moment. The yen, after having weak— well, yeah, weeks I guess of very little movement last couple of, of days excluding today, you saw some decent price action. But we are coming into, on Monday anyway, Golden Week. The beginning of that, and you've got to imagine people should be starting to, to lock off ASAP. So I wouldn't be expecting too much in the way of even movement, if you like, for the yen as price action from Monday really does start to stall down a bit. Just having a look at this, this market now, you can see it's already reacted quite choppy to the pivot, and I wouldn't really be too keen in getting involved in, in this as it's stands. Having a quick look over the, the general picture, you can see the, the DAX is finding, uh, resistance. I'll just bring this into picture. The resistance here at the, the pivot, uh, tried to fill that gap but not just yet. The sort of second test of that pivot holding up quite well. You've got bonds in, in Germany and, and the US just on their higher points at the moment, as stocks in the US just coming under tad pressure with that weakness of the dollar this morning. You can see gold did push up, but this trend channel still very much respected, and what was the previous high of the 22nd, even though it was chopped through yesterday, acting as a relatively good level of support for now. Might be worth still having it— well, will be worth still having this on, perhaps waiting for either the level support to come in or the resistance, and taking a look at how the dollar is, is reacting. I hope you all have a good weekend, and any questions please do let me know. And I reiterate what I said, if anyone is running the London Marathon, you're crazy, but good luck. The morning likely to be relatively range-bound, and the best action to come in the afternoon. Keep an eye on stocks for this morning and those levels in oil with those trend lines. Um, but yeah, hope you all have a, a great, uh, weekend ahead.
More from Anthony


Inside the Biggest Banking Stories You Need to Know This Week (Anthropic, Diageo, Private Credit)


Inside the Biggest M&A Deals You Need to Know This Week (UniCredit, GameStop, eBay, Eli Lilly)







AI Breakthrough or Hype? Anthropic’s Claude Mythos, Tim Cook Steps Down & LIV Golf Collapse