What Happened To Gold Overnight? And The Week Ahead In Markets
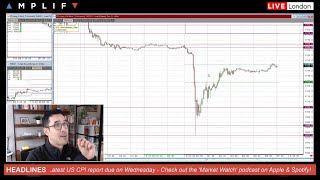
Gold crashed overnight on low liquidity and stop-loss cascades, not news. Crude fell $1.50 as Delta concerns and OPEC supply increases weigh on demand. China's inflation hit 9% while exports slowed, and ECB's Weidmann pushed for faster rate hikes.
Chapters
A very good morning to everyone. It is Monday the 9th of August. I hope you're doing well. Hope you had a good weekend. And yeah, gonna cover to start with the flash crash in gold overnight. Already had a lot of messages in my inbox in terms of this morning, so I'm going to cover that first. But then also we're going to talk about the fact that oil again is under some pressure this morning, down over $1.50. And this comes after extension of losses after the worst week since October last week. We're also going to talk about China trade and inflation from the weekend's data, updates on the US infrastructure bill, and then the outlook for the week ahead with focus on US CPI report we're going to get midweek on Wednesday. But as I said, let's kick it off with, with metals and with gold. What exactly happened overnight and Yeah, a lot of questions from traders this morning given the fact that, as you can see here, we've seen quite an aggressive spike lower in the yellow metal in overnight trade. In fact, we opened in the futures market at around 1753.5, we hit a low down at 1792. And in fact, if I just put that on a 5-minute chart, so this is much more shorter time frame, you can see that that move happened very quickly and shortly after the reopening of electronic trade on Sunday night. So key things to be aware of here: when I look at a chart like that, and let's say I come in in the morning and you see a price reaction like this, there's a couple of things that instantly come to mind. The first one is, is there any major news that's come out? But if there was major news, then you would look at the other charts, of course, and there would probably be some other correlated move if it was due to a fundamental headline. Let's say something ultra bullish that's bumped gold lower, and perhaps in context that could be a comment about Powell talking about sooner tapering rather than later on the back of payrolls. Well, that equity index futures should be sharply lower, yields will be sharply higher, so T-notes should be sharply lower. So you— when I look at the correlated move, I can quite quickly see that, look, Nothing else has moved apart from gold. So that to me tells me pretty much immediately that this is a technical-based move, probably exacerbated by things like stop losses being triggered, the low liquidity. We're talking Sunday night here. Don't forget it was a Japanese market holiday as well, which is only going to exacerbate those market conditions. And when I see the price structure like this and the move happens very quickly and rapidly and you see that then recover, the recovery as well tells me a lot of information behind the fact that probably this is just a move, um, that's been driven out of those aforementioned reasons. Because otherwise, if it was fundamentals that were really initiating that, then, well, then overall that move should have sustained, not reversed two-thirds of it already. So yeah, I mean, that's kind of what happened in gold on the daily chart. I think the other part or variable that was quite important here was, was a technical one. You can see here on this rectangle, this has been a key point of inflection for the price of gold futures I'm looking at here pretty much year to date. We're going back to February, March, April price action here on the left-hand side where my mouse is. That's been a good area of support as well in late June for the bounce. And following the payroll support on Friday, we did see obviously a spike in the dollar which weighed on metal prices which moved quite steeply lower through 1,800 on Friday, but didn't actually break that key area. But in the futures market overnight, we actually opened below that key point. And so I think as well, technically you're on the wrong side now of quite a key level of support, and that would have exacerbated some of those moves and triggered some of those stops just below that level as well. So yeah, hopefully that makes a bit of sense. Um, directionally, from a trend perspective, it— I mean, it definitely is a continuation play from Friday, obviously just following up from what we had on the payrolls report. So that's not a surprise, but it's those other elements of the technicals, the liquidity, and stop-loss losses getting run that I think has just created that spike. So yeah, I don't think you need to panic just yet. Otherwise, elsewhere, the dollar index Pretty much unchanged. Dollar index actually gapped up marginally overnight but has faded that move and continues to do so just slowly through the European entrance here. So at the moment, as far as these major currency pairs are concerned, just a quick look— EURUSD just coming up then as that dollar softens a little bit, going through 7 AM here in London through the top end of that range. So worth just keeping an eye on EURUSD, any further further price recovery here, given this— the decline that we saw after payrolls on Friday. So just definitely be using those as reference points then for the move back up. So here, then the pivot level just back above, and, and going all the way back up to really broader targets for the days and weeks ahead. The R1 today, uh, pretty nice level with around those previous areas of resistance after the rundown in price that we had through— that would have been Friday's morning— and then further up from that range low and respective retest high that we had here would be other areas as well of upside resistance on any further price recovery. Cable then, pretty similar amid those, those moves as well. So just picking up a little bit of pace, you can see here as well upside resistance behind. And looking at Sterling futures, 1.3885 being the recovery that we had after the initial dollar spike on payrolls, but also those previous range lows that we were seeing through the best part of last week. Elsewhere in the crude oil market, we are just having a bit of a test down towards the lows that we did print in overnight Asia-Pac trade, which have held thus far. So it's worth keeping an eye on crude. We're already down about $1.50 at the moment. And if I put crude on a daily, there definitely is quite a key level. You can see here marked up from a trend line starting from April, retest in May, July, and to where we're at at the moment, which is also not just a trend line but horizontally on the areas of resistance, has been an area that has generally been well respected. This is around 6660. And so any further trigger on the break of that to the downside could see a decent run lower. 66 handle, and then those previous lows that were seen going back to late May, early June, and then latter part of July as well. So definitely worth keeping an eye there, but it would be contingent really on a couple of things there— the dollar firming up perhaps, or also some more apprehension about the overall global situation on COVID for sure, which we'll— we can talk about, um, in a moment. And actually, talking of that, let's talk straight about it right now. And in terms of a news perspective, so oil extending losses after weekly slump as Delta clouds outlook. So yeah, for oil, it's really a twofold thing at the moment. You've got the fast-spreading Delta variant, um, weighing generally on people's perception of global growth. And of course, this comes in the context of OPEC+, who will make monthly supply hikes now of 400,000 barrels a day from August. As per their previous dealmaking. And so you've got slowly increasing supply, which should be able to get absorbed, but it just so happens to come in the context of where people like the Chinese authorities in Wuhan have just completed testing on just over 11 million people, covering most of the city's population according to a virus control briefing on Sunday, as they continue to try to get on top of some of the latest outbreak that's been seen across various different provinces in China at the moment. And in the US, new infections numbers spiked to more than 100,000 a day on average. So still heading in the wrong direction there as well in the States. That's returning to levels of the winter surge that was seen 6 months ago. And this has created then, or resulted in, a number of financial institutions recalibrating their view about kind of Q3 Chinese growth. Specifically, Goldman Sachs cut their full-year GDP forecast for China to 8.3% from 8.6%, assuming the government will bring the outbreak under control in about a month. Barclays as well, I think, also downgraded their Q3 kind of performance for China as well. So this is all kind of in part playing into the crude oil psyche at the moment, particularly on the demand side. Overnight as well, we did have some Chinese data. Uh, we had the latest inflation readings. So this is what we're looking at here. The purple, um, line is PPI numbers. So as we're used to seeing, a big divergence between that and CPI and core CPI numbers languishing down here at the much lower levels. The PPI overnight for July year on year came in at 9%. This was against an expected 8.8%. So it's gone back up after a temporary move lower that we saw last month. Whereas Chinese CPI came in at 1% above the expected 0.8%. It was a slight moderation from 1.1% last month. Higher crude oil prices and increased demand for thermal coal as China copes with hot weather drove up prices, according to the, the statistics office in China that came out alongside those numbers last night. Separately as well, you did actually have Chinese trade numbers over the weekend. You probably saw those on Saturday. Well, if you didn't follow me on Twitter because I do tweet that type of stuff at the weekend. China's export growth unexpectedly slowed in July following outbreaks of COVID-19, as we've just discussed, while imports also lost a bit of momentum, pointing to a slowdown in the country's industrial sector. July exports in China were 19.3% year-on-year below the expected 20.8%. Other things for the weekend to be aware of: ECB's Weidmann warns inflation may pick up faster than expected. So here he is, Jens Weidmann, the head of the German Bundesbank. If you're not familiar with this chap, he's right out there, outlying hawk. And the fact that he warned that inflation in the euro area could pick up faster than expected and urged not to drag out the institution's pandemic bond buying program— in fact, I think he said PEP, which is the Pandemic Emergency Purchase Program, the additional kind of top-up QE program at the ECB. He said the P stood for pandemic, not permanent. So it goes some way to show what his thoughts are at this point in terms of what the ECB should do with wrapping up those bond purchases sooner rather than later. Comments here, I mean, these aren't really going to shift the needle on the euro this morning or European assets because that's— it's in fitting with Jens Weidmann's character. Um, the other thing is the US infrastructure bill. What's going on there? Well, still keeping an eye really on the progress. Um, the bill cleared its last procedural hurdles in the US Senate last night, setting up a vote on final passage perhaps as soon as today. So we continue to just keep an eye on that at this point in time. As far as the week is concerned, it's not that busy, to be honest. Certainly not to the same tune as last week, which was incredibly busy. So kicking things off this morning, some, some German trade data that's come out. So German exports, I can see for June, came in at 1.3% above the expected 0.4%. But otherwise, today is pretty quiet. Tuesday, you get German ZEW survey, perhaps might get a look in, but again, not really that dramatic in terms of cultivating price movement. So then really the main focal point this week is on Wednesday. And the reason for that is you get the US latest CPI report expected at 0.5% month on month compared with a gain of 0.9% of course that we saw in June. Um, roughly a third of the increase in June was attributed to price gains in used cars fueled by the supply chain bottlenecks that have hampered new vehicle production. So again, with CPI of course when that comes out, what's going to be key is looking at those pandemic idiosyncrasies to see how much of the overall contribution is to those, those types of factors to determine whether or not the underlying inflationary situation is changing. And with the general elevated nature of these numbers that we've seen dictating, then of course, whether or not Powell is right to be fairly calm in this transitory view or not. So again, the underlying details will be key, but that's probably the main highlight of the week coming then on Wednesday. Um, on Thursday, um, we look out for UK GDP. I might get a bit of a look in. It's expected to come in at 5% quarter on quarter, largely a function though of reopenings. And actually, if you think about Q3, because this is Q2 data that we're going to generally be seeing, then in actuality you could probably say that that's probably not going to create too much of a market reaction, albeit might hit the headline broader press. But the reason for that, the rationale being the fact that given the outbreak of the Delta variant, some of that reopening kind of momentum has probably faded in the last couple of months. And then looking to Friday, investors will also watch out for the rising inflation expectations as part of the sub-readings that you get as part of the University of Michigan report that's coming on Friday. This is the preliminary numbers for August. From a speaker's point of view, it's pretty light for US central bank speakers, comparatively so from last week. We've got the Atlanta Fed President Bostic and Barkin from the Richmond Reserve, Reserve Bank speaking today. Kansas City Fed Chief Esther George, a non-voter, speaks on Wednesday. I'm sure some more will be added in due course, but they're the ones we're aware of. At this point in time. And so that is it, gonna leave it there. Hopefully that was useful just to get you up to speed Monday morning. I hope you're all doing well. Any comments at all, just feel free to drop me a comment on the, on the video below. Happy to help. Otherwise, have yourself a good day and a good week ahead. Take care.
More from Anthony


Inside the Biggest Banking Stories You Need to Know This Week (Anthropic, Diageo, Private Credit)


Inside the Biggest M&A Deals You Need to Know This Week (UniCredit, GameStop, eBay, Eli Lilly)







AI Breakthrough or Hype? Anthropic’s Claude Mythos, Tim Cook Steps Down & LIV Golf Collapse