Will OPEC Listen To Biden's Request For More Oil?
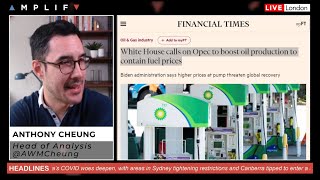
The White House is pushing OPEC to pump more oil and lower gas prices, but OPEC probably won't budge given its existing production schedule and geopolitical concerns. Markets stayed flat: Dow up 0.6%, Nasdaq down 0.2%, S&P up 0.25%. CPI showed inflation cooling monthly but staying sticky, while Fed speakers signaled a hawkish stance and possible tapering in September or October.
Chapters
Okay, very good morning, Thursday, 12th of August. Hope you are doing well. Going to talk about this article that came out in the FT in a bit more detail in a moment in regards to the White House calling on OPEC to boost oil production to contain fuel prices. So I'll discuss why they might be saying that, what it might mean, whether OPEC will listen, would it move the price of oil. So we'll get into that in a moment. Otherwise, we're also going to cover what's happened overnight in Asia. You've had a new report coming out of China in regards to a 5-year plan, in regards to regulatory crackdown, which we've been seeing obviously over the last few weeks. And then lots more Fed comments. So I'll get up to speed what exactly has been said and whether or not it changes that idea on the notion of tapering going forward. But looking at the charts this morning, pretty quiet. And we have obviously seen a momentary print of fresh record highs in the Dow and the S&P yesterday. They came off those best levels, but we did see a bit of a continuation from the prior day where the Dow was the outperformer, up around 0.6%, the Nasdaq was the underperformer, down about 0.2%, the S&P kind of mid-table, up about 0.25%. So one of the things obviously the highlight of the week really yesterday was CPI, and I think a large portion of the reaction to that was dictated by market positioning. Because if you're looking at yields over the course of really the last week, ever saw— ever since we saw that really strong services PMI in combination with those Clarida vice chair comments, yields have been tracking higher. So consequently, T-notes have been just trending downward. And so I think the market was kind of setting itself up for a potential more, if anything, upside surprise. And the numbers obviously didn't come out in that fashion. And thus what you had was a situation where T-notes and equities were moving higher yesterday with the dollar moving lower. So in terms of that kind of monetary policy play, it was almost a relief of sorts that that's not going to accelerate the taper timing. Obviously on the breakdown of CPI report, it was a little bit more interesting in regard to that whole used car truck situation, not really adding so much in regard to those pandemic kind of issues on the manufacturing supply bottlenecks, creating that more argument for transitory inflation. And so inflation still remaining pretty sticky, but evidently looking like it has peaked. And obviously the monthly rate pretty much halving from what it was in the prior month as well, creating that kind of degree of relief in the market. So yeah, that's past. Equities have kind of now steadied. T-notes are off the floor from where they were prior to the data coming out last night, roughly about 5 ticks this morning. And so I think we found a bit of a floor now for the time being to that what otherwise had been a week-long downward trend in the 10-year. Elsewhere, I was just looking at gold this morning, very much technical. It just broke out here above a very short-term trend line and also the APAC high on the range, and we just saw a little bit of a blip of a couple of dollars back to that double top that we've seen late yesterday. Nothing really significant in terms of a singular headline for gold, more of a technical play. In the FX market, it's pretty flat. Um, in fact, cable is unchanged. We have had some GDP numbers coming out this morning, manufacturing industrial output figures, business investment. Long story short, none of it has moved the market. It was all pretty much expected on the growth side, so no real reaction seen in cable on the back of that. Otherwise, oil— and that will lead us in there to have a quick chat about this FT OPEC report— oil's just run into a bit of an obstacle at around the late US and overnight Asia-Pac highs from a technical perspective. And so we've just started to drift back down, having broke through also the range low in Asian trade, um, as we move back to the $69 handle. Just below here, I'd be keeping an eye at around $68.83 in the futures for these previous areas of resistance now turned support, which would come in about 20 cents or so below the current price for the time being. Um, let's have a look at this report then. So first off, what exactly has been said and then we'll talk about what are the implications and why Biden has this particular stance. So the US administration on Wednesday urged OPEC and its allies to boost oil output to tackle rising gasoline prices that they see as a threat to the global economic recovery. So a key point here is context, and one thing to be aware of is that US petrol prices have risen alongside soaring motor fuel demand as the economy has reopened from these coronavirus-related lockdowns. Measures. In fact, petrol was selling for an average of $3.19 a gallon. Now, if you're not from the States, that probably doesn't really mean a great deal, but at $3.19 a gallon, that is up almost 50%— 5-0, 50%— from the same time last year. And one thing that's very prevalent in the US is that higher prices at the pump are never good for your political favorability. Biden will be very conscious of this, and he will also be mindful of the fact that the midterms are looming not that far off the, on the horizon. The White House spokesman later came out and said this isn't meant to be for an immediate response that they're looking for from OPEC, um, necessarily. It's meant to be a long-term engagement. So the rhetoric did get softened a touch, but to me, this is all to do with optics. Now, one of the challenges that Biden obviously faces, given what he's really stood for when he's come in as the new administration is environmental change, green energy, these types of policies. So although he probably could turn technically to US producers to fill the void, add supply to market in order to move the price back down, that's obviously going to be counterproductive for his political stance. So he needs to put the pressure and really pass the buck of accountability to the Middle East. And so for me, this is all quite a strategic attempt to really refocus and pivot the attention to the Middle East. We're requesting that they, they pump more oil. They're not listening. It's nothing to do with us. Where in actuality, Biden could actually, you know, find a solution for that. And obviously, if this was a Trump administration, it would be radically different where they'd be, as he did, allow oil producers to frack and do what otherwise are quite destabilizing environmental factors. In order to pump more oil. So for me, I don't think OPEC are going to necessarily listen. This isn't really new. US presidents, pretty much going all the way back in time, have always put pressure at certain points when prices get very high, particularly at the pump to consumer, for OPEC to flood the market with more. This obviously comes in the context of OPEC+ agreeing in July to boost output by 400,000 barrels per day a month starting in August. Until the rest of the 5.8 million barrels per day in time gets basically phased out. OPEC+ as a guide, they're due to hold their next meeting in about 2 to 3 weeks. So the first of the month in September. OPEC members, apparently this is according to sources overnight, have not collectively discussed output increases beyond that agreed 400K monthly additions following the White House statement. And I would expect that to be the case. As I said, this is Biden's administration trying to pivot the optics away from the fact that then any pain felt by the consumer, which is a real pressure point as far as petrol prices are concerned, it's the Middle East's fault. It's not our fault. Uh, I don't think it's anything more than that. And I'm not criticizing the administration. I'm just calling it as it is and the strategic rationale behind why the Biden team would be doing that. I think it's probably the only thing that they can do given the fact, as I say, they cannot turn to domestic supply to sort the issue of moving prices visibly lower. So I'd keep an eye on this. Perhaps there starts to be conversations that happen between the likes of Saudi, obviously, in the US where there's a strategic relationship. Could this impact then the sanctions and the discussions that are going on between world powers led from predominantly the US with Iran. And so there's ways and means that the US can pull the levers a little bit on the geopolitical front, obviously in the hotbed that is the Persian Gulf, in order to kind of get what they want. So yeah, it'll be interesting to watch that space and see how that really develops. But as far as oil prices are concerned, for, for right here, right now, I don't really see it has big implications at all, to be quite frank. Um, all right, quick run through some of the other headlines to be aware of. So a couple of Fed speakers from overnight. George, Esther George, is a very far-out leaning hawk, a non-voter, said the central bank needs to move ahead with reducing monetary stimulus, citing expectations for continued labor market gains. We also had Mary Daly, who is a voter, said the Fed could start dialing back its ultra-accommodative monetary stimulus by the end of the year, given the strength of the economic rebound. And then we had another hawk, Kaplan, non-voter, speak as well. Said if the economy unfolds between now and September meeting as he expects, he's in favor of announcing a plan in September meeting. Remember, that's the one that really has been penciled in because you've got Jackson Hole, which is that kind of platform for a speech from the Fed Chair Powell to really talk about potentially tapering in more detail, for it to be formalized then at the September Fed meeting. And that's important because that's when the next summary of economic projections are going to be due with the new dot plot and so forth. Um, so again, Kaplan said he's in favor of announcing a plan at September meeting and to begin tapering in October. So again, kind of conveying his outlying, more hawkish, um, nature, because that October is certainly out there with the likes of Bullard and others on the more extreme end of sooner rather than later. I wouldn't say that's the consensus at all, as far as either the market is concerned or in fact what the— where the Fed are in, in terms of the center ground at the moment and probably what Powell is thinking. So of all those 3 comments, um, uh, Daly, George, and Kaplan, it's nothing new to be quite honest. Um, so largely a reiteration and nothing that I would contemplate that's going to really impact markets today, but obviously good to know where the land lies at the moment with Fed rhetoric. Uh, this came out overnight, uh, not really too much to talk about. China has released a 5-year blueprint overnight to strengthen regulatory control over what they deem strategically important sectors. We've seen this already— technology, education. This also included healthcare as well. Um, and Beijing appeared to use the blueprint's release in a bid to provide direction on the breadth and duration of its regulatory overhaul. But analysts have still said that they do see this intensifying over time. The local market didn't really like what it heard. Shares in China are broadly lower. The Hang Seng, so the Hong Kong tech index, fell about 1% overnight. So nowhere near the size of the magnitude of the sell-offs that we were seeing, but again, just goes to show the kind of longevity of the strategic plan and change that, um, that China are trying to implement at the moment. In regard to US and China relations, the Treasury Secretary Yellen is considering a trip apparently to China in the coming months, according to sources who spoke to Bloomberg, but no decision has been made as yet. And within the kind of Asia-Pacific region, it's worth noting Australia's COVID woes have deepened. Areas in Sydney are tightening restrictions. Canberra is tipped to enter a lockdown now. And Tokyo panel of experts overnight said the COVID situation in Japan is now, quote, out of control. And it's obviously coming on the back end of the Olympics, which have just concluded in the last couple of days. Let's have a look at the calendar going forward. As far as the calendar is concerned, we've had some UK data already come out this morning. Long story short, it was effectively in line with expectations. The GDP number came in the 3-month, the 3-month figure at 4.8%. So it was bang in line. The manufacturing output a touch softer, industrial output a touch stronger. All in all, not really a great deal. If you're looking at the pound this morning, I would say much more technical. Just again broken out a bit of a short-term range that we were trading to a large degree, and so just had a bit of a run lower. When the timing of that data coming out 7 AM this morning, there was not one, you know, tick moving in cable, so it's not really based on the back of the data. Just more so a little bit of a breakout of that range low there in cable. Otherwise, today, what are we looking out for? We've got European industrial production at 10:00, not really a market mover, but just so you're aware. Then you've got weekly jobless claims expected to decrease once again to 375,000 from 385,000 coming out 1:30. And then you've got $27 billion in a 30-year bond auction coming out later on this evening. So That is it. I'll let you guys get on with the day. Uh, of course, if you're watching this on YouTube and you've got a question at all, whether can be anything at all or, or specifically on the content I've covered in the briefing, just drop me a comment below. And if you can, if you're, um, not subscribed to the channel, please do so. Love to have you in the community, and I'll catch you guys tomorrow. Thanks very much.
More from Anthony


Inside the Biggest Banking Stories You Need to Know This Week (Anthropic, Diageo, Private Credit)


Inside the Biggest M&A Deals You Need to Know This Week (UniCredit, GameStop, eBay, Eli Lilly)







AI Breakthrough or Hype? Anthropic’s Claude Mythos, Tim Cook Steps Down & LIV Golf Collapse