Yields & USD Higher Putting Stocks Back Under Pressure Despite Firmer Close On Wall Street
Treasury yields hit their highest levels since June, the dollar strengthened, and the RBNZ raised rates for the first time in seven years. Stocks face pressure despite Wall Street's modest gain, while the Nikkei fell over 1% amid Japanese political uncertainty and German factory orders dropped sharply.
Chapters
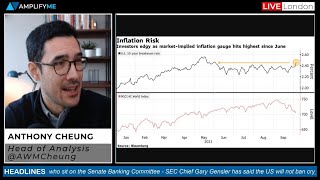
All right, very good morning. It is Wednesday the 6th of October. Hope you're doing well. Um, in terms of the briefing today, going to talk about just rising inflationary pressures, what's causing them, yields, the 10-year Treasury yield, the 30-year yield in the US both moving to their highest levels since June. As you can see here, the US 10-year breakeven rate just popping out of that range that had been constricting some of the upside yield movement over the last few months. And going back to the, the highest levels that we had really since late May, early June. And what does that generally mean for markets? Well, despite the slight reprieve that we saw in equity markets yesterday in terms of the major 3 indices— the S&P finished up around 1%, so did the Dow Jones Industrial Average, the NASDAQ was actually up about 1.25%, flipping some of that underperformance that was seen on the Monday move— but this morning we've kind of recommenced that trend a little bit, and equity index futures, despite that higher close on Wall Street, are just getting a little bit apprehensive apprehensive again about the whole yield environment and the subsequent reaction effect. We've had the RBNZ, the New Zealand Central Bank, hike rates now overnight, and the expectation of course that others are soon to be following, following these heightened inflation fears at the moment. And so equity index futures a little lower this morning, Asia stocks also generally lower. The Nikkei in Japan was down in excess of around 1.25%. Faded its opening gains and a brief foray into 28,000 territory. Auto names among the laggards amid ongoing production disruptions, with the PM Kishida's new cabinet beginning on shaky ground. Latest polls actually having had him now call for a latest election, polls have showed that his approval rating is at just 55% heading into the upcoming election. And there's a bit of context for Japanese politics, and that would be the lowest for a new leader in 13 years. So more political kind of uncertainties emanating out of Japan just weighing on their local stock market, seeing a bit of underperformance. And then this morning we've just had German factory orders come out. Just give you a bit of a flavor of what that looked like. This is the last 12 months of prints, and German factory orders this morning at 7 AM in Germany plunged 7.7% month on month in August. Of 2021, economists were only looking for a decline of around 2%, and so much lower than expected. Orders for motor vehicles— so you can see there's a very recurring theme here globally, from Japan to Germany, particularly those two countries specifically being large automotive kind of manufacturing centers. Orders for motor vehicles and parts fell 12% in Germany in August, and metal production and processing went down about 9.6%. So as I said, a little bit of an apprehensive open here for European trade. The DAX is already down about 233, the NASDAQ underperforming a little bit, down 137, and S&P down 33 at the moment. What this is translating to, again, just given some of the overall emphasis that we're seeing on the general inflation expectations moving higher, not only is this then being a bit of a negative for equities about tightening of policy, particularly more prevalent than for the likes of tech companies who are more, I guess, fragile to developments on that front. But the dollar continues to extend on gains, so the Dixie is trading higher again, adding to a lot of yesterday's ascent. And as that trades higher, it's just weighing on these major pairs here this morning. EURUSD is down 27, top left, and Cable's down 54 at the moment. And that dollar strength weighing on the yellow metal, which is inverse to the dollar, trading down $10 at the moment at around 1751. And obviously T-notes down, they've recovered a little bit, was down in excess of 10 ticks overnight. A few other things as well, just on a surface level before I really get going. Just wanted a little chat about Bitcoin. And the reason why is because we've had some latest commentary come out in regard to the SEC chief Gary Gensler, who has said the US will not ban cryptocurrencies. Now, as you can see here, this is looking at, this is looking at Bitcoin over the course of really the last 6 weeks or so. And we've had some quite seesaw commentary really, because what I've just mentioned there from Gensler, the US will not ban cryptocurrencies. He stated that the government's focus is on ensuring the industry adheres to investor and consumer protection rules, anti-money laundering regulation and tax laws. Very different from him saying you know, this is the day of reckoning, or the Coinbase spat with the SEC, which had contributed to a lot of the rationale behind some of the weight that was experienced at the beginning of the month of September and also mid-September in the likes of Bitcoin. And so we've had two quite elevated green spots here, as you can see on the most right-hand side of the chart here. And that's been— not only has Gensler kind of ruled out banning crypto, we've heard pretty much the same from the Fed Chair Jerome Powell, who said back on the 30th of September on a congressional hearing that he had, quote, no intention of barring cryptocurrencies. And I was reading a research note out of Bank of America. And again, to just add a layer of context, their strategists were talking about how more regulation— people have often thought more regulation would be negative for crypto in general, but Bank of America's take is the opposite. In fact, more regulation could be positive for the long run, at least. And once rules are established, the uncertainty then on over how to invest in crypto will be lifted. And as such, then, given it might be— there's more protection mechanisms in place, more oversight— that will mean that there's more general broad uptake and adoption of crypto in general, and therefore long term is positive. And so what does that look like this morning? Well, we looked at the Bitcoin chart obviously at the beginning of the week. and that's still looking fairly bullish at the moment. We haven't come up quite yet to test that high that was seen back on the 7th of September, looking at the Bitcoin futures here, but certainly that's what's in sight at the moment and definitely keeping an eye on that. And as we trade around the $52K mark in Bitcoin futures this morning, otherwise a few other things just to get up to speed on, on the news front. We've had the latest about Jerome Powell's reappointment I wouldn't see this as market moving for this morning, but certainly it's worth keeping up to speed with this because obviously it's a super important factor for policy setting going forward over the foreseeable future. And Powell has the backing apparently of more than half of the Republicans who sit on the banking— the Senate Banking Committee, support that could see him earn a second term to lead the central bank despite some of the sharp criticism you might have been reading from the likes of the Democrat Elizabeth Warren of late who's been very critical about loosening of regulation, his leadership, insider trading, kind of what we've been seeing most recently with Clarida at the weekend. And so there are quite a, quite a few vocal opponents, let's say, in the Democratic Party to that. Biden is yet to announce his nomination, but the White House has come out overnight and basically stated that Biden's confidence or has confidence in the Fed chair for the time being. And Powell's term obviously expires in February. So this is a decision we're expecting shortly. The growing support from the Republicans, though, going back to what this headline suggests, means that Powell may be able to get confirmed again in the 50-50 obviously split that exists at the moment in the Senate, even if a handful of Democrats oppose him anyway. So the point being then is that for now, I mean, I have been seeing quite a lot of PredictIt, which is a kind of political betting site, seeing the odds decline quite sharply for Powell over the last few weeks. And I think Leonel Brainard odds have continued to, to move higher. But honestly, I think that's just a lot of hot air and I still firmly believe that Powell will secure a second term. Um, it's just a bit of nervousness as we go into just waiting the confirmation at this point in time, which I'll see. The other thing we did have briefly mentioned, he had the RBNZ overnight. They did hike interest rates by a quarter, um, percent to 0.5%. It's the first rate hike that they've done in 7 years, if you can believe it. That was expected though, and actually the Kiwi dollar has moved lower. If anything, there was a brief blip on the initial reaction, and then it's trended lower. And of course, that's because you're trading against a strengthening counterparty in the US dollar at the moment, which is really dictating proceedings for the, the major currency pairs. One thing to be aware of is they did signal further increases will likely be needed to tame inflation, but again, that's not too dissimilar from what they've been positioning for anyway in their forward guidance. But while another rate increase in November looks firmly odds on I did see one bank commenting, one investment bank saying that risks are skewed towards something coming along to derail the RBNZ's hiking cycle before its completion. And this is something that I was talking about with the Bank of England and how aggressively the market has been priced. And I think that's been pushed out given this energy crisis we've had most recently. But, um, well, we— Piers and I talked about this on a podcast and how the market was pricing for like a Feb hike from the Bank of England, and we were going through the reasons and rationale why that's perhaps then pricing for, you know, kind of economic perfection, and that the risk then is to disruption, which could then obviously influence not just that of when the expectation of timing of hikes, but the strength of the local currency as well. And similar kind of theory holds true for New Zealand at this point in time as well. The other things to be aware of, we've had the API olive inventories come out overnight. I'm not going to dwell too much on this at the moment, but the numbers were a build of 951,000. The crude headline expectations were actually for a drawdown of 300,000. Cushing build 2 million, gasoline 3.682 million. As far as oil is trading at the moment, um, still remains very elevated this morning in the futures market. We've just popped up again in close proximity to not just the R1 at $79.88, but also the $80 psychological handle. From Monday's briefing, of course, this is the day— or weekly chart, excuse me— that we were looking at. And you can see the levels that we had marked up just working quite nicely for the time being. As you can see here, that previous inflection point that we saw through October, November of 2014, support then turned resistance on that decline that we saw through that kind of whole China hard landing fear and OPEC trying to squeeze out the competitors in the US shale industry. So that, that was that price point here of around $80, of which the market's just finding a bit of a hiatus for the moment. So quite a key technical level to watch. Certainly we're in distance of that now, so something we'll be watching out for today. Again, whether or not, just given the speed of acceleration crude oil has seen with this energy crisis at the moment and this talk of switching gas to oil and so forth and the cold winter weather looming, whether or not then we see perhaps a little bit of a consolidation at these levels, and then we look to continue to kick on, on a break of that next level. As I said, don't really see until we really get higher up to the 84 level, which would be up here. So eyes on oil as well, uh, continues to be the case. In terms of the actual calendar for today, a couple things to look out for. So we've already had the German industrial order data, as I said. And we've got eurozone retail sales, but that's largely a non-event. I wouldn't really look at that with too much interest. The main data point for this afternoon is going to be US ADP national employment. Just to give you a refresh of what that looks like over the last 12 readings, we basically had, as we know, fairly soft labor reports coming out of the US. It's been one of the, the reasons which has really despite the inflationary conditions, which has stopped the Fed from being more aggressive with their tightening of policy going forward. But this isn't really a case now, I think, of this number is going to really move the needle dramatically. I think markets are very much primed now for a November commencement of tapering in terms of that more detailed announcement. And so looking at this figure today, the ADP number is expected to come in at 428,000. So continued improvement over the last two readings that we've had at a fairly incremental value. We do have Fed's Bostic speaking later, who is a voter on the FOMC, speaking twice today at 2 and 4:30. A few other things you should be aware of as well is that the ruling Conservative Party hold the final day of their party conference, their annual conference in Manchester, um, today. And we're not expecting, according to Politico, any major announcements to come out of the PM, but the Prime Minister Boris Johnson will be giving a speech later on this afternoon. All right, that is it. If you've made it this far, thanks for sticking with me. Don't forget, if you're not already done so, please subscribe to the channel. I will be covering not only these briefings every morning, but on Friday, non-farm payrolls live on the channel. So once you subscribe, hit that bell icon and you'll get a notification as soon as that session begins on Friday. All right, take care guys and have a good session ahead.
More from Anthony


Inside the Biggest Banking Stories You Need to Know This Week (Anthropic, Diageo, Private Credit)


Inside the Biggest M&A Deals You Need to Know This Week (UniCredit, GameStop, eBay, Eli Lilly)







AI Breakthrough or Hype? Anthropic’s Claude Mythos, Tim Cook Steps Down & LIV Golf Collapse