E769: #TWiSTLive@WSGR: Balaji Srinivasan (21.co, a16z): crypto tokens, ICOs, longevity, future tech
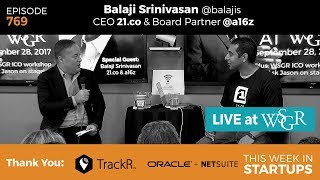
Balaji Srinivasan discusses 21.co, which pays users tokens for completing tasks, and his crypto and longevity bets at a16z. He argues aging is coordinated and potentially fixable in ten years with conventional interventions, and explains how ICOs and tokenization could undermine platform incumbents through decentralization.
This Week in Startups is brought to you by Tracker. Life is too short to spend looking for your wallet and keys. Save that precious time and get Tracker. Go to thetracker.com, enter promo code twist to get 20% off any order. And Netsuite from Oracle, the last business system you'll ever need. To get your free guide how to overcome the five obstacles to successful growth. Go to netsuite.com twist.
Hey, everybody. Hey, everybody. Welcome to another episode of this Week in Startups. We're live at Wilson Sonsini wsgr, a great law firm here in San Francisco and around the country. They're my attorneys. In fact, they do a wonderful job for us. We have an amazing show for you today. Balaji. I got that part right.
Yep.
Srinivasan. Srinivasan. Balaji. Srinivasan. I got it right is on the program. Let's give him a warm welcome. Now, you and I know each other from the Twitter. Yep. And also you have a site called 21co, 21co, which at some point somebody asked me to join, and then some people started offering me money for answering questions. So I answered a bunch of questions and I clicked donate it to black girls who code, or I'm not sure, one of the four very worthy charities there. And then I just logged into it today and it's now worth $500. That's a pretty good donation for asking whatever four or five questions. Tell everybody what 21Co is and why did you build it.
Yeah, sure. So Basically, what is 21? The simplest is you get paid to respond to emails. And if anyone here has used LinkedIn, there's an InMail feature where people can pay LinkedIn to be in your inbox, but you. You don't get paid. And senders also want to send mass messages. They can't do that. They want to send surveys and stuff like that. They can't do that. So now they can actually pay you for your time. And that might seem like a small thing, but LinkedIn InMail, even as kind of lacking as the product may be in some respects, is a 500 million a year business for LinkedIn. So there's a huge market for just getting in touch with people cold. And if you think about what's happened with email over the last maybe 10 years, all personal email has sort of been pulled out because Facebook and texting and so on and Snapchat and all intranet company email has been pulled out with Slack. Right. So the only thing that's left is really business to business email, which is commercial traffic. And commercial traffic, you'd probably want to put a price on that. And so now with digital currency, you actually can. And in fact, digital currency, one of the biggest things that led to it was hashcash, which is putting a price on email. So that's a quick version.
And so you were also a venture capitalist for a couple years at Andreessen Horowitz.
I still am. I'm part time.
So you're part time now. What did you invest in when you were at Andreessen Horowitz and what's it like to work for Mark Andreessen?
Well, what did I invest in? So let me take the first part first. So I invest in all the stuff which was the crazy stuff, pushing the future, but especially genomics, digital currency, and reinventing government, that type of stuff. And there's folks there who are very excited about SaaS businesses and the next Dropbox and so on. And that's also interesting stuff. I'd source those deals. But the kind of stuff that really got me excited was stuff that was hard technology and especially stuff in regulated industries.
Which company has objectively done the best of your investments? Which one would you say has been marked up and become the big win in your portfolio?
Soylent. Yeah. And of course, Bitcoin and Ethereum.
All right, hold on a second. Soylent is the biggest winner in your.
It's doing amazing. Yeah. Because I was.
Explain to me why this is doing so well. Because I've had it and it's absolutely horrific to drink.
Okay.
I think. Sure. But there are people who are. And I have people who work for me who drink this stuff, and they drink it exclusively. Do you drink this exclusively?
I don't, but I like it. And we get it for our office. Let me ask, actually, just a show of hands, who here has heard of Soylent?
Okay.
Okay.
So every single person. That's amazing.
That's amazing.
Number one. Right.
Right now, who here actually has bought Soylent or drank it?
That's unbelievable. For people who don't see the live audience, that was close to 50% have had it.
So that's my kind of.
How many people who drink it regularly? Let's really get to the breast hack. So it's about five people.
But here's the thing. The awesome thing about with most businesses, your problem is not indifference. Or rather, your problem is indifference. Your problem is that people just don't even care. Everybody hears about Soylent. Everyone's got an opinion on it. Oh, my God, they're destroying Food, blah, blah, blah, all that type of shit. And so they've got an opinion on it and it's polarizing. And in general, in a market, if you can polarize and 20% of people love you and they buy a subscription food subscription, where they're getting it every single week. That's amazing.
Right.
So they've got, I don't give out their numbers, let them do that. But let's say they've got a very large group of people who are basically buying subscription food. And if you look at the numbers on that, when you've got an annual.
Year, no, I heard it's nine figures in revenue. Is the word on the street that this is like essentially completely destroying it?
But let me give the highbrow pitch on it. Why is it not just slurry? Why is it not just slim, fast or whatever? Right. Basically the idea is, okay, well they went from a powder to a ready to drink and now they've got flavored ready to drink. And what's really awesome about what they did is, among other things, they flipped many of the 20th century modes on their heads. So for example, Coca Cola used to keep their recipe complete secret. It was the state secret. Part of the mystique of Coca Cola fine Soylent open source a recipe and there's a website called DIY Soylent Me where for example, women will supplement with iron and bodybuilders will put in creatine and so on and so forth. And the best of those formulations are things that then they're going to go and do in a first party way. So they kind of engage the community with it from the beginning. So that's kind of one thing. And the second is that with the soylent thing as a base, you can now add kind of additives that will make it for different kinds of groups. Right?
Yeah.
So it's this really awesome plastic kind of thing that is like nutrition 2.0. And really what it's about is like transhumanism and stuff like that. Not like, not something.
What does that mean, transhumanism.
What does transhumanism mean? It means human 2.0. Right.
Okay. So optimizing to be better humans.
Yeah, I mean like in the sense of, you know, what is healthcare? Right. Like, you know, healthcare means, you know, okay, let's add a few years to somebody's life. That's how often you'll measure healthcare outcomes.
Right.
When you go and compare, let's say Sweden to Ukraine, you'll say, okay, they've got larger life expectancy but we're just, you know, we're not really trying to punch through. We're just saying, okay, let's add a year or two. Right. But actually, if you look at the, you know, biology of aging, it looks like a coordinated process, right. Without getting into all the details of it, it's something where it's not something that happens by accident. In the same way that your maturation from a child to an adult is not an accidental process, your maturation from an adult into an old person is something which is actually coordinated. So if you could stop that, you could actually extend life. That's the kind of thing that transhumanists think about.
Got it. Are you one of these transhumanists?
Yeah, I'd say so, yeah.
Do you want to live forever?
That'd be ideal. Yeah, sure.
Is it really? Do you really want to live forever?
Well, there's a lot of math to do.
Yeah.
Yeah.
So for that reason alone, well, yeah. Well, how do you think that. How old are you?
Me? I'm 37.
37, okay. How many years do you think we're going to add to human life spans on average here in the United States due to technology in the next 30, 40 years? In other words, when you hit 70 or 75 and you're supposed to die, how many more years do you think you're going to get?
So let me answer the question slightly differently. If you know what most people have as a mental model is they think that aging is something where it happens because random accidents happen to you. Oh, I got hit by this rock and so my arm doesn't work as well and various accidents happen and function degrades and then you finally die.
Right.
That can't actually be what happens because if so you'd have a so called hazard rate like distribution, and there'd be some humans who'd live for 1,000 years because they would never actually encounter those accidents. We see that with manufactured objects, with cars that don't have any accidents that just function for a very long time. So it's actually something where there's, it looks like there's a sharp cut point, like actual biological switches that trigger, that kill us at around like 120 is like the maximum age. And what's interesting is most people don't know this because they don't like follow the literature obsessively. But we've been able to extend the lifespan of mice. We've been able to do this. Scientists have all this stuff, breakthroughs. I could show you a whole slide Deck where there's a recent drug where a side effect of it was it made the man look about 15 years younger. Like it made his hair turn from gray to like brown. Right. And so my answer to your question is there's several different forms of, you know, molecular issues that cause so called senescence, like aging. Frankly, I think we could probably get to unlimited life. Now, will that be something that you could do for existing humans or would you need to actually do something in the germline for the next generation? I don't know the answer to that. I do know that the technology is way more advanced than people think, but it's all stuck in the research lab right now.
So how many years you think we're going to add? Like if you had to just ballpark it, if we, if we were both supposed to die at 75 or whatever, you think we could add 10 years by the time we hit it?
I think probably, yeah. I mean, like there's stuff that's out there right now. I mean, this is a whole separate kind of conversation. But yeah, I think you could probably add definitely 10 years. That's within the scope of what I call conventional medical kind of interventions. That's within the scope of the life expectancy boost that we've seen over the 20th century. But the most interesting thing is to think of aging as actually the ultimate disease. Right, Right. And one way of thinking about it is, and this is a sentence where you can go and you can attack or analyze each individual clause, but if the purpose of technology is to reduce scarcity, then the ultimate purpose of technology is to reduce or eliminate mortality. And let me actually, you know, kind of break that down. Right. So the first part, if the purpose of technology is to reduce scarcity, so how do we market a technology? We say it's cheaper, we say it's better, we say it's faster.
Right.
And cheaper means, okay, it costs you less money, which means it takes less human life in order to go and buy this thing. And so essentially human life is that ruler by which you measure the cost of any new technology. Cheaper, better, faster. Right. And so the purpose of technology is to reduce scarcity, but the ultimate form of scarcity is our limited human lifespans. If you can increase the human lifespan, that is the ultimate wealth creating thing for everything else downstream.
Okay, when we get back from this quick break, we'll pivot and we'll pivot the discussion from living forever to talking about ICOs. And if this whole thing is the future of finance and venture capital, or if it's colossal scam like the dot com bust or if it's both, when we get back on this week in startups. Okay everybody, let me tell you about a product I love. It's called Tracker T R A C K R. Tracker without the E trackr is an amazing little product that you can attach to a keyring, attach to your phone, put in your wallet anything that you lose regularly. Know I, Jason Calacanis, am on top of everything I do and I never lose anything, but once in a while I do. And one of the things I'm always misplacing is keys to cars. And my wife also happens to suffer from this. And we're constantly trying to find who was the last person with the Tesla key. Well, when I got tracker I took all of our Tesla key fobs, I took all of the different the minivans key fob and I put trackers on them. Now when something's wrong, I can easily take out an app and bing beep beep boop. Find the keys. It makes a nice little beep. It tells me where it is. So when you misplace an item and you have that tracker Pixel. Pixel is their new product attached. You can use your smartphone and a 90 decibel alert will help you find it in seconds. I'm thinking about putting these on the remote controls because my daughter, now my seven year old, is constantly leaving the remote control in some weird place. She literally took the remote control into the kitchen and put it in a drawer. She put the remote control in her bed. You know these things happen. So when you misplace an item, you get that 90 decibel alert and it's got a powerful LED on it and you can find anything you want in the dark. If you lose your phone, just press a button on the tracker Pixel and your phone rings, even if it's on silent. So it's reversible too. This is amazing. Every tracker user is part of the largest tracker crowd locate network in the world. So you can locate your items anywhere, even if it's miles away. The tracker 30 day money back guarantee equals that you will have nothing to lose. So here is your call to action. Go to thetracker.com twist that's T-H-E T R A C K R.com thetracker.com no E on that second E in Tracker Twist and you'll get 20% off any order. They have a money day guarantee, 30 day money day guarantee. Go ahead and get it. Thetracker.com twist thetracker.com twist. You will love this product. And I have been a fan of this product for a long time and this new Tracker Pixel is their best product ever. As the years have gone on, they've made their products better and better. And Tracker Pixel is, I think, the holy grail of losing items. It works perfectly. I love is great. It's been eight years since they started working on this problem and I gotta tell you, right now, I think that they have solved it effortlessly. It's so easy to set up. I set it up in literally seconds. I was so impressed. To the team over at Tracker, Congratulations. You have figured it out. I know it was a long, arduous trail to figure out how to make all of us have instant recall of where we left our car keys, our wallet, and all these things. It is so delightful to see a startup figure it out. And the Tracker Pixel is so just from me to you, the team over at Tracker, I just want to say congratulations. I know you've been working on it for a long time and I am really, genuinely impressed with this latest version. Tracker Pixel is amazing. TheTracker.com/TheTracker.com/TheTracker.Com twist okay, let's get back to this amazing episode. Hey, everybody. Welcome back to this week in startups. I'm your host, Jason Galacanis and you can follow me, Jason, on the Twitter and you can follow the podcast this week in startups, wistartups. And if you love the podcast, go ahead and give it a five star rating on itunes. If you don't like it, email jackieaunch co and she will do a better job. My guest today, Balaji, is B A L A J I S on the Twitter. You love the Twitter.
I used to love the Twitter.
You used to love the Twitter? Yes, you and I used to get into it a little while on the Twitter a little bit now and again. It's basically me and all the Andreessen Horowitz partners get into it a little bit. I don't know what it is with me and the Andreessen Horowitz partners.
It's not you. And it's just what Twitter is. Twitter is about gang warfare. So just you messed with the wrong gang.
Exactly. I always feel like when I'm getting into it, like all of a sudden it's like, oh, here's another Andreessen Horowitz partner. Here's another. And all of a sudden I'm arguing with three Andreessen Horowitz partners and then Mark blocks me. Then he unblocks me. It's very weird. So that was the question that you punted on before. Mark Andreessen is kind of a weird cat. What's it like working for him?
I love Mark. I love him, too.
But he's a little bit weird, right?
Well, I'm weird also, but basically, like, I mean, I'm kind of a hybrid of Mark and Ben because I listen to as much rap as Ben, but I'm also like a, you know, fundamentally a tech CTO ish kind of guy. Like Mark got him.
What's it like working for him?
What's it like working for him? I mean, he's one of the few people I can talk to where I can speak as quickly as I can and he can speak as quickly back. So we can just like, kind of upload information. Yeah.
How do you make decisions on what to invest in at Andreessen Horowitz? Is it consensus? Is it contentious? Equals consensus. A lot of different funds have different approaches to this. So when you say, hey, I want to invest in a powdered beverage, that'll make you live forever.
Right.
Well, what's the conversation like? How do you get consensus for something as wacky as that?
Well, obviously, you have to present your diligence and so on. And, you know, I'm not saying, by the way, that Soylent will make you live forever. I'm saying it's a step on. I'm joking. I'm joking. But how are investments made so general partners can invest on their own if they have conviction? And in fact, not just us, but many other firms have found that the best deals are often the most polarizing deals as well as the worst deals. But since VC is very upside driven, you can only lose all your money, but you can make 10 or 100x. So typically, polarizing deals are actually. It's good that one person can have the minority report and say, boom, I really want to invest in this. Right. With that said, there's a lot of discussion prior to somebody pulling out that card and saying, okay, I want to invest in this.
So when Andreessen Horowitz came into the space, they said, hey, we're going to disrupt things a little bit. We're going to hire huge staff, and we're going to have a bunch of support services that other VCs don't have. So if you compare a benchmark, which is just whatever, six partners, no support, no hr. Now a lot of lawyers. What's that?
Now a lot of lawyers.
Now a lot of lawyers. Yeah, well played. And then you have Andreessen Horowitz with a bunch of services. I remember when you guys came into space, a lot of the VCs were talking smack about you were like, don't work with you guys, etc. And then you guys were paying really high prices for the series Bs and you became known for overpaying or paying a lot. Tell me about that strategy of maybe investing larger amounts of money than other firms were comfortable with. And has that paid off? And have other firms followed you? Or is that something you guys have reconsidered? Because there were some firms that I think got a little bit ahead of themselves, maybe had too much money. Did you learn something from that as a firm? It's the only critique I've ever heard.
Yeah, I mean, I think the firm has done pretty well and it's something where early in Slack and early in Airbnb and all this other great stuff. So ultimately the price you pay is market determined and judged by your returns.
Yeah, but people have. The critique has been that you guys have come over the top and paid very high prices and put in very large amounts of money. Is that critique valid or not? And not just sour grapes by the other VC firms who weren't willing to pay the price that you were.
I mean, like an international relations here. Whenever you have like a rising power, then like, you know, the incumbents don't usually like that new rising power and they can manufacture or sometimes, you know, come with genuine grievances against the interloper. But now I think we're really kind of in the club. So I mean, also that was before I joined the firm. So.
What is your take on the current state of venture with venture capitalists now that you're. Because now you're essentially a full time entrepreneur, part time and just part time being a venture capitalist. So you're back on the other side of the table. What's your take on, independent of Indris and Horowitz, most VC firms saying, hey, we're going to move down to what most people would have considered the Series B back in the day 10 years ago, which is show us significant traction and we'll give you $20 million for 20% of the company or something in that range, as opposed to being the risk taking, hey, we're going to do Series A. There was a moment in time where somebody, I don't know if it was you or some partner said, hey, we really don't do Series A's anymore. And then Mark sort of backtracked those comments a bit. But the truth is, VCs, Andreessenhorts and others are taking, are moving a little further downstream. We'd all agree in doing bigger rounds later with more traction. What's your feeling on that trend? And maybe the emerging angel class, angel list syndicates and taking up the early stage.
Well, so I actually, I mean, I think that was like maybe a live issue a couple of years ago, but I don't think about that as much because I think that coins and tokens are a structural change in the whole industry. So that will affect all of what you're talking about because just a gigantic amount of capital has been unlocked. And so I think. Are VCs moving a little bit down? Yeah, because, you know, you have angels and super angels and so on. People can get financed earlier and they have, you know, lower capital cost to get to market and so on. So yes, VCs probably are like somewhat moving up the stack, but they certainly still do A's. But I think that the single biggest thing to ever happen to venture capital is, you know, the token launch, the, you know, the ICO and whatnot. And I think that over the next five to 10 years, not without bubbles and reversals and regulatory issues and whatnot, but over the next five to 10 years, it's going to result in a very rapid decentralization of technology outside of Silicon Valley. And the reason for that is one of the biggest kind of appreciated drivers of why entrepreneurs come to Silicon Valley is because VCs don't want to get on planes too much. The reason for this is because if you've got 10 board seats and you've got a company in Japan and you've got a company in Israel and you've got a company in India and so on, you're basically spending your entire life on planes.
It's exhausting.
It's exhausting.
That's right.
So because of that, if you're an entrepreneur in Israel or in India or what have you, you've got essentially two options. Number one, relocate your company to the Bay Area and then, quote, build a relationship with the VC or angel or whatever over time. Right. Or number two, parachute in and try to build a relationship in sort of in an organic way. And sometimes that kind of works. If you've got a really good company, you spend like three weeks on Sandhill Road, you, you're slacking back and forth with your team. But it's a real pain and an exceptional company can pull that off. And sometimes VCs do invest abroad. But what happens usually is the gravitational well of funding pulls you in for the A round, and then the guy gets you in your capitol for the B round and the C round. So they can all just kind of drive around. And it's not like a selfish thing, it's just like a logistical thing. Who wants to be in 12 countries for 12 different board seats? But what's going to change now is everything else has already been put in the cloud. Slack's in the cloud and you've got Google Docs has been there for a while. Google Drive is there, all these other tools, right? And now the last piece is investment and funding is in the cloud. And so now that means that folks anywhere in the world who have a good idea can get set up. And anybody in the world who has a good idea can actually also buy some tokens, even with $10 if you're in the middle of Mongolia. Right? So it's going to massively change the entire industry over the next decade.
Okay, let's talk a little bit about what's happened to date. I've been looking at these ICOs. Most of them are by unknown founders who have never built a company. Most of them have built a white paper, and in some cases they're raising 20, 30, $200 million based on a white paper. Is this wise to give people who've never had a successful company 30 to $200 million in one chunk for writing a white paper?
Yeah. So, good question. My short answer to that is certainly, I would not recommend every or even Most or even 90% of the ICOs that are out there today. But I would also say that in 2014, there was a guy who had never run a company before who took in $18 million in crowdfunding, which was one of the highest crowdfunds of all time. That was Ethereum, which has turned out to be probably the best startup investment in ever, right? Better than Dropbox, better than Airbnb, better than Uber. Right. Better than Stripe. Just in terms of from where it started to where it got to and how liquid it was during that time period is probably the best startup investment ever, right? That was considered a gigantically huge crowdfunding in 2014. Like, way, way, way, way beyond progress. It was just a white paper, all that type of stuff. They had no track record, to my knowledge. I don't think any VCs bought in as VCs. Like a lot of us bought in as individuals, but it wasn't like something that we went and marketed and they killed it. Right? And so because of that, I'M loathe to say, oh, somebody without a track record is bad, without white paper is bad. Now, are many of these guys going to be the next Ethereum? No, most of them will not be. Right.
Well, not being bad, but maybe the funding would be better if it was staged or tranched or tranched or something like that. It just seems very reminiscent of what we saw in the dot com bubble where people raised SPACs or other incubator like devices of 100 or 200 million without any product. And a lot of that was overfunding that eventually resulted in complete and utter cratering of the industry. Do you see that happening here? What happens if, as you said, 90% of these ICOs might be bad? If those 90% go to zero, which I think is a likely scenario, what happens? Exactly what would happen? Because is this all funny money? Because people don't know whose money this is, do they?
Yeah. So a couple of thoughts on that. So first is, with even the dot com bubble, one of the theses that we have at A6 and Z, which we've talked about publicly, is a whole Carlotta Perez Gartner hype cycle kind of thesis. And so essentially the concept here is that any technology will have this initial spike of inflated expectations. Everyone's super excited about it, and then it drops off as people realize, oh, it can't do everything in slice bread, right. And then that culls and lots of bankruptcies happen, consolidation happens, and then those survivors who are hardy enough to make it through, you get to kind of the peak over here, right? And you went through that with Silicon Alley reporter and all this stuff, right? And you know, the fact that you could survive and make it through. You actually had a great essay on this, you know, a few years ago about like how the second time and the third time you're in that trough, you're like, let's do this. Right.
But the first time, well, it's kind of exciting, right?
It's kind of exciting.
You know, you expect it.
Yeah.
And you're like, oh, there's, it's very easy to hire people when everybody is leaving and it's not tourist season. Like the hotels are cheap and there's no, like, it's easy to get a reservation and there's no lines at the great, you know, restaurants.
That's right. And it's also an iterated game where a lot of the folks in the industry have been around for a while and they recognize who had the grit to go through the hard times. And those are the folks who are going to back in the good times.
Right.
It's not 100% of the reputation system, Silicon Valley, but it works reasonably well, I think.
So we're right at that peak right now.
I mean, yeah, maybe. I'm not sure. It's hard to call the top on something. Right. This could be like, who knows, there could be two more, three more years like this. Right, right. With that said, I would say the good thing about crypto is this is not the first crypto bubble. This is probably the fourth. Right. There was the one in 2011, then there was one in early 2013, late 2013, and the late 2013 one that was a real bear, where most of the folks who are in the space now are mostly like, I think the better coins and tokens and so on that you're seeing are, are from folks like Brave and Blockstack and Civic and so on. Who are all players. During that initial 2013 to 2017 bubble, which was pretty brutal, it went down to $176 in early 2015, a lot of folks lost their shirts and died. So the answer is, is it potentially bublish? Yeah, there's definitely bublish aspects, but a lot of the folks in the industry are survivors of that and very few technologies have been built without bublish periods.
Okay, when we get back from this final break, I want you to give advice to people who are in the room who have startups or ideas of if they should do an ICO or if they shouldn't do an ico. In other words, who should be considering doing this and who shouldn't. And then I personally want to ask you, as somebody who's a fund manager and investor in 150 companies, should my next fund, if I were to create one, be token based, or should I just go with classic LPs? When we get back on this Week in startups. Hey, everybody, let's take a minute to thank NetSuite Plus Oracle for partnering on this Week in Startups. And let me ask you this. How many times have you asked these questions as a business leader? Why does it take accounting so long to close the books? And why can't I get my sales numbers in real time? Did we beat our revenue goal or did we lose money? What the heck is going on? Are we being audited? When you start asking these questions, it means that you've outgrown your business management software. And QuickBooks and spreadsheets are fine when you're a bootstrap startup and when you're just getting started, but you can't have mistakes and delays and you can't not be able to get fast answers when your startup grows up and becomes a big, real sustainable business. So the number one business management solution, of course, for growing companies is NetSuite from Oracle. See what's going on with your business in real time by using NetSuite from Oracle. Revenues, expenses, customers, orders, even your HR department. You can run your business from your dashboard on your phone and know what's going on as the CEO, the president, whatever, anybody on the management team, the board. Their current clients include all the great technology companies, you know, including people like Locallytics, GitHub and PlanGrid. Those are startups that got really big and they needed to have this industrial strength business management software. 88% of Bessemer's Nextcloud unicorns use NetSuite from Oracle. 29% of recent software industry IPOs use NetSuite from Oracle. And 22 of the Wall Street Journal billion dollar startups use NetSuite from Oracle. You're getting the trend here. Thousands of companies across America use NetSuite from Oracle. So here's your call to action. Go to netsuite.com/netsuite.com/ and you will get your free guide called Overcoming youg 5 Obstacles to Growth. That's netsuite.com/netsuite.com/ Please, please go there and get your free guide to find out how NetSuite can simplify your life. Just go to netsuite.com/netsuite S U I T E.com/ all right, thanks a lot, NetSuite. I really appreciate it. Let's get back to this amazing program. All right, welcome back to this week in Stardust. My guest biology is here. You can follow him on the Twitter B A L A J I S. You're good on Twitter. And Mark stopped tweeting?
Yep.
Why did he stop tweeting?
Because the downside is greater than the upside.
Okay. Yeah. So after that comment about India, he was like, it wasn't right.
After that was. Yeah, no, it was like, like a few months later. I mean, the thing is that you know what Twitter is right now? Like, there's only two models for social network governance. There's the Soviet Union and Somalia, exemplified by Facebook and Twitter, respectively.
Right.
And you know, Twitter is basically just people with guns roaming around trying to kill each other. Right?
Somalia.
Yeah. I mean, like, I'm not seeing.
That's why I feel most at home there. Right. I kind of feel like I would have done well in Somalia, if I had been born.
I mean, Somalia is a great anarcho capitalist example in many ways, but it's also kind of a dangerous, you know, place to live.
Yeah, I'm the captain.
I like Rwanda much better, actually, under Kagame. He's done a great job. Go ahead.
I just said I'm the captain now.
Oh, yeah, yeah, yeah, exactly.
Right. Wait, wait. And then what was Facebook?
Soviet Union.
Soviet Union. Right, right. What do you think of this whole Facebook thing? This seems to me to be the craziest thing that's ever happened.
Which thing?
Well, with the Russia thing, they ran Russian ads. Zuckerberg said there's no way this could have impacted anything. Then he did a public mia coppa and said, we're going to do better. But he cashed $100,000 in ads for the Russians to put up anti LGBT and anti whatever ads. And it's pretty clear that Facebook is very influential as a platform and he's now backtracked. How do you think Facebook could impact an election? First and two, if it did impact the election, let's say if it's greater than 100,000 in ad buys and it did impact the election and that can be proven, what should happen?
Well, I mean, you know, does television impact the election? Does radio? Does the Internet. Yes. Facebook impacts the election when 2 billion people have it, yes. It's a big deal. Right.
Okay. So we all agree. Totally impacts the election. Great.
Yeah.
I mean, despite Zuckerberg saying there's no way it could have impacted the election.
I mean, I think so. I didn't look at his. I don't want to parse his specific statement.
Well, he backtracked it anyway. Yeah, but he said he thought it was ridiculous, I think was the quote, that an election could be swung?
Well, I think. I don't know what his exact quotas, and I'd have to go and look at it. My understanding is that he was saying that that ad buy was too small to have swung the election. It was before the ad buy, but yeah. Okay, fine, fine. So I think the reason he might say that is $100,000 is absolutely nothing to Facebook. Sure. I mean, that's. I don't know what their revenue is like, but that's gotta be like per second or per minute or something like that. Right.
So what should happen if it did? Let's just say they used micro targeting to target African Americans in swing states who came out for Obama and convince them to not vote for Hillary or influence him in that way. And the money came from the Russians and the data was stolen. What should happen? What is Facebook's responsibility in your mind?
Well, so I've not been following this one very closely. I've tried to tune out of all the political stuff, actually. But basically my understanding is that some of the money actually also went to like Jill Stein and Bernie Sanders ads as well as Trump ads. Right. So it's just like a cross spectrum anti establishment kind of thing. And you know, what should be done? I don't know. We're in terra incognita right now. Right. You know, I'm not sure there's any like, rules against it. And certainly, frankly, the American government does a ton of lobbying overseas for, you know, when there's elections that are happening over there, there's not a country around the world that hasn't had the State department come in and do some stuff.
Right.
Other than maybe China. And so. So because of that, I think we should look at, you know. Yes. Like is, are any laws violated? Sure, that's something to look at. But also be conscious of the fact that the US Is done a lot of stuff worldwide. It's not necessarily always the most symmetric actor.
Do you think Facebook should be regulated in some way?
It is regulated already in many ways. Like the FTC keeps fining it and.
So, yeah, they got a 20 year fine and audit.
Yeah, yeah.
Right, right. Do you think there should be some additional regulation around this type of issue? In other words, should all political ads be transparent? Should their the targeting be listed underneath the ad on the top level? Would there be something that would make you more comfortable with it if in fact there was some shenanigans going on?
Yeah. So I'm simple, I'm sympathetic to like the public choice theory of economics, which is kind of, you know, Nobel prizes are being awarded for it, which essentially states that if the goal is to hamper or constrain a company, then regulation actually usually accomplishes the opposite effect, which is it actually locks in an incumbent. And so many incumbents actually, when you get, you know, let alone the scale of a Facebook, but, you know, a Pfizer or a Roche or what have you, they actually unbalanced, typically welcome regulation because what it usually results in are compliance costs for all their competitors. And actually it locks in the current status quo.
Fascinating.
Yeah. So if you want to harm or reduce the impact of a large company, I think the goal is actually to allow startups and other things to attack it. And one of the tools, just actually returning to the token for a second, we've Got a completely new tool with which to break network effects and to bootstrap two sided marketplaces, which is the token. Right. And the reason is that basically, you know, one thing people have talked about for a very long time is, okay, Facebook's a $500 billion company. What if it could have split half of its equity with its users?
Right.
That would basically be 250 billion divided by 2 billion users. So $125 for every man, woman and child on Facebook, Actually quite a lot of money. But in practice, you would not do it completely uniformly. Instead you'd have like a function that kind of dropped off like this, where the first 10,000, 100,000 and 1 million users would get more than the 1 billionth user because they contributed more to the network effect.
Right.
So with tokenization, this is possible and it's actually something where you wouldn't do with equity because equity is problematic. But with a token, you can have folks participate in network value creation and something that's like, this is basically what we're doing with 21Co, right?
If I answer a question, I earn some coins and I can spend them on other questions.
Yes. But even more than that, so if I can bring up the website for a second. Yeah. So let me see if I can.
Do a little demo here and then we will answer the question of who should ICO and who shouldn't.
Yes.
Which is a super important one, I think, because I'm getting asked by all my startups, should I do an ico? And I have no idea what to ask them.
Absolutely. So let me just explain at least what we're doing. So we're actually doing a token launch without an ico. And the way it works is basically as follows. So we call this like the first token based social network. And what exactly does that mean? Right, so rather up to this point, with an ico, you've got in tokens for capital, but we have tokens for labor. And every time the user base doubles the amount of tokens that you get for signing up halves. So there's a strong incentive to be an early adopter and also to invite all your friends because you get a portion, 25% of all the tokens that they earn. So what's cool about this is basically it's a bootstrapping mechanism that just strongly incentivizes early adopters, so you get hundreds of thousands, millions of folks onto the network. And then we know already that if you get to many millions of users, you can easily monetize a social network. So It's a new way to bootstrap networks. It's not an ico, but if it does work, I think it's going to be widely imitated by like mid next year or thereabouts. So this is kind of what we're doing with 21.
Yeah, it's a great idea. It makes total sense to me that the first million people, the first hundred thousand people who invite Everybody, should get 10 tokens.
Exactly.
The next million should get one token and the next 10 million should get a tenth of a token.
Very much like that.
If I write a post that gets 100 likes and shares, maybe I get a hundredth of a token for every share because I created something valuable in the network.
Yeah. So the one thing that we're doing that's slightly different than that. So when you're generating content, you're generating what you want to generate, and people have talked about being paid for content, but I think that a different way of thinking about it is if somebody issues you a task, they already value the labor they're asking you to do. So they direct your labor in a useful way rather than generating content and hoping that someone will pay for it. Instead, somebody sends you a task that you already know they're going to pay for it.
So like Amazon Turk, but for tokens.
Exactly. So one way of thinking about this is it's sort of like LinkedIn in the sense that you can target individuals. Mechanical Turk in that you can give them tasks and digital currencies, you can pay them for completing tasks.
Or Quora. So it could be just for a question like you currently have, you could. Quora. Is Quora going to do their own tokens?
You think they could?
What do you think? You probably have inside information. Are they going to do it, you think? Give me a percentage chance.
Percentage chance. Well, big fan of Adam. I actually don't know what his plans are on this. Give me pretty a percent chance. I think it's hard to tokenize a very large existing network because when folks have tried to bolt on economics onto things where they've spent a lot of time optimizing all the social stuff, it tends to make people mad. And so it's sometimes easier to do it as a separate network.
Yeah, it's definitely when you introduce it, you get all kinds of perverse effects, like people creating fake accounts which you'll have to deal with.
Exactly. That's right. So we verify all users and so on. So we actually, because we built this as a commercial network rather than really a social network from the beginning. One of my theses is of Facebook, Twitter and LinkedIn. LinkedIn has the least engagement of users on there. And the reason I would say that is the case is that it's really a commercial network, not a social network. What you want are for the edges to have some monetary value associated with them. But before digital currency, that wasn't possible. So we'll see if this one works.
Where it's buffering the ground up. I go to my inbox on LinkedIn. I have 18,000 connections, and I don't think I've ever gotten any quality anything that benefited me.
That's right.
So I literally have given up looking at it, and I would much rather just literally have it be sorted by how many bitcoins they would allow me to donate to charity.
Exactly.
And if it was sorted, like when I get a thing from 21, I'm just like, oh, I can answer a question. And $20 goes to black girls who code.
Fine.
Sounds good to me because I can write a sentence or three and five minutes. I'm a writer, so it's great for me to put some goodwill out into the world. Let's talk about ICOs and who should do them and who shouldn't. Because it seems to me that people who are buying ICOs are buying them to speculate. You would agree with this?
A lot of them, yes. Yeah.
And so if people are buying them to speculate, but they're what people are calling utility tokens, that, to me, leads to a little bit of confusion because the purchasers want the tokens to go up in value, but the person selling them is saying, you're not buying these for the appreciation, you're buying them because they'll be useful to you on an API basis. Is this some inherent conflict right now or discomfort in the space that needs to be clarified?
Well, I think.
Because the SEC has started to talk about this.
Right? Yeah, yeah, educate us. I think, for example, if you go and buy a house, that house can appreciate in value, but you can also use it. If you go and buy a domain, a domain, you can use it, but it can also appreciate in value. Not everything that you buy that has a use case that appreciates the value is necessarily a security. There are examples that are not.
They could be both.
They could be both.
Like the house.
Right? Like the house.
Right.
And so I think a really important question is, is there genuine utility for the token or is it like kind of like a bolt on. Right. And we're going to see how wide a class of things can be kind of tokenized in a way where there's genuine utility. With that said, I think there's definitely some coins out there and tokens out there that have genuine utility. For example, filecoin. Right. Where what is a token? Well, you are basically buying a hard drive space on 1,000 remote machines to store one megabyte of stuff that's clearly utility.
Right?
Yeah. Ethereum.
Is that idea going to work, Falcon?
Yeah, I think definitely.
Why would people use that as opposed to the just plummeting cost of S3 it seems to me.
Super good question.
Yeah, like this is like not going to work because if I have a serious use for storage, it's so de minimis the cost at S3 that why would I want it spread across a bunch of people's different machines? I don't get it.
Excellent question. And so the short answer is censorship, resistance. But let me give a longer answer, right, which is if everyone's followed the news, you've probably seen that like a week or so ago, the Spanish government went and raided the cat registry and shut down 100,000 cat domains for Catalonia. Right. Because Catalonia was going to have an independence movement. So all these people were caught in the crossfire where their domains were either shut down or seized or what have you. And this is something where essentially governments started overstepping. Where previously there had been Marais that had stopped them from being so intrusive, at least in the West, China had been intrusive for a while, but in the west there have been these Marais that stop people from like messing with DNS and you know, stuff that was previously considered like demilitarized zone.
Right? Yeah.
Now that's actually happening. It's happening very routinely. The seal has been broken and I think you're going to see that a lot more. And that every, every time something like that happens, it's a huge subsidy for every person, crypto person, who's working on decentralized systems. Because the decentralized systems, no one can take it away from you.
Right.
They can't take away your domain, whether it's Blockstack or DNS.
So in a way, what we're seeing with these, the decentralized nature of crypto, ICOs, blockchain, et cetera, in a way, it's being bolstered by the fact that 20 years into the commercial Internet or so, people are starting to get greedy and governments are trying to stop it. In fact, if you look at just domain registrations, we had whatever the white supremacist group was, I Forgot their name, but they kept having their domain name registration yanked out. Yanked. And I can understand that if I'm the CEO of GoDaddy. Do I really want Stormfront on as resolving through myself, or do I want to be routing their DNS if I'm dying? Like, it doesn't feel very good to be routing the DNS of a bunch of white supremacists. But should anyone be able. Should the domain system be independent and the DNS system be independent of that kind of censorship? What's your position on it? I find it a very confounding proposition right now for me, as someone who's a free speech advocate. Right. I'd like to see these maniacs. I like the fact that the maniacs publish themselves because at least we know where they are.
I think, you know, like, you know, I definitely agree that with freedom of speech. I am against censorship. And the reason is because I think if you look at history, censorship of that guy will often be turned back on you.
Right.
Like, you know, for example, you know, the House UN American Activities Commission, which is famous for McCarthy and investigations of Communists, actually started as something that was going after Nazis.
Right.
Most people don't know that. Right. So it started as something that was going after UN American Nazis and was turned on going after UN American Communists. So if you start by going after Nazis, it can get turned. Right. That's kind of.
You can wind up in Hollywood.
Yeah, exactly.
Getting screenplay writers.
Screenplay writers who are writing things to.
Mock you as government officials.
Exactly. Right. So that's kind of one aspect of it, the enlightened self interest aspect. But the second is that it's also, I think, going to become less and less feasible because of encryption, because of decentralization, because of all these technologies that are rolling out. It's not just end to end encryption on WhatsApp. It is the fact that we're building an entire parallel tech stack. So you won't be able to see somebody's domain and you won't be able to see somebody's money, and you won't be able to see somebody's files and you won't be able to seize their followers and so on and so forth. Right. All that stuff. I mean, why does Twitter have actually a great deal of power? You know, it is because if they want to, they can block your account and then they can disintermediate you from all your followers.
Right. Whereas they did this to Milo Yiannopoulos and other troll harassers.
That's right. And so far it's being applied to folks who are, you know, like unpopular and negative and, you know, you know, bad influences. But that's a very powerful kind of power to take somebody away from the audience that they've built. And, you know, it's something where. I'm not sure we should entrust an entity with that. It's something where would you want to build up a following of a million people and then have that yanked away from you just on a whim. Right. Because you got unpopular one day. Right, right.
And then the counter argument is, well, if I'm a private company like Twitter, I just don't want to deal with someone like Milo, or Milo, however you pronounce it, Milo, just harassing people randomly, especially if they're African American women's, and calling them.
It's within Twitter's rights to do it.
Horrible names and doing crazy name calling.
Absolutely within Twitter's rights to do it. And I completely understand why they did it, and I understand Jack is under pressures and so on to that. And who would want to support Milo versus the woman he's harassing? Nevertheless, just like with the domains, it's a precedent that it sets where that's a sword that can be turned on you. And I'll give a good example of it where there was a statistics professor a few weeks ago whose account was just banned by Google. All his blog, all his access, all this stuff was gone.
And.
And this was just a normal guy. He happened to have done some political blogging. And so Google's filters picked him up as being like a bad guy. And so he just got like completely frozen out of Google. He frozen out of Gmail. He'd use it for 10 years. He had had all this AdSense revenue. He's like a stats professor.
Right.
So, you know, we can't trust in these systems to have a 100% positive rate. Innocence will get caught up in it, and that's bad. And decentralization allows it to be set up such that you can't take these kinds of properties away from people. Because 10 years ago you might have said, oh, who cares about my social network? Today it's like a primary source of income for a lot of people. And they have no customer service rep they can get in touch with at Google or Facebook or Twitter.
They specifically don't have customer service reps at YouTube so that you have no recourse when they turn off your account. And we've seen that people built up huge followings on Vine. They shut vine down. They built up huge followings on YouTube. Then they said you have to have 10,000 views to have the video make money. And now you have that whole class.
Exactly.
So these companies are getting so big they're able to really essentially silence people. And that's dangerous.
That's right. And I think, like returning to your original point about should Facebook be regulated? No, but I do think that. Not more than it is, but I definitely think that we should allow lots of decentralized competitors to crop up because what those will do is they'll chip away at all these individual features where the reason that Facebook is problematic in many ways is that there is no alternative. And if you allow folks the ability to build those alternatives, well, then I think you're going to have the market create some really interesting things.
And in this world, the posts and the individual accounts would be kept on a blockchain and you would essentially reconstruct your Twitter feed from the blockchain.
Yeah, basically.
I mean there'd be a permanent record of every tweet you do with no ability to remove it.
One, one caveat. So it wouldn't necessarily be on the blockchain like the bitcoin blockchain, but a blockchain.
A blockchain.
And now the second point you mentioned is actually a very important one. It's on the frontier of blockchain research. So typically with databases you have four functions. Create, read, update and delete. Blockchains only have really create and read, update and delete are things that you have to sort of emulate with blockchains. And so they're not yet suitable for all purposes. So that aspect of it's an undeletable blog post is something that we're going to have to figure out the right way around. Right.
Being able to go back into the.
Blockchain and change, edit or something. Yeah, there's ways you could sort of emulate with like log structuring and so on, but it's kind of a cutting edge problem right now.
And who should as a startup, when you're thinking about your startup, at what point should you consider an ico? And then the second question I have is for people who are fund managers like myself or you previously were, or you are part time or Mark, should we be thinking if you have unlimited access to high quality LPs, should you be thinking about taking crypto from random people and having a big open pool of capital and letting people trade it mid fund before disbursements? What's the upside? What's the downside? Should I do that for the Venture side, angel side, and then also for the other side founders. How should we look at deciding if we should do ICOs or not?
Good question. So I would say as an individual, I only do crypto investments except when it's a very close friend or somebody I know extremely well and they're still doing a conventional startup. Haha. And you know, that's not to say startups are over or whatever, but I do think that more and more stuff is going to go to crypto over time as regulatory and other kinds of issues are worked out. Because if all else being equal, if the regulations are equal, if everything else is equal, you'd vastly prefer a token over the equivalent, you know, alternative finance methods. Because they're liquid, they're programmable, they've got all these, you know, great properties.
All right, I know what liquid is. That means I can give it to you. So if we were both an entries and horowitz1, which had slack in it, and I need to pay for a house in college and you are long the fund and slack, I could sell you my position at a 20% discount. It just shifts over Andreessen. Horowitz either decides they want to approve it or not. They could actually do that, I guess. But the second thing you said was not about the programmable. Programmable. What does that mean? Explain that to the audience.
So, several things about that. First is it means that you can actually run a crypto hedge fund where you can enter and exit positions programmatically, you can balance things and there's folks who are doing that. In fact, I think everything moves to be a crypto hedge fund by about 10 years. That is to say right now you've got all these different sectors of finance. You've got individual angels and you've got VCs, and then you've got your PE guys and then you've got private equity. Private equity, Right. Pension funds. Hedge funds. Exactly. And you've got these mutual funds. Mutual funds.
Right.
And I think what happens is with digital currency, first you have a completely new player enter the system. Who is the sub angel? It is the kid in India with 10 bucks saved up who buys some Ethereum, which is now possible to do. Right. And second, everybody basically, whether you've got $10 or $10 million or $100 million, I mean, the intraday trading volume of Bitcoin today is like 1.8 billion. Right. People do not understand how big that is. That is at the same scale of Google. Google is like $1.5 billion. Trades hands on a Daily basis. So liquidity of these coins is already at the level of the largest public stocks. Right. And so because of that, I think from the largest hedge fund to the smallest individual investor, it's all going to become crypto. Here's an interesting statistic. USA Today a while back ran this study. I actually want to update the chart. But since Sarbanes Oxley, the number of public stocks has just been falling because it's so hard to go public and many folks are just going private or exiting public stock markets that you've had the number of public stocks more than cut in half since Starbucks. One of the things I've been doing is I'm making a graph and around later this year, the number of coins is going to pass the number of public stocks.
Got it. Not in value, but in quantity.
In quantity, that's right. And obviously non value because 150 billion market cap is less than market cap of one apple. Right. Nevertheless, unfair comparisons are sometimes really interesting. Here's another one. Coinmarketcap.com Adam Ludwin pointed this out, has more traffic than WSJ.com right? Okay. This random site has more traffic and that seems like an unfair comparison until one remembers why did people buy the Wall Street Journal? In the past it was to look at the prices of stocks, Right. And then the information was kind of a sidelight to that. Right. So now like CoinMarketCap, you know, you could imagine they could build a really interesting site there. Right? So I think all this stuff, what happens over time, probably 10 years, lots of regulatory issues, lots of bubble type behavior to be worked out. But eventually the Internet becomes the world's biggest stock market. And I think if I was doing something today, right. If I was creating a fund today, definitely. I just think all crypto because that's where the future is going to be.
So if I start a new fund, I make a crypto and then I let anybody buy it in the world.
What do you mean by that, let anybody buy? Oh, you mean launch a coin for your own crypto sale?
Yeah, I would launch a. If I were to launch fund too. I can't say if I was or not for obvious reasons. But if I were to do that, and I just said it's going to be a $50 million fund and each coin is worth a dollar today and anybody can go buy them.
I wouldn't do that. And here's why. It's just because I think whenever a new technology is coming out, you want to try to figure out, okay, how can I use this to do something transformative. Also minimizing my technical and legal risk. Right. So, for example, Netflix knew the Internet was going to be a big deal, but they also knew streaming video was too early, so they did mail order for a very long time before they made that transition. And so what I would do is I would, you know, if you have the connections to do it, which you do, I would just raise a fund as normal, from normal LPs, have that part be something that's completely understood and locked down, and then go and invest in various kinds of connections, coins. Because you're not capital constrained.
Right, right.
For somebody who is capital constrained. Yeah. Then maybe they might do an ICO kind of thing, but they take on huge amounts of legal risk in doing that.
Got it. There is this zug.
Yeah. In Switzerland.
In Switzerland.
It's a real place.
It's a real place and you can do whatever the heck you want with crypto there. I understand it's like a loosey goosey kind of province where anything goes. Is that correct?
So I'm not sure they'd market themselves that way.
I think they did say loosey goosey come to Zug.
Yeah, yeah, exactly. So I think it's Zoog. So Zug in Switzerland is based.
Sounds like a Bond villain.
Yeah, yeah. That's where Ethereum got set up.
Right.
And so because of that, it's become like the crypto valley. Right. And so lots and lots of folks have set up Swiss Foundation.
Have you been there?
No.
Are you going?
No, not anytime soon.
If you go, let me know.
Maybe we'll go.
Sure. Okay. I don't know what's there, but maybe.
We'Ll do a few.
Is there a there? There? Is there like just like a pile of Ethereum, like just laying there like.
That would be interesting.
Yeah.
Physically materialized. Yeah, physically material. I mean, Minecraft or Switzerland is a good place historically for banking and other types of stuff.
Right.
So it's not that unusual. It's not like that random a place for it to become, you know, kind of cutting edge on this type of stuff. But. But yeah, there's now other centers are starting to open up in other places in the world. Like, you know, Finland and Singapore and Estonia and so on are all very pro crypto. Estonia actually even wanted to try and do a cryptocurrency themselves. And like Mario Draghi of the ECB said, no, you can't do that as long as you're part of the Eurozone. So at some point they might say this actually has more upside than Being part of the Eurozone. So we'll see. You know, they did their E residency thing and they've got like millions of folks abroad who are effectively Estonian honorary citizens of a kind. I was like one of the first of those. Tim Draper, Steve Jefferson or others were just kind of testing out the systems. The goal there is they're a million person country on the border with Russia. And if they can have millions of people around the world back them up, then if Russia invades them, then we can protest.
Right. So wait, you're becoming. You get a passport or citizenship. What do you get?
It's e citizen, so e resident, I should be more precise. It allows you to open a business and do business in Europe.
Got it.
Which is very useful to.
So basically they're becoming like the Delaware Corporation headquarters and just saying, like, hey, do it for free here. It's all good.
That's right. So if you've got more E residents than you have citizens and their export is basically their, you know, excellent rule of law and Internet based systems for interfacing with Europe, you could imagine they might put a crypto aspect into that eventually. Right. So there's folks there who have been thinking about that.
This is Estonia.
Yeah.
So Estonia will be the first crypto state.
I don't know, you know, like China's actually doing extremely. They're very ahead of the curve on that. They've been working on their own crypto coin for a while.
The government.
The government, yeah.
So the renminbi will become a coin, you think?
I don't know. I do. Well, here's what I would say. I would say that what's happening now in China with blockchain and bitcoin and.
So on reminds me what is happening.
What's happening.
They're locking this shit down, right?
Yeah. So for those who haven't followed every single, you know, like blow of the. Blow by blow of it, they banned ICOs. Then they like basically shut down all bitcoin and crypto exchanges. And the rumor is that executives from those companies can't leave the country. And so. Yeah, that's not great. Right? Yeah. But we, we believe, or at least, you know, a lot of folks who have been watching it think maybe the next shoe to drop is related to mining. That would be a big shock to the system, but not irrelevant. Whoa. If they stopped mining, they could, they could stop it. They could take it.
Over 60, 70% of mining occurring there.
That's right.
So because people are stealing electricity from hydro dams, is this an urban legend or Is this true?
So I think it's maybe phrased more negatively than that because, you know, the thing with power generation on the electrical grid is you can't store power very easily.
Right.
Batteries aren't that good. Right. So.
And it has to be blown off, basically. Blown off.
Exactly. So what happens is peak power consumption is typically like 12 noon, and then minimum power consumption is like 4am or 5am Right. And during that period, you need to maintain enough power generation for peak. So often what people will do, it will spin a water wheel or otherwise throw off that excess power. So in China, they've done a lot of deals with basically what are called bitcoin batteries, where essentially it's better to store that as digital currency by mining than it is to store it as energy, because you just can't store that much energy.
It just burns off. It's like steam off a pot of boiling water.
That's right.
So capturing something that otherwise would have.
Been lost for a while. If you looked at the Chinese blocks, they were disproportionately mined late at night in China time because they were using spare power.
Who's doing that, though? Is it the government? I mean, we have no way of knowing.
Yeah, I mean, I know some of the folks involved, but basically they're just extremely competent hardware and data center engineers over there who are running large data centers. Centers. And they can do deals that people in the United States can't because the power companies are more open to it.
Was that a mistake with Bitcoin to put in this whole fakaca, like, we have to burn all this electricity and carbon dioxide into the planet? Shouldn't they just have issued them other cryptocurrencies as opposed to mining it?
No, I think mining is actually super important.
But it's so bad for the environment, isn't it?
Well, so what a lot of people do is they'll say, okay, you know, bitcoin consumes this much power, but look at Visa or PayPal and they consume much less. Right. But I don't think that's actually the right comparison. The right comparison is how much power does bitcoin consume and how much power does, like, the government of the United States consume. Right. Because what bitcoin is and what blockchain is more generally is its rule of law as a service. Right. Even into lawless places like Venezuela, you can parachute in a predictable system of property rights. Begins with Bitcoin for money and then with Ethereum for smart contracts and so on. And over time, what that means is rule of law is a service anywhere there's a smartphone. So what you're really doing is you're doing something where the blockchain is to the Constitution, is the constitution is to UK common law. With common law, you had this sort of informal formalism within the UK based on precedent. Then you got that formalized with the Constitution in the US and now we go to the next step with smart contracts and blockchain. It's kind of like the next step.
So a country that's run by a Mickey Mouse dictator who might flip the currency around at will depending on what's happening or manipulate it, those people get to join a different country's constitution by buying Ethereum and buying Bitcoin. They just basically opt out of that country's constitution.
That's right. So like, because that's already happening in Venezuela, right? That's already happening in places that are not respecting the rule law. Now those folks have an exit, right? They have an alternative.
And we're seeing that in the statistics. The number of wallets in Venezuela, the number of coins being bought.
And it's, I mean, like, you know, it's one of those things where probably five years from now, every year it gets better and better. The infrastructure. I don't know that there was a large Venezuelan Bitcoin exchange there. One of the biggest things that's going to be developed are decentralized exchanges where you only need an Internet connection in order to earn it. And then I think stuff that hopefully like what we're doing, where folks can just do labor, turn digital currency will also be a big thing where even if you don't have capital, well, anybody in the world can pick up a phone. Anywhere there's a phone, there's a job. So over the next five, 10 years, we're going to make it more and more and more accessible so that anybody in the world can, can kind of opt out and just get this digital currency.
What does your gut tell you will happen here in the United States? And how do you rate our regulatory organizations in their management of crypto to date?
I actually think they've exceeded expectations so far with the exception of maybe New York state in 2013. People thought that the US government was going to take a very potentially negative attitude towards crypto. And a lot of technologists, a lot of VCs and so on, went and talked to folks who were institutional. And the reason is because VC is the interface between disruption and institution in the sense of you speak to the guy in the garage and you also speak to a Large pension fund.
Right.
So you're kind of a trusted interlocutor between both sides. Right. And so as such, you could go to them and you could credibly represent that this blockchain thing, this bitcoin thing could be a big deal. Let's not kill innovation in the crib. Could be a big deal for fintech. Fortunately, that worked. And for the most part, the government really stayed their hand from 2013 to 2017 insofar as there are regulations. It was like somewhat annoying stuff, but it wasn't like insuperable. The industry did not die by any means. It in fact grew quite a bit.
Right.
Recently with the SEC's document. I actually kind of take my hat off to them because they did a few things. First is they definitely got up to speed in the technology. If you read the document, it's a sophisticated paper. There's at least some people there who are.
Is this the Dow document?
The Dow document, that's right. So this came out like a couple of months ago. It's a sophisticated paper and they're familiar with Etherscan, they're conversant with the whole shebang, which is impressive. So that's kind of number one. And then number two is they said ether was a currency and they said effectively not all tokens are securities. So they did not ban the nascent industry and they've made pretty positive noises about blockchain, other types of stuff and so on. So it looks like they're actually taking a fairly enlightened attitude towards it and let's hope that that continues.
When you look at the landscape here in Silicon Valley and you talk about, hey, capital is going to be sort of uncoupled from Silicon Valley, what do you think happens to this incredible Silicon Valley infrastructure that has created the greatest companies of our lifetime or in the history of humanity, it's literally going to just not be competitive. Do you actually believe that, that all of a sudden the next Facebooks, the next Googles, the next Apples and Airbnbs and Ubers and Lyfts are all going to be just funded by random crypto, ICO sales.
And from anywhere it's already happening. I mean like Ethereum did not have really a center in sf and you know, what's the next Facebook, the next Uber is Ethereum, right? And that was in Brooklyn and Berlin. It didn't really have any presence here. And you know, I think like one of the big differences with blockchain, as opposed to say something like mobile, right? Mobile was extremely top down. It was Apple and Google.
Right.
So it was instantly credible. Right. Like Android and the iPhone, everyone, they had PR teams and they obviously had great tech teams and so on. So super, super top down, the blockchain began. Bottoms up in the most bottoms up fashion possible. A pseudonymous post on a message board forum. Right. No reputation, no credibility, only pure technical credibility. So it took a while for it to rise. And yet even now, only eight years into it are Facebook and Google and Amazon and so on. Looking at it, Microsoft of the big five is the one that is kind of the most ahead of the curve on blockchain. They've been doing it with Azure and so on. And that's because Satya is hungry and Microsoft's the hungriest of them.
Yeah, but when you're behind, you take risk.
That's right. And actually Satya as a side like, deserves amazing. Even before his book, he deserves incredible credit for turning around Microsoft. Very, very hard to do.
Well, I mean, just the nature of being able to say we're going to put Office on Apple phones and Android phones and all of a sudden you look and it's like Outlook is in the top 10 apps and you're like, oh, well, this could have been that way for the last five years if Steve Ballmer would have just allowed it to happen.
It's hard to run a large company. And all credit to Steve Ballmer in the sense of he grew enterprise profits. The amazing thing to me was Sathya didn't just open up Microsoft on those dimensions because it would have been easy to do that and then see profits drop. He also increase profits. Like, you know, the monthly subscription, it's so cheap. Yeah, exactly.
Like Adobe.
Right?
Like they just figured it out.
Exactly. So suddenly all their products is amazing how his leadership, everything became like competitive. Office365 stopped losing accounts to Google apps and, you know, their, their code push stuff is actually one of the best ways to get stuff onto, you know, iOS. And it's like, it's just really amazing that one guy could just transform so much stuff. Anyway, he just deserves a lot more credit than he gets. I think.
Just do a little lightning round here before we open to a couple questions. Which of the fangs or top five Internet companies will be the largest in 10 years? Which one has the brightest future? Amazon, Apple, Google, Facebook?
I think Google is. That's an interesting one.
Take me through your thinking and then let's come to an answer of who's.
Going to be the big winner. Well, okay, so we had to bet the thing that I think about the two things I think are the biggest risks for Facebook, Apple, Google, Amazon. I wouldn't put Netflix in there. I mean, Netflix is a great company.
You could put Microsoft in there.
Yeah, Microsoft. I think the biggest two risk factors for them, and obviously I've got a biased point of view, what have you, but are regulation and decentralization. And the reason is they've gotten very politically unpopular recently on both left and right. Probably Google has lost, I don't know, 20 or 30 points of popularity in the last couple of months alone with various episodes. And that popularity is not coming back, in my view, because at a certain point when you get big and powerful enough, you're going to piss a lot of people off basically, no matter what you do, and forced into really polarizing situations. Plus they've got lots of money and that always makes them a juicy political target. So those two things interact, regulation and decentralization. Because their presence in the United States is something where, I mean, these are global companies which operate all over the world and have employees, frankly from all over the world. Right. Like that's one of the things most people don't understand is Silicon Valley and technology is majority minority. It's majority immigrant. Right. Most of the folks are from overseas. Right.
And majority of revenue is overseas.
Yeah.
So when you start thinking about it from that perspective, like the cash register is not an American cash register.
Exactly.
It's a multi continent cash register.
It's a multi continent cash register. Right. And for different ones of them, the breakdown looks different. But all of them, while they start in the US are really very much global entities. So because of that, there's been, I think, a tension between, okay, our customers are mostly overseas, our revenue is mostly overseas, our employees are mostly immigrants. We're headquartered in the US but probably most of our employees are actually maybe based around the world. Depends on some of them. Like Mountain View and the Menlo park campus are pretty big. So now they're going to be kind of forced into this thing. Are they American companies? Are they global kind of entities? And all the stuff they set up with foreign corporations, all this stuff I think is going to become under siege over the next three or four years because they've just lost too many popularity points, I think. And I think that's a threat for them. And then alongside that is decentralization, where a lot of their network effects can be broken. Now, of these, the ones that are like, how do I rank order them? All of them have just really difficult to penetrate positions. I would actually say Facebook is probably the most vulnerable of them because Amazon and Apple have large hardware manufacturing divisions and Google has. Well, Facebook also has large data centers. But Facebook is probably the most vulnerable because I think you can break network effects with tokenization.
And we've seen that people kind of get tired of social networks and move to the next one. Yeah, people are a bit transient in them and they seem to also be generational. There's like a Facebook generation versus a snap Instagram generation.
Yeah, I'd say Amazon is probably maybe the hardest one to displace because of just the sheer scale of their physical manufacturing.
And they have so much upside left to capture manufacturing.
But you know.
Well, in some cases they are Amazon based in the Kindle. I mean, they are buying a lot of factories from what I understand.
Physical plant. I'll put it like that. Yeah, physical plant.
And they're just so such a small percentage of their market, whereas Facebook is such a large percentage of their market.
Yeah. So I'd probably rank order them in terms of difficulty of disrupting Amazon first, Apple second, Google third, Facebook fourth.
That's exactly my order.
Yeah, yeah, yeah. But I'm not saying they're going away. They're going to be huge companies for a long period of time, but I do think that they're going to be facing these twin threats which are hits that are very hard for them to counter because their very bigness leads to people aligning against them on the policy side and then also on the technology side from decentralization. Like the reason to go and build a decentralized social network or to build a decentralized exchange or a decentralized marketplace is because it's not one of the big guys. And so why do you build a decentralized domain name system? So Google can't yank your domain like that kind of thing. So anyway, that's why I think it's sort of like the Microsoft situation in the late 90s where they're going to be put into no win situations and winning is losing.
Okay, this has been amazing. Let's take two questions. One from the chat room. Ashley, are you there? And then we'll run a microphone over to my friend over here. We would like a crisp question. Please refrain from a commercial for your product or service. If somebody does, everybody knows the rules of this week in startups. If somebody does a commercial, Val does a question, everybody groan. We can practice that. Okay, so with that disclaimer, a crisp question, please. Hi, I'm Anita Darten Gardine. I'm the CEO Of Oneiva. My question is, has either of you invested in a woman of color?
Yeah, definitely.
Let me think, would you count Indian or Asian?
Have you ever invested in a black.
Co brand of color? I don't know if we have a black founder in the port, a black female founder in the portfolio, but we have black men in the portfolio, so yes, black men, but I don't think we have a black female founder yet. But I have a feeling you have a great company and that we'll talk after I won Disrupt last week.
Runner up.
Okay. Congratulations. Actually, I thought I remembered you from somewhere. Yes. What are your thoughts generally on diversity in technology? Is it getting better? Do you feel it's getting better? We're obviously very focused on it as an industry. It feels to me like I'm seeing a lot more diversity in the early stage. What are your thoughts on progress? Obviously there's a ways to go, but is it getting better?
Well, so if you take a global view, I think that I'm very excited about technology getting to places like Nigeria, India, South America, Vietnam, places that were basically poor through the entire 20th century and that have a lot of talent now. So stuff like what Mark Zuckerberg did with investing in Andela in Nigeria I think is really interesting. And so what I'm excited about is really, from a goal perspective, tapping all of this untapped talent.
Great. Let's take a question from the chat room first so we make sure the people who are on the live stream get some play. Go ahead.
Ashley from Eamon, what is the future of ICOs? Will they be replaced by fork from core blockchains for specific use cases, example bcash or eth?
Okay, I don't speak French, so can you translate that for the rest of us who don't speak crypto?
Sure, sure. So what, there's different ways that you can create a new coin. One of them is what she just talked about or what that question mentioned, which is, do you fork an existing blockchain and basically airdrop coins on every existing holder of that chain? Or do you create a new coin? And I'd say, frankly, it depends on the situation. So forking existing coin, for example, the bitcoin bitcoin cash fork meant that everybody who was part of who held coins in bitcoin before also got coins in bitcoin cash. It was sort of like a stock split. Right. And you know, whereas an ICO is, you're generating coins for a completely new purpose.
Right.
So I think that forking of existing coins will probably coincide with Forking of developer groups like what happened with Ethereum and Ethereum Classic or with Bitcoin and Bitcoin Cash. There may be coins and tokens that build in some percentage of their token base as an airdrop. So that, let's say 5% of your tokens are awarded to all Bitcoin or Ethereum holders, you know, by presenting their credentials and they get the coins back. But I think there are two different tools to be used for two different situations.
Great. So let's take a question in the room. I don't know where the microphone is, but I see five hands going up. So we'll get like maybe five questions.
So this is a two part question for both of you. Are we effectively seeing seed rounds become bridge loans in the sense that safes are never converting because of product and utility tokens? And does that bode well for the employee option pool saying that there's no precedent set for token companies being acquired or any exit scenario yet?
Okay, great. Complex question.
Well, so what do I think about that? So I think the interface between what I call the coin table and the cap table is something which, you know, the industry is still figuring out. Probably a good way of doing it is as follows. So let the coin table refer to the set of all coins and let's say that your company has X percent. Let's just say it's like 25% of the coins. One useful way to think about it, something I've seen in some documents, is imagine that 25% effectively hovering over the existing equity waterfall. And then you have a board of directors vote or a shareholder's vote to liquidate that. And then that goes as cash through the waterfall. That's a way that you can kind of take all the existing agreements that you have within the company, all the investor relationships and liquidation preferences and whatever, and honor that while still creating this kind of new token.
So you basically take 25% of the coins that you're going to sell and just pass them through to your shareholders pro rata or on a percentage basis.
Basically as if it was an exit. So let's say that 25% of coins is worth $100 million. That's as if it was $100 million exit.
So there's 100 million shares and we each own 10 million shares. As co founders we each get $10 million coins, but then we have a tax event.
Well, right, exactly. So there's a couple of caveats. Right? So the first is that there's a difference between a distribution and a liquidation. Like a distribution is you just distribute those coins at their current value out.
Right. So we have them in our wallets, but we haven't sold them. So there's no tax.
Yeah, that's right.
Or hopefully no tax.
And it also doesn't crash the price.
Right.
Because some folks believe there's still future upside and they want to hold onto it.
Right.
Whereas liquidation is you actually go and dump some or all those coins on the market. And that certainly if done in an expert way, can tank the price. Right. So that's kind of one aspect. Distribution versus liquidation. Second is something that doesn't occur in typical VC backed companies, which is a partial exit. Right. You can choose, okay, if you've got 25%, let's go and distribute 5% today at this valuation. Right. Clear out the liquidation preferences, Rev. Still hold 20%. Right. And the third thing is to agree on exactly how that spot price is determined is actually something you want to put in the contract beforehand. Because it can actually mean a very big difference if it's 5 or $10 lower. Right. Because like are you consulting Coinbase or you're consulting Coin market caps price, whatever, that service better be up on the day of because it's like the difference between, oh, 17.5 cents a share versus 16 and a half. It can make or break a deal sometimes. So it's an important kind of thing. So I'm not saying those are best practices. I'm saying those are emerging things that I've seen ways to interface the coin table with the cap table.
Yeah. And I've had this come up a couple of times in discussions. And I said, just make sure that you don't put yourself in the position that the coins become worth so much money that they fall below, much below what the equity's worth. And the people who gave you cash feel like idiots. And for giving you money to start the company, like Vinny Lingham and his company Civic has raised 30 million in the coin. And how does that relate to the people who gave him venture money, et cetera. So definitely new area. We're in on notes, convertible notes. What's nice about a convertible note with a date is that the founders and the investors have to sit down and say, do we extend this note for a year or do we convert it now at a certain cap or another valuation? And it's kind of a forcing function. What I don't like about the way some safes are structured is I've seen safes where people sell one person at 6 million, one person at 7 million, another person at 10 million, another person at 12 million. They don't know they paid different prices. They all bought within the same 90 days. And then they all convert. At some point, people get the cap table and they're like, what just happened? And a lot of bad feelings. And what if you convert automatically at a price? And sometimes people put their safes designed this way. We're going to convert no matter what at a $10 million valuation in 24 months. What if the company's worth 6 million at that point in time? Well, then you're screwing your investors by converting them at 10 and then taking other investors at 6. And you just have to be careful that you don't get this adversarial relationship. And I feel like the safe note was created in some ways as being adversarial, anti governance. And what we've seen is bad governance kills companies. So a lot of the companies I've seen die have had a lack of governance and said, I wish I had a board, I wish I had a lead investor who cared enough about the company that when we hit the wall, we could have done something right. So this idea that it's cool to have no governance, I see a counter trend, which is it's cool to have board meetings, it's cool to have minutes, it's cool to price your round. Because with VCs looking for more disciplined founders, when they see, oh, here's four board decks and here's four sets of meeting minutes and here's the resolutions and we know the share price and we don't have to convert and have all those bad feelings of seven different convertible notes that happened over two years. It's just really messy. So there's a lot. It's one thing when there's one convertible note or two, but when you start getting to these, like, you know, a half dozen or a dozen, I mean, you've probably seen this and then all of a sudden the founder is like, I own how much. Like, there's a lot of shock on these cap tables when people figure out how much they own.
I mean, also typically, I mean, the cap on the convertible is basically kind of the price on the round. If you haven't exceeded that, then it's kind of like, oh, you didn't hit what we wanted to hit. I would agree with 95% of what you said in the sense that I agree structure is good. I agree regular board meetings are good. I agree engaged investors are good.
Plans are good.
Plans are good. Pretty good, right? Try to hit targets yeah, all that stuff is excellent. And because a startup is a very unstructured thing and imposing some structure on it is handy, especially by folks who have been through the trenches. I would say, however, that a founder has a sense of what they want to do, should not, for the sake of it, give up veto control over the big decisions.
For sure.
That's my only caveat.
Yeah, I mean, losing control of your company, not a great thing to do. Right? So you want to keep control of your company. But it's also quite nice to sit down quarterly and say, what are we doing here? And actually having your team say, you know, every 60 days we meet with the investors. It would be nice. It's a nice device for a founder to be able to go to the team and say, I had a board meeting for Inside.com this morning at Sequoia. It's like three weeks ago. We're like, what is this board deck going to look like? And are the numbers up and to the right and do we need to kick ass in these last six weeks or four weeks before the board meeting? It creates a sense of urgency when you go into the halls of Sequoia or in Dreeson and you got to face the music and say, hey, do we hit our plan or not? And present a plan and have people with 20 or 30 years experience say, I've seen this movie before when we did Netscape, when we did this other cloud company. Like they can really have great signaling. So it's cool to have governance, I think. Okay, who's got. I don't know who's got the. We take one more from the. Do we have any more questions online right here. Okay, hold on one second. Do we have more questions online or no? Okay, let's take the. We'll go online for one and then we'll go live this way. People feel like it's. But we're going to get you, don't worry, I see you. I pronounced it right.
Okay, what is the best way to incorporate tokens into my syndicate? A majority come from my real estate. I'm assuming LPs with non tech backgrounds. They trust me. I want to include new tech without overwhelming them.
I'm completely confused by that question. Do you understand that?
I don't really understand it. I'm sorry.
I heard syndicates and tokens in the same thing, so I don't get it. All right, well, you want to try one more time? Go ahead. Let's try one more time.
How about what is the best way to incorporate tokens?
Into my syndicate. Okay. Does that make sense? Sort of. I guess you could have an angel less syndicate with tokens and then people would be able to then trade it. I think naval has token list.
Coinlist is coming.
Coinlist, yeah. Which is going to do let you do coin offerings, but I don't think there'll be syndicates. Exactly.
I mean, the thing is, there's two different ways of doing it. You can have a coin that folks buy into and that's your capital for your syndicate, which is what you were discussing before. Possibly. And there's also your syndicate investment and coins. I would certainly not recommend combining the two because then you just got so many stakeholders and stuff and complexity. I think, you know, investing in coins as an individual or as part of a syndicate is definitely a reasonable thing to do in 2017. I would say like doing an ICO to raise capital is something where only do it if you really want to do it and there's a law firm and so on backing you and recognizes risk associated with it.
Okay, now I'll take a question from the room. Good.
Sounds good.
So, Blockchain, you can say your name and your company, by the way. I wouldn't consider that part of a promotion.
Devin Elliott, founder of Unoceros, which launched.
At launch festival in 2015.
2015, yeah. Great idea. I remember.
It's fantastic. Which by the way, your idea became the subject of Silicon Valley's last season. So you had the crazy idea to have a peer to peer network on mobile phones. Yes. Which is exactly what Pied Piper built. What was it like to see your idea from the launch stage in 2015 become the arc of Silicon Valley, the TV show on HBO in 2017? I think that was a rough first night. I didn't want to watch it. I just fielded quite a few texts and kind of settled into it though.
It's pretty entertaining, actually.
Okay. It's literally the same thing.
Yeah. I actually wanted to ask you, did we actually just pitch one of the.
Writers at your event or what? The writers of Silicon Valley have been to the event, my poker game. And I've talked to them on the phone. But I never said Oscars would be the great story arc of story arcs. So it's possible they saw it. But anyway, you created a distributed network on mobile phones. Yes. You basically made a second Internet on mobile phones. But anyway, go ahead and ask us your question. So it's a wonderful diversion, by the way. Wonderful. Yeah. Thank you.
Well, so Blockchain is just part of a new technical stack of protocols Right.
And it alone doesn't impart all of.
The things that are needed to run.
On decentralized, untrusted hardware. As investors, are you guys engaging any.
More technical due diligence for any of these companies? Yeah. So? Well, so I have a PhD in double E from Stanford and I taught CS and stats, so I usually like to read the source code myself. But you're absolutely right that it's not just the blockchain. You have to look at every aspect of what they're doing, but the blockchain is a new primitive that allows you to monetize those protocols. So that's kind of why we brought it up. But I think you are right that to a broader point, the technical diligence actually is something which is critical in the space and it almost kind of replaces not deal flow. Exactly. It sounds like there will be people who will see certain coins early, but many of the skills of VCs, like, oh, I've got proprietary deal flow, are going to become less and less important. And the ability to go in and be like, okay, line 47 over here. Why is this company using ternary rather than binary? Like a company you might know of? That's like a really weird design choice. And why does their main CPP have 5,000 lines of code rather than being factored properly? All those kinds of things, you'd actually now want to have at least somebody in your team prior to investing who has read the source code and who can give some kind of attempt at trying to build it and look at it.
I look in the eyes of the founder and I look at their product and craftsmanship and I figure out if I think they're going to quit or not. So I use my degree in poker.
It's also actually very important.
From Stanford, from the money I took from Stanford students playing poker. I take that and then I decide what. Who to invest in. And that's my diligence.
I should also say I am not a degree snob. We hired lots of folks. I've hired many folks without high school degrees. Do you play poker? I play poker. I haven't tried. Really?
Yeah. Do you have money?
I have some.
Okay, great. That's a good strategy. That's all you need.
All right.
That's all you need.
I'll teach you. I'll teach you.
All right. Do we have time for one more question? All right. I don't know who's got the microphone? I don't think they're going to. Let me take another question. You let me take one More, Jackie. All right. It's got to be a lightning question, Titus. Right. I'm Tim Wagner from Accenture Ventures. So I had a question.
I think it was pretty inevitable that SEC would kind of step in with ICOs. What is the best case and the worst case for that?
I mean, are they going to try.
To recreate the stock market or are they going to really look at the power of what ICOS can bring, something new? I think the best case is if they take. I mean, you have to sort of judge a revolution by its fruits. Right. And so the blockchain industry today is at roughly 140 billion total. If in four years it's at like 3 or 4 trillion, which is quite possible given its rate of growth, then the SEC did a good job in terms of specifics. I think probably the best thing that could be done in the best case is there's a very obvious set of things you have to do to make sure your thing is not a security. Right. There's a bright line test, and the Howie test is starting to get there. Maybe, but there's a bright line.
Explain what the bright line test is, because I've never heard that.
Oh, well, like, so a bright line test in general would basically be, okay, if you do X, you're on this side. If you do not X, you are on that side.
Okay, so it's exactly what you say.
Yeah, yeah.
It's a bright line, it's a bright line. It's clear you're one or the other.
Yeah, that's right.
Got it. Ok. Colloquialism. Well, it's not an actual test. It's a colloquialism.
It is something that lawyers will often say.
Got it. Okay. Bright line test. Got it.
So basically, the Howey test is something that SEC has said determines what is a security. Explain what that is, what the Howey test is. Yeah, sure. So this actually goes back to 1946, 70 years ago, there was a case involving orange groves where people essentially came up with a set of three points that determines whether something is or is not a security. It's like an investment of capital in a mutual enterprise where other people are working to make money for you. Right. And if one of those three points is not there, then your thing doesn't pass a Howey test. And if it doesn't pass Howie test, it may not be a security. But ideally we'd have a test on the other side where if you pass this other test, then you're definitely not a security. And so, for example, a House appreciates in value, it has utility, but it's not a security. A domain name appreciates value, it has utility, it's not a security. So one of the best things SEC could do is figure out a safe harbor where if you do X, Y and Z, then you're safe, right? And that'll reduce everybody's legal costs. The alternative is that there's another country that does figure out that safe harbor earlier. And for example, there's always some precedent for this. So in the UK they came up with this fintech regulatory sandbox, right, where it allows companies to get to market earlier, like the Next Stripe, without having to get all these banking licenses and so on. And that was an innovation that threatened to pull US companies over there. So actually the US to its credit, has actually responded with its own OCC type charter. So you don't have to get 50 state money transmitter licenses and so on. So if there is some jurisdiction that says, hey, we're open for business, you can do a token launch in our jurisdiction, that country, if it markets itself properly, worldwide will have a real shot at the next Wall street, right? And so that's the alternative. If the SEC doesn't do it properly, then there will be another country.
Here's another worst case scenario. People invest money, they lose it, they still have a lot of money left and they sue the people who lost their money, whether they were right or wrong and whether they checked the box, that they knew that they were taking risk. Because as we've learned, people can sue at any time for anything and they could have no merit to their claims. If the SEC sees a bunch of people or a bunch of state attorney generals who are looking to put a notch on their belt, see a bunch of people take down 20 or 30 million dollars commissions like say Tezos did, they took a 20 million commission on their 200 million raised and put a bunch into a nonprofit. If that project were to go belly up, and if everybody who put the money in still thought, still checked the box, that they understood this was risky and they're just investing in a white paper and they had all their I's dotted and all their T's crossed, they could be in litigation forever. And then state attorney generals could litigate you and regulate you and just break your chops until you cannot stand it anymore and you settle. So that's the other reality is I call this the fair and fair use. In the fair use statutes, like there's a whole series of tests for something fair use and editorial. And so we would go through this with the magazine all the time, what percentage of the work did we use? Are we confusing the public, etc. Are we infringing on the other person's ability to do commerce? Is there an educational or analytical reason for doing this? There's a whole test you can go through. And what I would just tell my team is will the other person feel it was unfair our use? In other words, forget the law. Do people feel it was fair? And if the artist doesn't feel it was fair and the person of the original content owner, expect a lawsuit potentially. And I think that's what's going to happen here is if people just like on Kickstarter, if they don't get their product or the product comes so late and is so bad, they might sue. And I think that's what's going to happen with these ICOs is if the product never makes it to market, which some number won't, you're going to start to see people sue. If those people sue and there's no money to recover, then attorney generals might get involved and say, where did the money go? And I think that's what happened with the Dow. They were like, what exactly happened here?
Well, yes, let me jump in there for a second. So by the way, I think Tezos is actually a reputable project.
Oh, I had her on the show. I think she. I think it is reputable. But my point is, if it fails, which startups fail, the majority fail, it fails, which is the likely scenario for startups. Sure. So in the likely case that Tezos is like other startups and fails, when it does fail, will people say they took $20 million and don't deserve it?
Well, yeah, so. So okay, what do I think about that? In general success as a thousand fathers, failure is an orphan. Right? Right, Correct. Right. So everybody is genius when the market is going up and so on. And very few people have the guts to make it through a bear market. And you and I have both, in different ways, gone through that three times. Yeah, exactly. And so that's something where actually the folks who can make it through that and at least escape with their shirt or even make a profit are the folks who you want to bet on time and again. Right. That's kind of at the individual entrepreneur level. At the regulatory level, you're absolutely right. That failure is often criminalized. Right. Where essentially there's a retroactive lens that is applied and everything that was seen in rose colored glasses or a positive way before is now seen in a very harsh and negative way. Like the options backdating stuff in the mid 2000s where people were just looking for something to pin on these.com people, and it turned out to be options backdating. And we're very fortunate that Steve Jobs was not caught by that because there was attempts to get him involved in that whole morass. So you're right. Absolutely. That retroactively things can turn very sour. And you know, my advice on that would just be to paper up everything you can legally and try to minimize the amount of legal risks you're taking. That, you know, sometimes you have to take legal risks and then just, you.
Know, hope that here's a corollary example for you. Seven years ago, my friend Naval says, hey, I'm doing this thing, check it out. And I fire off my syndicate. I get a bunch of members, a bunch of people invest. And then a bunch of people said, you're crazy for taking other people's money. When you're investing in com.com, a meditation app like, this is ridiculous. You're going to get sued by the members of your syndicate. And I said, okay. And I wrote long disclaimers every time to the accredited investors. These are accredited investors, they're smart. And I just said, I am running the Trench run syndicate.
More from Balaji

34 - Network State Conference 2025 - Fireside with Vitalik and Balaji on Zuzalu and d/acc
33 - Network State Conference 2025 - Fireside with Amjad Masad of Replit and Balaji



06 - Network State Conference 2024 - Fireside with Naval Ravikant and Balaji Srinivasan