Session #2 Top 3 Reasons Rehab Loans Work for So Many FHA, VA & Fannie Mae
This YouTube webinar (Session #2 of a series) is hosted by Catherine Hall, Executive Director of the National Association of FHA Consultants (NFAC). Hall introduces three rehab loan options—FHA 203k (her primary focus), Fannie Mae HomeStyle, and VA renovation loans—then provides personal background and organizational context (her 1994 home inspection company, government grant work, formation of NFAC and the Genesys Rehab Reporting Project Creator). The chunk contains a detailed primer on FHA 203k: it's owner-occupancy focused (one-year occupancy requirement; many borrowers refinance after six months), has liberal credit/down-payment rules (FHA minimum credit score 580; 3.5% down with gift/OPM allowed), allows substantial rehab work including rebuilding on an existing foundation, requires minimum property standards and mandatory repairs, requires a contingency reserve (10–20%), mandates an FHA consultant when repairs exceed $35,000 (consultant fees are reimbursable), and carries FHA mortgage insurance for the life of the FHA loan. Hall also notes 2020 FHA loan limit increases (up to $765,000 in high-cost areas) and that 203k can be used on up to four-unit dwellings (owner must occupy one unit).
Questions this video answers
April 15, 2020
About 8,000–9,000 projects (speaker estimate).
One year (but many refinance out after six months).
Minimum credit score 580; down payment 3.5% (gift/OPM allowed).
When repairs exceed $35,000.
Chapters
And thank you all so much. Welcome to the second installment of the 203k Secrets field hosted by the national association of FHA Consultants. I want to thank you all so much for being on the webinar today. My name is Kathryn Hall. I'm the executive director of the national association of FHA Consultants and your host for this and all of the 10 part, actually six part series that we're going to be holding today. We're going to be talking about three great reasons to consider a rehab loan. And we're going to be talking about the FHA 203, the Fannie Mae home style and the VA renovation loans. I'm really excited about this segment because there's a lot of misinformation and frankly a lot of absent information when it comes to understanding what the different options are that are available to everybody. And so for me it's really important that I'm able to share this information with all of you so that, so that you can really understand what you're looking at and what you're being able to experience. As a contractor who is working with a customer who's trying to get a way to fund repairs to a property they want to purchase or renovate or refinance, A real estate agent who is trying to decide what is the best way for them to be able to maximize their customers dollars and their credit and their bank account. And as a FHA consultant or home inspector looking to become an FHA consultant. So today I'm going to talk to you about these options so that you can understand that in this world of renovation consulting, there are many different avenues that a person can take to be able to assist individuals and also to be incredibly profitable on their own. And so that's what we're going to be talking about today. So hang on for a second. I want to move this screen over so that I can be able to see what I'm doing. Okay, so hold on for one second. I want to switch screens out. Hold on. And let's see, we're going to swap them.
And. Perfect. Okay, so I swapped the screens. I'm going to do a new share and.
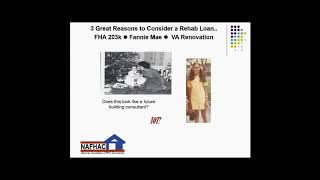
Move this over to here. Excellent. All right, now we've got it going on. Yeah. So I can look at you and still see exactly what you're supposed to be seeing on the screen, which helps me be a little more successful. All right, so let's start the sharing. Alright, so first of all, I don't know if you've been on many of the calls that I've done before. But every single time I have a class like this, the first thing I want to say is thank you. I want to thank you for showing up. I want to express my appreciation for the time and effort that you took to be with us today because you might be anywhere in the country. For me personally, I am actually always on the road and always in a different city in a different state, sharing the opportunity and the joys that I experience as a renovation consultant and as the standard bearer for the national association of FHA Consultants. So I just want to applaud you. And I'd like you to take your right hand and lift it up high and yes, I can see you. I'd like you to reach around and pat yourself on the back and say, thank you for showing up because you've done yourself a favor today. Because knowledge is not power. The application of knowledge is power. And what I'm hoping to give you today are some actual tangible tools that you can leave with that you actually can apply in your business right now, today, or if it's still a workday for you, or tomorrow morning. So I just hope you understand that today is a day that I'm going to give you resources that will make you feel like this has been a valuable experience for you. So the first thing that we're going to talk about is the three different types of rehab loans. Obviously, my personal favorite and what I was able to successfully build my business on is the FHA 203k loan. And so we're going to dive deeper into that than most of the other products, because from this loan is the base that all the other types of rehab loans were generated, and all of the rehab loans that are created now that have spun off basically use the FHA rehab loan as its foundation. Then there is the Fannie Mae home style. Now, the Fannie Mae home style is different from what used to be known as the Home Pass. So now, if many of you have heard about the Home Pass mortgage, that mortgage discontinued about, I would say, three years ago. Two to three years ago, the Home Pass discontinued as an option for home buyers. The Fannie Mae home style has not gone anywhere. It's still here. It's still a viable resource and a perfect tool for you to be able to use for any type of project that you're working on where you're looking to have a conventional borrower. So, and the reason we use the term borrower, if you might remember from the last conversation that we had, is because we don't just work with home buyers. About 40% of all rehab loans of all rehab renovation projects are for existing homeowners. And so with that being the case, we call them borrowers because they could be borrowing to refinance or borrowers for purchases of the property. So we don't just stick it to just people who are. Let me turn off this other light to make it a little better to see. Thank you. We don't just use home buyers. We do use borrowers. Okay, so just give you that little bit of knowledge. And the third type of loan that we talk about is the VA renovation loan. Now, for many years, the VA renovation loan was just for up to like $10,000. It was for very, very minor. And it's still meant to be for limited repairs, but the loan limit has gone up substantially. And we're going to talk about that during our conversation today. So before we get started diving into all this, I believe that you don't hear a person's words until you know who that person is. So I'd like to tell you a little bit about who I am if I could. And you might have heard this story before. It's one of the things that I never get tired of talking about is where I've come from and what has made me the person who I am. Because I hope you like who you are. Because I do like who I am and I enjoy speaking with you and I enjoy everything that I get to do in this industry. I actually was a only daughter with three younger brothers. And my dad is a basketball coach. My brother is a basketball coach. My other brother's a basketball coach. My two nephews are basketball players. You getting the drift here? We came from a very sports oriented family. And I was the egghead, I was the nerd. But my father used to trace me around everywhere he went because my mother died when I was 12 years old. She suffered from a disease called lupus, and it was a fatal version of it. And she died when I was 12. And when she died, she actually received her master's degree in education. She was a high school teacher. She was able to receive her master's degree in education posthumously because she worked on that degree up until her death. I remember as a little girl watching her lay there in bed helping her grade her test papers because she was trying to work up until the last minute she could. And she taught me something very valuable. She taught me never to give up on a dream, never to give up on a goal. Nothing should stop you on that dream, not even death. And she proved that because her goal was to get a master's in education. And death didn't stop her. After she died, my father walked down the aisle at Temple University in Philadelphia and received that wonderful outstanding certificate in her BE on her behalf. And I learned from her. And so I carry that with me. That sense of power, that sense of belief, and that sense of purpose in everything that I do. And there you see in that picture, there she is with me with my Chippendale slippers. And later on as a, as a 12 year old, that. That's me when I was 12. And so one of the things, the first thing I did in this industry in my path towards success as a renovation consultant is I opened a home inspection company back in 1994. And one of the USPs of my company was that all home inspections were performed by FHA 203k consultants. Everyone in business should have a USP, a unique selling point, something that separates you from your competition. And that was it for us. We were all 203k consultants. We got a grant with the federal government to perform home inspections for people who were getting first time homebuyer loans. In order to qualify for these loans, they had to have the property meet federal minimum property standards. I learned all about FHA MPS because I had to create an MPS checklist in addition to every home inspection that we provided for every client. So my glasses are glaring up. Sorry. I might just take them off. Okay. I can't see, but you can't see the glare. So I'll be all right. I know this stuff by heart. I should be okay. And this Grant lasted for 10 years. And really my company just bloomed. We went from two inspectors up to five. We were getting. We had a government contract. It was basically $75,000 a year back in the 1990s. That was huge up until 2005 when guess what happened? The mortgage meltdown. So when we had the mortgage meltdown, guess what else happened? The loan. The grant died. The grant program ended just at the time when everybody else was suffering for business. I had to find a way to grow my business after having received inspections from a fax machine. I hadn't had to do any marketing. I hadn't worked for it. It just came over the facts. Now I had to grow a business. So I took this expertise in 203k consulting. I took this USP, as we called it, and I partnered with a lender. Now let me give you a clue. Once you start learning your skills as an FHA consultant, once you start letting people Know, lenders will want to partner with you because they want to get the word out just as much as you do. So I partnered with the loan company Keystone Funding, and together we formed a real estate school so that I had a way to get in front of audiences of 15, 30, 50 agents at a time teaching CEU classes. So I created an entire curriculum for the 16 hours that they required in the state of Pennsylvania to get ces. And I was the one person standing up in the front of the room teaching them about what a home inspection should be, what are environmental studies, what is a 203k, what is an energy efficient mortgage. All the things that real estate agents needed to get information on, we were able to provide in the form of CEU education trainings. So with that being the basis education, my company did not suffer during the meltdown because we had agents looking at us as that unique expert that could provide them a resource that no one else could.
Now, how did I figure this out, how to do this? Well, like many of us, most of our success is built upon the success of someone else. And for me, I had a mentor. I have several mentors, actually. And my one mentor said, you have multiple inspectors in your company that you're able to train to become FHA consultants. How do you do it so successfully with such rapidity, such ease and quickness and such repeated activity? And I said, oh, I have this box with all the stuff that I learned and studied and how to become an FHA consultant. And whenever I hire a new inspector, I just give them this box. And that is how 203k in a box FHA consultant training and Marketing System was born. And now today, we have trained hundreds of home inspectors and contractors to become successful renovation consultants. And because we have so many people trained the same way, being successful the same way, lenders looking for the fact that they've been trained in this same model, we decided to form the national association of FHA Consultants. This is the only nonprofit association dedicated to the success and the support of all those involved in the world of renovation consulting. And that is where we are today. So with that background, with that experience, and with the fact that we were all wanting to do things the same way, with the same level of professionalism, the same highest quality of competency and consistency and community. The three Cs of NFAC, what the next step was for us was to create our own software, the Genesys Rehab Reporting Project Creator. With the Genesis project creator, we now have the only web based software that is created by and for FHA consultants that allow the loan officer, the borrower and the contractor to dial in and log in directly online to navigate and assist with the creation of the work. Write ups, the phase construction draw, the bidding process, everything is automated, 100% paper free. Yay. Save some trees. So that is who I am. And that is why many people today call me up and look to me to say, hey, can you recommend a consultant who can help me in Bluff, Idaho? Can you help me find a consultant in Reno, Nevada? And thankfully, the answer is yes. But sometimes the answer is no. Sometimes there are parts of the country that we haven't yet been able to touch that we haven't been able to get the message out. And that is why we are holding this series of educational sessions to help get the word out about the NFAC way of consulting and the mission that we have to spread the quality, the competency and the consistency to every parts of these wonderful United States. And so that's who I am and that's what my goal is for being in front of you today. So if that gives you a little bit more comfort to listen to me, let's dive in. Okay, so the FHA 203k rehab loan, like I said, I know this like the back of my hand. I have been dealing with renovation loans since 1996. I can't tell you how many 203k projects I've completed. I think close to about 8,000. I think 8 or 9,000, not including draw inspections. I won't even count the number of draws because mostly of all, most 203k project has at least 3 to 4 draws. And about 80% of the projects I've done work write ups on went into the draw stage. So I'm not even counting that money. I don't have to. So with FHA 203k loans, the most important thing to understand that it is a program that's designed for owner occupancy. It's meant for the person who is getting the mortgage to live in the home. Now, on my NASPAC Facebook page, NFAC 203k and I hope you'll friend us there. We had a contest where I asked the question, what is the amount of time that you must live in the home as an FHA 203k borrower before you can rent it out, before you can make it an investment property per se? And not many people have the answer. The answer is one year. But after six months of ownership, after six months of having that loan, you can refinance out of the 203 loan into a Fannie Mae loan and be able to eliminate that owner occupancy requirement and be able to do whatever you want with the property. So a lot of people will refinance out of the 203 after six months of owning the property. And in many cases the rehab is just concluding at six months. So the timing is perfect. Another important thing to know about the FHA 203 loan is that it has very liberal and easy credit and down payment requirements. With the FHA 203K you can get a mortgage with as little as 580 credit score. You're going to have to shop for a lender and you're going to have to meet some other prerequisites. Most lenders don't touch a customer unless they have at least a 610, 400 203k for an FHA loan. But the FHA minimum credit score requirement, which used to be zero, there used to be no credit score minimum, but three years ago they did put a minimum which is 580. And if you have a 580 credit score on an FHA loan, you can get a rehab loan for as little as 3.5% down. You can see on that gray section it says for a conventional loan with a 580 credit score, you're paying up to 10% or more in down payment. And so this has a very liberal credit and liberal qualifying. Another important consideration about an FHA loan is you can have that 3.5% down. Can be gifted money or something I like to a term that many people know opm, other people's money. You can use OPM with an fha. Lots of alphabets, right? Another thing, and those are some of the wonderful things about 203. A valuable thing about 203k is that you can actually tear a house down to the foundation as long as you keep its existing foundation. And you can call it a rehab loan and rebuild it a brand new house as long as you keep the foundation. So if it had a basement or a crawl space, you can augment that, but you cannot eliminate that foundation. You actually can put a brand new house on top of that foundation and it's considered a rehab. Isn't that awesome? So those are some of the things that a lot of people don't know. You can take a property, a property that is intact, you can relocate it off of its current foundation onto another foundation on the mortgage property and call that a rehab as well. So there's a lot of ways you can use the 203k rehab loan, that makes it a very attractive loan. Some of the things that make it a little less attractive for some people is minimum property standards. The house is going to be held unto a scrutiny because it must meet minimum property standards at the completion of the renovation. So at the very least, the repairs that are included in that scope of work must be those that fail to meet minimum property standard. So for example, if there is an outside outlet that does not have a GFI protection on it, it must be upgraded to GFI protection as a mandatory repair. If the mandatory repairs, including outlets, cracked windows, paint that's peeling, or any of the other things that HUD and FHA appraisers identify must be included as a very minimum. If the cost of the mandatory repairs doesn't exceed the amount of money the borrower can qualify for in additional expense and doesn't exceed the loan to maximum loan to value, then they can add on desired upgrades to the property. So the goal for most borrowers is to have the fewest mandatory repairs, to leave the most amount of money for kitchen upgrades, bathroom additions, hardwood floors, and you get it, the desired improvement. But that's one of the stumbling blocks that a lot of people have problems with when they're dealing with FHA loans and is those mandatory minimum property standard repairs. Another important thing about FHA loans is the contingency requirement. The FHA 203k loan requires that there is a contingency of at least 10% up to a maximum of 20%. And usually that contingency allowance amount is determined by the FHA consultant. If the repairs are over $35,000, then the FHA consultant is a mandatory component of the project. However, the good news is all costs that are paid to FHA consultants are reimbursable to the borrower as a paid on contract expense because it's able to be added to the escrow. So the good news is all the money that are paid to us as consultants comes back to them at closing. So those are some of the reasons the ups and downs of 203k. Another thing that would be considered a down for many people is PMI private mortgage insurance. As of 2014, FHA decided that the PMI must remain with the life of the loan. Another real good reason why people will finance out of a 203 loan after they've reached a certain point of equity, because with other loans it's not that case. So with the PMI, it stays with the life of the loan as long as you're owning an FHA insured mortgage, you must have that mortgage insurance premium. Just like if you have a note on a car, as long as you have the note on the car, you have to have car insurance that names the lien holder as the additional insurer. Only makes sense they have a vested interest in that car maintaining its drivability. You owe on it. But as long as you owe on this house to FHA as the guarantor of the mortgage, they want to make sure that there's an insurance premium protecting their investment. Makes sense to me, but a lot of people do not like pmi.
So I never like to end a conversation on a negative. So I'm going to end my conversation about FHA on a cool part. The FHA loan limits have increased for 2020. And this is a really cool thing because as you can see in this presentation slide here, the loan limits have gone up in almost 85% of the country. Either they stayed the same or they went up. And so here you're looking at the loan limits for Fannie Freddie are $510,000 for a single family or for the FHA 203k for single family. This is for low basic standard mortgages. The rate goes up based upon the conforming loan limit in that area. So not all areas will be 331. In some high limit areas, the maximum loan limit is $765,000 for a single family home. So we're talking about areas like New York City, areas like that that are very expensive to live.
Hawaii, Guam, US Virgin Islands. The numbers are even higher than that. And I'm looking to get some consultants out there so I can go make a trip out there, maybe do 203k discovery days in Guam or Hawaii. Who wants to join me? Raise your hand if you want to have a road trip and have an educational training in Hawaii or the US Virgin Islands. Come on with me, let's go. So as you can see, the rehab loans are allowed to be up to four family dwellings. And with that being the case, you actually can have an investment component in that the borrower has to live in one of the units. But up to three additional units are able to be used as investment properties and you're able to renovate all three units. All three units must meet minimum property standards. So this is a real great opportunity. So you can see someone in. And I'm actually working with a client in a very high limit area. He's doing a 203 rehab and the rehab is in Brooklyn, New York. The rehab cost for the four family dwelling is $1.4 million in rehab. He is a very happy consultant because he's doing a lot of work for this customer and he's going to be paid a very worthwhile, reasonable amount of money just on that one project. So I am looking at. We have a couple people who said yes, count them in. That's Yari. You guys will meet Yari especially when you come to the 203k discovery days. She's our general manager. She is our social media expert and she's on the line here to answer any questions that anyone might have in the chat or to respond to anyone having difficulties logging in. Thank you, Yari.
So let's go into a little more depth about the 203. There are two different forms of 203 loans. There's the standard 203 and there's the streamline. Now, the streamline, 203k is no longer called streamline, it's called the limited. Now, I put up the word streamline because, believe it or not, I still have real estate agents and lenders. Not so much lenders, but some real estate agents still calling it a streamline. Please, please, please fix your verbiage. It's not a streamline anymore. It's called the 203K Limited. So scratch that out. I'm not going to try to write the word limited. Oh, this is going to be ugly. You get the point. This worked better in practice. Limited. I'm not right handed. I'm left handed.
Okay. This is painful to watch. There you go. Okay, so it's the 203k limited. So let's look at the difference. With the 203k limited.
You have. With the 203k limited, YOU repair. Excuse me. With the 203k full, let's turn this off.
All right? Repairs, improvements must be at least $5,000. With the Limited, there is no minimum repair, but they can only go up to $35,000. With the full 203k, there's no maximum up to the total loan limit, but there's a minimum of 5,000. With the 203k standard, an FHA consultant is required. With the limited, it is not necessary for a consultant with the full, architectural exhibits, if required, are included as a component of the rehab project.
More from Catherine
Getting last minute details ready for the 203k Discovery Days just 5 days away!
Savvy real estate pros are attending the 203k Discovery Days Livestream event 2/25-26...are you?