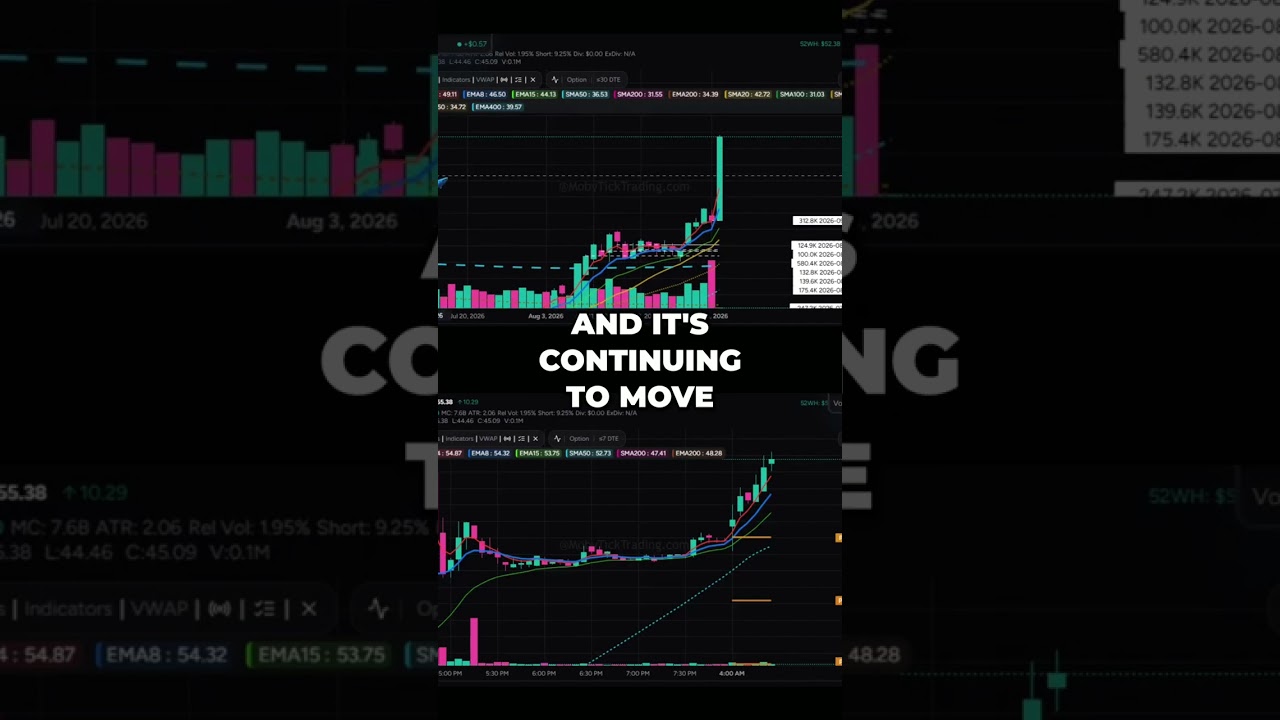
Dave Barnhart explains open interest as the count of live option contracts at a strike price, and why converting to share exposure (contracts × 100) matters for spotting dealer hedging activity. OI shows where price friction concentrates but doesn't reveal who's long or short, or predict direction. It loses relevance after expiration and for same-day contracts, where volume takes over.
Chapters
There's one column on an options chain that most traders scroll straight past. It sits next to volume, it doesn't move much during the day, and it looks boring. It's open interest. And it's arguably the most useful number on the entire screen because it's the only one that tells you where positioning has actually built up over time. Here's what it is, what it definitely is not, and how to read it on a chart. Open interest is the number of option contracts at a given strike that are currently open. Contracts that were bought or sold and haven't been closed out or expired yet. That's it. It's a running count of live positions. When a new position is opened, open interest goes up by 1. When a position is closed out, it goes down by 1. If one trader simply sells their contract to another trader, it doesn't change at all. The position just changed hands. The number people confuse it with is volume. So let's separate them cleanly. Volume is how many contracts traded today. It resets to zero every morning. It's traffic. Open interest is how many contracts are still parked. It carries over from day to day, building up or draining down. It's the parking lot. A strike can have enormous volume and almost no open interest— that's day traders passing through, in and out before the close. Or it can have modest volume and a mountain of open interest— that's positioning somebody built up over weeks and is still holding. The parking lot is what matters for the levels we're about to look at. Here's why the number gets big fast. A standard equity option controls 100 shares. So the contract count isn't the real number; the share count is. Say a strike shows 50,000 contracts of open interest. Multiply by 100, and that strike represents 5 million shares of exposure sitting at one price. That's the translation to make in your head every time you see an open interest number. Contracts times 100. Because shares are what actually get bought and sold when somebody hedges. And that's the connection to the last video— every one of those open contracts has a dealer on the other side of it, and that dealer has hedged their exposure with real shares. So, a strike with heavy open interest isn't just a big number on a table; it's the price where the largest amount of hedging activity is concentrated. When price moves toward a strike like that, Hedging gets busiest right there. That's why it behaves like a level instead of like empty chart. Heavy open interest above price tends to act like a ceiling. Heavy open interest below price tends to act like a floor. Those are what get called call walls and put walls. Now the part that almost nobody says out loud, and it matters. Open interest does not tell you who's long and who's short. It doesn't tell you whether those contracts were bought or sold to open. A stack of calls at a strike could be traders betting on a breakout, or it could be somebody selling covered calls against shares they already own. 2 completely different intentions, identical open interest number. So be careful with anyone who reads a big call number as everyone is bullish here. That's not what it says. What it does say, reliably, is that a lot of positioning is concentrated at that price, which means a lot of hedging is concentrated there too. That's a statement about where the pressure is, not about which way anybody thinks the stock is going. So, how do you use it? Picture a stock at $100. Above it, a large stack of call open interest at $105 and a smaller stack at $110. Below it, put open interest at $95 and a smaller amount at $90. That gives you a map before the day starts. $105 is where a rally is most likely to stall, 95 is where a sell-off is most likely to find a cushion, and the space in between is comparatively wide open— less friction, so moves through the middle can travel faster. Size matters more than location. The single biggest strike is the one that behaves most like a wall. Smaller ones are speed bumps. 2 situations where open interest quietly stops helping. The first is expiration. Once those contracts expire, the positioning behind that level is gone, and so is the hedging. A level that mattered all month can simply stop mattering the day after expiry. Levels have a shelf life. The second is same-day expiry trading. On contracts expiring today, positioning is being built and unwound in real time, within hours. Yesterday's open interest is already stale. In that world, you watch volume instead, because volume is the live picture and open interest is the old one. That's a full topic on its own, and it's coming later in this series. So, to recap. Open interest is the count of contracts still open— parked, not traffic. Multiply by 100 to get the share exposure that has to be hedged. Where that exposure concentrates is where the friction sits, and that's what turns a strike into a level. And remember what it doesn't do. It won't tell you who's long, and it won't tell you where price is going. It tells you where the pressure is. MobyTick reads open interest across the chain and plots those concentrations as levels directly on your chart, So you're looking at the map instead of the table. Next up, Delta and Gamma— why dealers hedge in the amounts they do, and why that hedging speeds up as price gets closer to a level.