TF4: Enterprise Branded Currencies - What is after Libra?
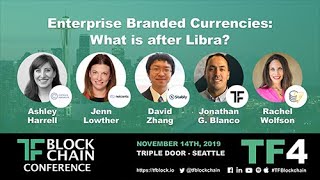
In a recorded panel at the Wonderful conference, moderator Rachel Wolfson leads a conversation with Jonathan (retail tech veteran), David Zhang (co‑founder of Stably), Ashley Harrell (Celsius Network), Jen Loether (CRO of NetSense), and others about the future of enterprise‑branded cryptocurrencies after Facebook’s Libra project. The panel explores how large firms may issue their own tokens in stages, beginning with companies that face high‑cost, cross‑border payment frictions. They contrast closed‑loop loyalty points with open‑loop digital currencies, discussing trade‑ability, secondary markets, and the blurring line between gift cards, loyalty points, and branded tokens. Government digital currencies, especially China’s CBDC, are examined for their efficiency motives and the potential for pervasive transaction monitoring. Privacy concerns surface as speakers note how data tracking, advertising, and blockchain could both empower and surveil users. The discussion highlights corporate incentives—reducing payment costs, increasing customer retention, and capturing data value—while acknowledging regulatory challenges and the appeal of Bitcoin’s decentralised, private nature. Real‑world examples such as Facebook/Libra, JP Morgan’s blockchain trader certification, Starbucks loyalty, Uber, and Amazon illustrate the strategic considerations for future enterprise token initiatives.
Chapters
All right, we're going to have an interesting panel up now. We're going to talk about enterprise-branded currencies, what's going on after Libra. If I could invite my fellow panelists, David Zhang, Ashley Harrell, Rachel Wolfson, and Jen Loether.
Come on up.
Thank you everyone for being here today, and thank you to Jonathan for organizing Wonderful conference. We've got a good crowd. So my name is Rachel Wolfson. I'm a journalist. Most recently, I was writing for Forbes. Now I'm with Cointelegraph. And I also host a podcast called The Crypto Chick, which is part of the Bad Crypto podcast. So I'm moderating this panel today. It's entitled Enterprise Branded Currency: What Comes After Libra? And we've got some great panelists up here, which I'll have them introduce themselves, starting with Jonathan first.
You already know me. Sorry. The reason I really want to be on this panel, I've been in retail technology for the last 15 years, worked in loyalty and payments and rewards, attempted to start a company in the loyalty retention rewards space leveraging blockchain and cryptocurrency. Didn't go the way I wanted it to go. In hindsight, I wish it would have been focusing on Bitcoin as opposed to our own token. That was a lesson for us.
Hi, I'm Jen Lauder. I'm the CRO of NetSense. My background is bringing new products and technologies to market.
Hey everybody, I'm Ashley Harrell. I'm the Director of Operations at Celsius Network. We are a mobile app for users to deposit their crypto to earn back interest and take out US dollar loans. And I'm really looking forward to this discussion today.
And I'm David, co-founder at Stably. So we're a company that's trying to disrupt financial technology by leveraging cryptocurrency and blockchain. You may recognize us from our first product, which is called USDS, which is a US dollar-backed stablecoin.
Great, wonderful. Okay, so as everyone may know, enterprises are starting to come up with their own cryptocurrencies. So the first question is, what companies or brands do you think will have a currency and why? I mean, obviously we all know about Libra, so let's just talk about the other examples like JP Morgan, Amazon, Google, all of that. Anyone can start first.
Yeah. So personally, I think this is going to happen in stages. So I think at first we'll see a lot of companies that have real tangible pain points that traditional financial rails can't solve. Like, for example, Facebook's initiative Libra is likely aimed at a lot of their consumers that don't have access to the US financial system. And by launching this sort of more open transaction layer, they're hoping to reach their customers that are using WhatsApp and other products that perhaps are not as US-centric. And I think as time goes on, we'll see as the friction of integrating blockchain goes down, as more and more users have wallets that support cryptocurrency, I think we'll start seeing any company that has a substantial network effect look into how they can leverage this sort of open finance to either reach more customers or reduce friction for their customers.
Sorry, is there something we can do with the feedback?
Yeah, are you guys hearing this like— All right, is this better?
Okay, are we good?
I think we're good.
Okay, great. So let's just continue with the conversation.
I love everything that you're saying, and I do think that we're seeing a replication of what happened with the early days of the internet. Everyone thought it was crazy to develop all these new websites, and Even with the surge of ICOs in 2017 and 2018, we began to see so many coins coming. And of course, it's ultimately all these big corporations want to get a piece of that. So it's going to be really interesting to see how this plays out, what kinds of technologies are actually supporting these currencies, and are they actually revolutionary or are they just replicating finance? Rather than disrupting it. And I'm really curious to see more and more big companies coming to the space because in general it's going to increase awareness in the public. And I do think that this is a very interesting sector that's still a very small pool of people involved. So if the byproduct of some arguably, you know, dirty companies getting involved is that more people become aware of this and do their own research, then ultimately that could be a very good thing for our space.
When you look back to your original question is what companies does it make sense for? Payments are expensive. Cross-border payments are a logistical nightmare. I'm Canadian, spending money down in the US is prohibitively expensive to the point where I've actually set up US banking. So, the companies that it really makes sense for are do high volumes of payments, have large user bases, and really deal with a lot of international transactions where it's either cost prohibitive, they're having to integrate multiple payment rails, and they're needing to get everything back to a base currency. And so then you've got multiple conversion events, payment rails, and points along the way that slow down the transaction and add to the overall cost of the transaction.
Yeah, I definitely want to echo I definitely want to echo what you're saying about the rails, right? And so especially from a loyalty perspective, when I think of Libra, I'm actually a fan of Libra in theory, right? Like, you know, I wouldn't use it, I wouldn't use it as store of value and so forth. But as far as in-network currency, to me it's super fascinating, super interesting. I think they made a really big mistake in creating this big overarching goal of we're going to be a replacement currency essentially. The easier way to call that would have just been, hey, we're a loyalty program for Facebook.
Facebook users.
And so when I think about Libra, or I think about the things that you're all saying, is what would loyalty look like today if we didn't have to rely on all the rails from the past, and we just went ahead and just started fresh, and it's basically, you know, a branded currency?
Right.
And you bring up a really good point, because it's like, what is the difference between these cryptocurrencies and a loyalty point? I mean, I was recently speaking with an executive at IBM Blockchain, and she mentioned that they're thinking of doing something to have a loyalty program. So what are your thoughts on that? Like, what are the differences between these digital currencies and loyalty points?
So there's really two key things there. One, is it an open loop system or a closed loop system? Or does it only work in your ecosystem? Think Uber Cash. It's not a cryptocurrency, but I load my money on there and I use it until I deplete it and I get 5% or 10% or whatever it is off my Uber trip. Or is it an open platform that can be used outside of that ecosystem? And that really to me is the difference between loyalty with a discount and a currency that you can use. There's really not a lot of point in developing a cryptocurrency that you can only use in your ecosystem because as a user now I have to transfer my money in, buy your coin, I can only spend it with you and if I want to do it, I now have to take it out and convert it to another currency. I understand why a company would want to do that and own the entire end-to-end of the ecosystem, but it really is like AOL internet again, where the internet is the internet that AOL says exists. It's a walled garden approach.
I think it's also quite interesting when we're talking about the ecosystem that, like, you know, Libra functioning within Facebook. If you think about Facebook, I mean, it's a marketing company. They make all of their money on advertising. So if you really think about what are they spending on or where are they losing profit, it could be in all of the remittance that they have to deal with. And, you know, my company spends a lot of money on advertising, and I see the, you know, charges going out every single day. So if Facebook is able to use their own in-house or like point system or whatever you want to call it, they're actually going to be saving billions of dollars by doing everything in-house. So I think that there's definitely an ulterior motive here. I mean, we can definitely talk about banking the unbanked and trying to bring easy payment systems to the entire world, but there are other reasons that this is happening.
100%.
Yeah, I mean, oh, excuse me. I think one of the biggest distinctions is, you know, like secondary market tradeability, as was, you know, said earlier. I think one of the, you know, actually even right now there is this distinction in existing, like, you know, retail, right? You have gift cards and then you have loyalty points. Gift cards you can trade by selling to another person, sometimes at a discount, but loyalty points are typically tied to your account. And I think that sort of distinction might blur down the line as, you know, companies start issuing more branded currencies that have benefits inside their ecosystem, but can also be traded for cash or other companies' dollars, so to speak. Or we could see this distinction continue to stay and have companies leverage blockchain and cryptocurrency just for replacing gift cards and store credit. So I think that will depend on the company's strategic approach, and I think I think only time will tell what will happen.
Great.
Okay.
Another interesting point that I wanted to bring up is China. So it's constantly in the news now. So as a journalist, of course, I'm interested in this. But what are your thoughts on their digital currency or cryptocurrency that they're creating right now? And where do we think that's headed?
Yeah. So personally, I think a lot of these government initiatives is really about efficiency and governability, right? So the dream currency for a company is basically one that they can control with more fidelity, but also one that its citizens and the global economy can trust and actually use. And I think that's the initiative that any government that tries to launch its own stablecoin is gonna try to go after. Like China, for example, they're almost definitely going to build in lots of controls because there's already capital controls, etc. And this is just a more streamlined way to do that. Because unlike cash or other things, you can actually monitor every single transaction that happens in the network if you wanted to. So whether it's a good thing or a bad thing, I'll leave up to you, but I think that's likely the direction we'll see them taking.
I'd also echo that sentiment. One of the great things about cash is I can go buy a latte, and if I'm not doing a loyalty program, no one knows who I am and what I'm doing. When you get governments, particularly ones like China that control the population, if you could tell where they spend every single dollar, and then you add into that the social score credits about who's allowed to travel or not, in a case like China, it really comes down to another factor where they can control their population. Which, when we talk about both enterprise currencies and the government ones, it really goes against what cryptocurrency is. It's taking back control of your finances, your bank not being able to tell you, sorry, you hit your spending limit today, come back tomorrow. And what we're seeing with these corporations and governments getting into it is trying to co-opt this next evolution of money and take control back and actually putting more control in place of the overall populace or consumer base?
Yeah, I think people forget that it's in a country's best interest to basically have rule over its citizens, right? And so there's a certain amount of freedoms, yes, that we all have. But when you start thinking about how an authoritative government works, it's to the benefit of that country to have hyperinflation. It's to the benefit— sorry, it's to the benefit of the— is that it? Maybe I just have to lean back. It's basically to the benefit of those in power in an authoritative government to have hyperinflation, to have controls like everybody here has said. And it's maybe like a double-edged sword when it comes to blockchain is the fact is, like what you're saying, Jen, about all the traceability aspects. And then when you start putting hooks and levers on folks for how that works. To me, that's actually what makes Bitcoin so interesting and continuously interesting, right? Is the fact that now you have this self-sovereign for a currency that is independent of a country's rule, right?
So, yeah. I think that it's a little alarming Personally, I just, from a human rights perspective, it can be a little scary to think what blockchain has the capability to do. And I think that this needs to be a strong message to all countries to consider, like, how are they going to utilize blockchain technology or possibly introduce their own government-endorsed digital currency? Because it's almost like the new space race. And I think that we need to to take, you know, what China's doing and look at that and to consider— I'm speaking of we as Americans, I know you're Canadian. But I think it's a strong signal that regulators, and I know there's gonna be a panel on this later on regulation, which I'm interested to watch, but really need to work very hard with existing blockchain and cryptocurrency groups to establish clear guidelines of how we use this technology going forward with our own currencies in the United States. And I'm really interested to see how this plays out. But it's also kind of like watching an episode of Black Mirror. So it's a little scary.
And circling it back to Libra, the Congress's initial knee-jerk reaction is to stop it. We're losing monetary control. So Facebook has what, about 3.2 billion active users? If even just 10% use their coin, that's almost the population of the United States. They then become equally as dominant as the US government in global financial policies. So you don't need to look at a government like China to see governments really quite scared about losing that monetary control. Control and all of the regulations that they're starting to put in place. Should it be completely unregulated? Absolutely not. But you can see the government's fear of what we are doing today.
Right, exactly. And I think that privacy and protection of data comes into play with all of this, with China, with Facebook, with all these digital currencies that enterprises want to create. What are your thoughts on that? Privacy in general.
And so privacy is one of these things that you swing back and forth, and the statement you often hear is, I have nothing to hide. But privacy— I don't think people realize just how much of their lives people track. I remember when the Cambridge Analytica scandal came out. My background's in digital marketing. I'm like, what did you think they were doing? So we are absolutely every day giving up pieces of our privacy and our data, and at what point do they have such a holistic photo of what we're doing in our lives that we don't need to file taxes anymore? Because they're just going to go, you've done this, you've spent it on this, this is your tax bill, don't bother telling us, like we're actually tracking all this. We're really not that far off. So taking back control of the privacy, things like Bitcoin that's private and they're not going to be able to trace it back to you is really important in this day and age as we have beacons pinging our phones and everyone knows where we are.
It's also an opportunity for a company like Facebook to see where they're closing the loop on their advertising and your browsing every single day. So if you're seeing certain ads on your feed and then you're clicking on them and then you're paying for it with a Libra in-house currency. Oh, they're already doing that.
You don't even need the currency.
Yeah.
They actually have offline tracking. You've seen an ad, you go into that restaurant and pay, they know, they already know without the currency.
But I mean, they don't know if I walk into a store and pay cash.
They know that you've gone in and done it. This is actually something that we've been— We're living in Black Mirror. I was out with a girlfriend and we were talking about it the other day and she got, they were having problems completing that loop, so they got put on the phone with a Facebook rep and now they know the number of people that have seen the ads, have walked in, how long they've spent spent in their restaurant, and they might not know the exact dollar value of what they've spent, but they're tracking back their ad spend to the length of time in the store.
Leave your phones at home, guys.
Well, and what becomes interesting with that too is that's just going to continuously evolve and evolve and evolve and evolve. There's so much you can do with merchant data. There's APIs like Plaid, which just pull your payment history and then make connections there. So what becomes interesting now is the concept of participating in that, whether that be financially reward-based or whatever. It's like, hey, I'm aware that you're taking and mining my data. Let me at least participate in the value creation that you're getting out of that. And that's really, I think, where we'll start to see people go. With Brave or some of these browsers where you're earning tokens for doing things, it's because you're participating in that value. The other thing though is that we're so privacy fatigued. There's times where like, oh, give your email, give your this. You're like, okay, fine. I need to get in there. So it's this weird balance.
And it links back to the loyalty rewards. It's like, yeah, I'll take that 2% off. I'll give you all my data for that 2%.
Totally.
For a Jimmy John's sandwich.
Right.
Well, so on those points that we just made, why do you guys think that enterprises aren't just want to keep Bitcoin.
Again, closing the loop, they're holding as much of the pie as humanly possible. And as a CEO of one of these companies, it makes all the sense in the world. Why wouldn't you want— when you're talking about trillions of dollars in transactions over 5 years, a fraction of a percent matters.
Yeah, I think again, it gets back to like the on and off ramps and like how do they actually pay their bills and. And if it's an in-house currency, that really solves a lot of issues for them. Because, you know, if they're going to have to constantly be converting Bitcoin, that can get very expensive for a company like Facebook.
Yeah.
And I think a lot of, you know, the why— so, you know, volatility and scaling issues aside, I think a lot of the why not Bitcoin question can be applied to like why not dollars, right? Companies will almost always prefer their own in-house because they get cash flow upfront that they can spend on, they get some level of guaranteed spend by consumers, and they get some level of retention because customers have to come back and spend in their network. And I think the same reason why companies would want to issue their own cryptocurrency rather than rely on one of the open cryptocurrencies like Bitcoin is for those exact same reasons. And of course, you have the added complexity of dealing with something that your regular everyday spend is not denominated in, you can't pay your employees in it yet. So there's also a lot of other logistical issues that come with it, but even beyond that, if those were solved, I think governments would still— or I think companies would still be incentivized to have their own issued currency if they were big enough.
Right, wonderful, good points. We're going to open it up to questions from the audience. So does anybody want to come up here on stage and ask a question?
Or should we write down here who all left? We'll take two questions, whoever can make it over here.
What do you guys think about JP Morgan's move to have their coders certified as traders? I'm going to pass that to the CTO.
So personally, I have—
So real quick, let's repeat the question. So it was—
Oh yes.
Go ahead.
So the question is, what do we think about JP Morgan's move to have their coders for their blockchain stuff certified as traders? Was that the question? Yeah, so personally I come from a bit of a finance, math, and technology background, so this is very near and dear to me. I think when it comes to blockchain and cryptocurrency specifically, there's a lot of issues that as a math or a coding person you don't think about, because there's a lot of behavioral economics or just general incentive and game theory issues that the coding doesn't come up, right? Like you can't write unit tests that tell you how a person is going to act in this ecosystem or this incentive scheme. So a lot of the failures that cryptocurrency projects see is not a failure of technology, it is a failure of sort of anticipating how greedy actors are going to act in a system. So I think it makes a lot of sense.
And for time, let's try to answer this last question in a minute. Go ahead, Carl.
So probably the interesting thing to look at is how chat apps combine with mobile wallets in order to provide this type of mobile payment. That's how mobile payments are scaling, because I helped to enable mobile payments in China. Here's the problem. Mobile network operators and banks—
Carl, for time. OK, here's the question.
Here's the question. What do you think about Starbucks? Because they had the best loyalty app on the planet in the United States for payment. What do you think about Starbucks adding blockchain and then loyalty and then other things like cryptocurrencies? It seems to make sense. What do you think about that?
Yeah, I mean, it makes a lot of sense. Just like Uber, just like Amazon, just like Facebook. Anyone that's got a large enough user user base that processes enough money, it does make sense for them to try and want to keep people going to Starbucks and not the coffee shop next door, while bringing their cost of payments down. I think we're going to see a lot of these large enterprise companies play with it, try and figure it out, how to keep their user retention up, all while bringing their costs down, increasing their bottom line. At the end of the day, these companies want to increase their bottom line and profit to the shareholders.
Facebook and Starbucks work together.
Well, I think that's why Facebook did— Facebook was really smart bringing out the coalition of companies, bringing them in so that it did open it up more to just the Facebook platform. That starts to make more sense than just one because it's a semi-closed ecosystem at this point. But goes back to my earlier statement. Bitcoin is supposed to be private, supposed to be anonymous. It's supposed to decrease friction and make life easier rather than trying to tie you in to a single ecosystem.
Great.
Wonderful.
Well, thanks so much to our panelists and to the audience for listening. And yeah, wonderful.
Thanks so much.
More from David

Interview David Zhang - From a Software Engineer at Amazon to the CTO & Co-founder of Stably