From $1,800 to $5,600 Cash Flow - Lifetime Income Planning & Mortality Credits
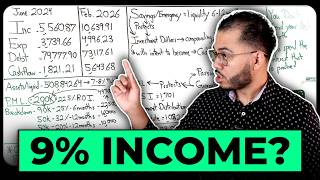
Denzel Rodriguez shows how a 68-year-old client nearly tripled her monthly cash flow from $1,800 to $5,644 in 20 months through private lending, annuities, and mortality credits. He argues cash flow, not net worth, should drive retirement planning, and demonstrates how a $200k annuity could guarantee $1,500 monthly income for life.
Chapters
I'm going to share with you a case study today, which I absolutely love because this is a, this is someone in our community. This is a client of mine, someone I've worked with for just a short period of time. We've only been working together since June of 2024. This is a perfect textbook scenario of what cash flow over net worth looks like in real time. So these are real numbers, real case study, real situation. This is a single mom, someone who, when I first started working with them, they were 67, 68 years old. They turned 70 this year. So any excuses I get, whether it be from you people catching the recording This woman here eliminates all that because this is an everyday woman, did not come from money. This woman does not have, uh, entrepreneurship experience for God knows how many years. This person's not a content creator, not a famous YouTuber, doesn't have a huge following, none of that. This is a mom who's committed to creating wealth. For herself, for her family, for the Kingdom of God here on earth, and to be the example that God wants us to be as his royal citizens, as his children. We are to be examples in our faith, in our health, in our finances, in our relationships. Okay, and many other things, finance being a big one, because in America, specifically in America, in order to have great health, be in shape, have healthy relationships, surround yourself with positive thinking people, you're going to need money. No Christian should be afraid of money. Money is a tool. It has no authority over us because you and I are kings and queens. No authority whatsoever. So when we come into this way of being, this way of thinking, "I am a king, I am a queen, I am part of a royal family, I was made by the Creator of the universe to fulfill his will," for me on earth with the limited amount of time that I've been blessed with here on this planet. It's our duty, it's our obligation to be successful kingdom entrepreneurs, to be successful kingdom builders, whatever language you want to use. At the end of the day, here we go, case study for you. Take this, take your notes, see where you align. Maybe this gives you an idea, and this continues to shape the way you think about cash flow over net worth. Again, many of us are trying to hit a certain amount of money. Denzel, I need $1 million, I need $2 million, I need $3 million, $4 million to retire. And when in reality, you need a certain amount of income, cash flow. 'Cause at the end of the day, you don't spend your net worth. What do you spend? You spend the interest that is produced. For if you spent your net worth, you're creating the possibility of running out of money before you die when you spend your net worth. Because what that means is if you're spending your net worth, that means you're not earning enough. In your net worth. So, so your mind will go, well, I need more net worth, and that's the wrong thinking. That's what's got so many baby boomer and Gen X generation in the pickle that they're in today. And it's not necessarily your fault. And we went through this, we went through this in the previous session where I said in the United States we went from defined benefit plans with pension plans and payouts that provided you lifetime income no matter what. Went from defined benefit plans to defined contribution plans where you and I, for the last God knows how many years, probably since the early '70s and '80s, that we all started just contributing to retirement accounts with our employer. So what happened is all the risk was transferred from the corporation and banks to the individual. You, John, Louis, Dexter, Ruben, Sean, Denzel, we are now all personally responsible for our own retirement. That was the switch, the major switch that happened around the '70s and '80s with the introduction of the 401 contribution plans. Prior to that, it was your employer's responsibility to provide you with a pension so that you could retire after you worked for 30, 40 years, whatever it was, and you're able to live a happy life in retirement. Baby boomers were the last generation to experience that, and then it still trickles into Gen X based on what career you went into. So if you work for the government, if you work for the, uh, teachers retirement system, if you work, uh, you're a firefighter, you're a police officer, you're military, political world, that Or you work for a major, major institution that still provides pensions, then you're, you're pretty blessed. I've never met a single person that did not like their pension. Okay. And so what does a pension do? Pensions provide lifetime income. Retirement plans don't necessarily provide income on a guaranteed basis, but we Since it's now our responsibility, we gotta learn how to do that. And we don't have to become experts. You just gotta know the framework, the principles, and then you pair that with a financial professional that also understands those principles and you allow them to do the math for you. Basically, we provide our situation, our numbers, and they're able to come back and give us a plan that solves for lifetime income. So person here on the board, female, 68 years old, June 2024, started working with Denzel. Income was at $5,560.87. Expenses are $3,700. Debt just under $80,000. Cash flow $1,800. Between June 2024 and February 2026, notice the difference. Income has increased to $10,639.91. Expenses have increased just under $5K. Debt still relatively the same, around $73 grand. We now have a cash flow of $5,643.68. Not bad at all. How did that happen in such a short window? It wasn't through net worth accumulation. Here's a breakdown. Of this person's financial portfolio as of today. We have a little over a half a million dollars in retirement slash investment slash cash accounts, all of which is relatively liquid, available for income distribution. A half a million dollars. So if this person was to distribute income of $500,000. So let me— I use the exact numbers that I showed, $508,842.64. According to Morningstar, as of 2026, the safe withdrawal rate from your financial portfolio is 3.9%. So For my mom here on the board, her half a million dollars is only going to safely produce her $1,653 per month for the rest of her life without necessarily running out of money, as long as she earns above and beyond 3.9%. Makes sense. So she has to earn a net 4+ percent so that the principal never runs out, so that her money never runs out. She's just spending the interest, a portion of the interest. The ideal scenario is that this money would be averaging 7 to 8+ net, net Not gross. If you're earning a gross 8% and you don't know what your net is, that can put you in trouble as well in your financial portfolio. So if we say 7 to 8% net increase in this retirement account, that would mean their gross is probably 10, 11, or more percent. So if you got a nice solid 7 to 8 net percent rate of return, and you're withdrawing 3.9%, you're never gonna run outta money. Make sense? Cool. So of that $500,000 that's sitting there, if we were to try to figure out how much money would we need to have in net worth to produce the amount of money that she would need to live off of for the rest of her life? Let's figure that out. So far, we have different passive income vehicles. I'm not gonna count her active income. I'm only going to count her passive and/or guaranteed income. She has one form of guaranteed income, that's Social Security. So that's $1,701. We then have retirement distribution. Remember how I just got done saying 3.9%? She's distributing less than that out of her total assets. So $1,440 per month is being extracted from this half a million without that number decreasing. We have real estate. This is net, uh, income. $1,082.25. So we have $4,223.25 of secured, relatively secured income. Her expenses are $4,996.23. So we have a small gap that needs to be filled just to What? Cover her debt service obligations, cost of living. We want more income so that she can operate in retirement more abundantly. Now, from her own words, from her own goals, we are looking to produce $15,000 per month. So we're short. So we look at $15,000, again, not counting active income. Do $15,000 minus $4,000, $223.25. We have $10,776.75. That's our gap to fill with passive and guaranteed income for life, preferably. From a guaranteed income perspective, ideally you want enough guaranteed income in your total income to supplement living expense. So cost of living. I wrote out this, this philosophy of cash flow over net worth is what it— this is how it looks like in real, real time is of the money she's now producing. No, notice how she jumped in income. The reason why this happened is she is saving money. To remain liquid in case of what? Emergencies, unexpected life expenses, which life always happens. When you save for emergencies, you're protecting your investment dollars, the money that you allocate toward what? Compounding, rate of return, wealth building. Now, if we only invest for compounding ROI, rate of return, we're gonna fall into a category of nervous retired individuals that are stressing about whether they have enough money to retire on. So to avoid that, we say we invest dollars, yes, to compound, yes, to get an ROI, but with the intent to become cash flow dollars. So if I, so if I put a dollar into an investment, I want that dollar to produce not only increase in value of that dollar. So I, so if I put a dollar in, I want that dollar to become $1.10, $1.20 over time. Yes. But I also want that dollar to spit out $0.50 in cash flow, $0.75 in cash flow, $1.50 in cash flow, $2 in cash flow. In my business as a financial coach, consultant, content creator, insurance agent, referral partner, every dollar I put into this business It has the potential to produce on average based off history now being in business 8 years. I put a dollar in, I usually get $2 to $3 back out. So I have a personal ATM machine where I just insert a dollar. Imagine going to an ATM, boom, give me a dollar, boom, and then it spits out $2. How often would you go to that ATM machine if you start with a dollar and then it— pfft— $2 out? What's your next move? What's your next move? Let me see in the comments. Put a dollar into the ATM, you get $2 out. What's your next move? Yeah, one person comment. Give you a few seconds. And then those catching the recording, you can comment in the comment section as well. That if you're at an ATM right now, you got a dollar in your pocket, you put it in, spits out $2. What do you do? What do you do? I know what I'm doing— putting the $2 back in so that it spits $4 out. And I'm gonna do that over and over and over and over again until I feel comfortable taking some profit off of the cash flow, taking some of that profit and putting it into a cash grow account. So if I put that money in the ATM, keep spitting out more money than what I put in, boom, boom, boom, eventually I'll have tens of thousands of dollars. And then I can say, you know what, I'm going to take some cash flow profit from this investment in this ATM machine. And that's going to create an income for me to pay for my bills and my lifestyle expenses. The cash flow profit can either remain in that cash flow account, or I can put it into a cash grow account in the event someone else comes by, knocks me out, steals my ATM machine. Now I can't go back. See how there's a risk? You see how if— see, some people get too excited and they're not looking around for the enemy. They're too vulnerable because they're putting a dollar in, taking 2 bucks out, 2 bucks in, 4 out, 4 bucks in, 8 bucks out, 8 bucks in, 16 out, 16 in, 32 out, hundreds. You're just doing this, right? Can you imagine doing this? You're building, you're compounding your money. You don't think the enemy's watching? You don't think there's vulnerabilities around you? You don't think someone's like, hold on, get out the way, let Ruben. Matter of fact, gunpoint. Matter of fact, I'mma sue you. Matter of fact, I'mma come after you. I'mma take your money and I'mma take your business. And so if we don't understand the vulnerabilities and risk of that particular investment, we could end up with nothing. Makes sense? So what do you do? Well, with any good financial portfolio, you're going to have zero-risk assets. You're going to have non-correlated assets that continue to go regardless of what happens to real estate, regardless of what happens to crime in America, regardless of what happens to administration changes, regardless of anything. You're going to buy insurance to insure your ATM machine in case somebody steals it. You have an insurance company that says, hey, We're gonna replace that and make you whole in the event somebody steals your ATM machine. We will assume that risk. We will assume that risk for your ATM machine. All you do is pay some dollars of premium. You pay some dollars of premium, and that insures your ATM machine so that you, Denzel Rodriguez, Ruben Rodriguez, Sean Lewis, John Dexter, don't have to hire muscle, security, gunmen, mercenaries to protect your ATM machine. Make sense? So what's happening in America today with the vast majority of Americans' financial portfolios is you're trying to self-insure your financial portfolio, trying to figure out how much I'mma withdraw, how much money I need to make, and you're going about it completely wrong. Messing yourself up. And your enemy to your financial portfolio— gotta know who the enemy is. Your enemy is taxation. Your enemy is devaluation of the currency. Your enemy is inflation. Your enemy is cost of living increase. Those are your enemies to your financial portfolio. So we have to mitigate these costs, these expenses. That's one way to go about addressing the enemy is you mitigate, reduce risk, remove altogether, and increase cash flow ahead of— increase rate of return ahead of inflation increase to live, right? So coming back, recap, started here, $5,500. We doubled our income focusing on cash flow. Not accumulation. The way we get there is we save money, protect ourselves, stay liquid for unexpected events. We're saving, which protects investment dollars. We take investment dollars, which is going to compound, which is going to create an ROI, but with the intent to become cash flow dollars later that we can take as income in the form of passive income in this case for her was private money lending. So her passive income vehicle is private money lending. Her guaranteed income right now is Social Security, which protects passive income, protects cost of living lifestyle expenses. Active income is abundance, meaning This soon-to-be 70-year-old female can continue to actively work in her church, in a nonprofit organization, and she's a certified public notary, so she makes some side income doing that. She wants to continue doing that, she totally can. And that is abundance money, that is excess Cash flow. She does not have to do those things. She chooses to do those things because it brings fulfillment, keeps her active, keeps her healthy, keeps her engaged with society, keeps her as a contributing member to society so that her brain does not rot and she does not just sit on the couch and watch TV all day and watch brain-rotting social media content. No, she is out there in the community, being a blessing, enjoying life in retirement. So let's figure out our gap once more. Do the $15,000 as a goal minus $4,000, $223, $225, $10,000 gap, $10,776.75. Come over to the passive income cash flow producing vehicle. She has $200,000 of capital, not all hers, $200,000 total. She has curated 4 private money lending deals, one earning 25% over the next 6 months, one earning 32%, 20%, 12%. The last 3 over 12 months. Her average rate of return is 22.5%. Now, if she were to take this $200 grand, put it into the marketplace, and say earn the same rate of return, she's still going to have the problem of cash flow because you're not going to want to distribute a hefty amount of money to get to close that gap. That's not going to make sense. So what do we do instead? Well, you take that $200 grand, you put it in an alternative investment asset such as, in this case, private money lending. And in this case, I believe it's through real estate for the most part. These are like mortgage notes, if I'm not mistaken. So these deals are going to produce a rate of return. But what's also happening is while that rate of return is occurring, she is receiving payments every single month on these investments. Let me take a look at my spreadsheet I have with her so I can take a look. Right, so here are the numbers. We got the $90K will produce $22,500 ROI. The other will produce $16,000. The other $10,000 will do $1,200, and the $50,000 will do $10,000. Okay, so in that time frame, 6 to 12 months, $22,500, $16,000, $10,000, $12,000. So we're going to have $49,700 of increase on the $200,000. Now here's where it gets interesting. She receives this increase in the form of payments. So she's now getting 4 payments sent back to her. And I'm just going to tally up that total number real quick for you to save time. So we're getting PML right now. We're receiving $6,016.66 in passive income on $200 grand. $200,000 and add the $49,700 and do 3.9% only gets you $811. You see the difference? So even if you earn a higher rate of return, this is the problem with most Americans, is like, oh, let me just get a higher rate of return. Well, no, you're forgetting about cash flow, messing yourself up. And even if you got a higher rate of return one year, how do you then distribute income to yourself afterwards? So that's the problem that we have, is for us to get to $15K per month, it's gonna take an extremely large amount of money with a safe withdrawal rate of 3.9%, even if you went a couple points higher, to ever get to $15K. But notice how with just $200 grand— and notice how not all that $200K is hers, she's invested some of that with family So some of these returns will go back to other family member. I believe she's investing with her son, that she is now pooling money to get an even higher ROI to compound the dollars instead of just earning them a steady rate of return. We are actively engaged in In an investment, we're not setting and forgetting. We're actively engaged in this investment. This person educated themselves in one area. They built knowledge in one area. They did their due diligence and research. Now they're in execution. The past year and a half or so, doubled their income. If we do this for, say, 2 to 4 years. I was doing some math with her. Let me see if I look at my notes real quick. I had guesstimated, you know, let's say every year you increase the $200,000 by $49,000, right? So $49,000— let's do, do $200,000 divided by $49,700 takes you 4 years to double $200 grand. She'll be 74. So between 70 and 74, let's say she doubles her money. 4 years, doubles, we now have $400K. What she can do now, this is where mortality credits come into play. This is where insurance protection comes into play very effectively. Mortality credits. Let's look that up together, provide that definition for you so that you stay with me the whole entire time. There's no confusion. What is mortality credits? Mortality credits are the additional income payments generated within a lifetime annuity pool when some contract holders die earlier than expected, with their remaining funds redistributed to the survivors. They essentially allow those who live longer to receive higher returns funded by those who pass away sooner, acting as a reward for longevity. So keep reading the mechanism. When you purchase a lifetime annuity like a SPIA or a DIA, your money goes into a pool. The insurance company calculates payments, right? The insurance company calculates the payments based on the assumption that some people will die early. So here we have these insurance companies taking a bet. They're through what's called actuarial science, right? Through actuarial science. And it puts us in a position for us to take advantage of that. Now, let me take a quick break. I got FedEx at my door. Let me take a quick break. FedEx is at my door. Give me one second. Okay, I am back. Appreciate your patience. Everyone can still hear me okay? I think my mic is back on. Perfect. So got the mechanism, understanding that when we put dollars into an insurance company, multiple— so many people are doing that at once. and through actuarial science and through different ages that people will buy these lifetime annuities will allow for your dollars to have more power in the income distribution that you're able to give yourself. All right, so benefits: these credits increase payouts specifically for longer-living annuitants, providing higher income than traditional fixed income investments. They're considered the engine behind guaranteed non-outliveable income in retirement. So we have $400,000 that we've accumulated so far. Come back to whiteboard. We're at $400,000 we've accumulated so far. We're now 74 years old, so 4 years have gone by. Say her expenses gone up $5,500. Let's keep that number the same, $4,223.25. Her expenses gone up $5,500. We need to create more protected amount of income. As she continues to build this cash flow, she has to protect the cash flow. She has to protect her ability to keep doing this as she ages. What happens if something happens to her health? Now what? Then her passive cash flow income vehicle can be impacted because she might need more income to take. And this is what knocks out Americans quite often, is health concerns. So what if we just removed that risk by taking a portion of what we earned and increased the distribution of that money? So let's say $5,500 minus $4,000 2, 2, 3, 2, 5. We need $1,276.75. Let's round up, call it— we need $1,500 to have our guaranteed income protect her cost of living, which is now over here. So we're gonna go with $1,500. So now we Google, go back to research. Gotta love research. Very helpful. So we say, how we write this? Let's do for a 74-year-old female. How much money do I need in an immediate income annuity to provide $1,500 per month in income? So For, it says for a 74-year-old female, you would likely need to invest about $200,000, $230,000 in a single premium immediate annuity to generate $1,500 per month, $18,000 annually. That's based on the 2026 rates. So that's pretty powerful. So we could say, all right. Um, Say we took 200 grand. The number we needed was, was less, right? So I'm being overestimated here. Let me go back to what my number was. So it was 55 minus 4, 22325. We really just need 127675. But when it comes to like taxes and stuff, the number needs to be slightly higher. So that's why I went with the 1500. So let's say from that 4, she doubled her money, 4. Let's say she took $200K from that, got an annuity that spits out $1,500 per month. Now, does she have to pull from here to make that happen? Not necessarily. She could evaluate these dollars in 4 years from now. What did that $508K grow to? She can evaluate some of those dollars, some of these dollars, roll profits of $200 grand to have an annuity, pays her out on a guaranteed basis, $1,500 a month, keeps her, keeps her guaranteed income continuously paying for her lifestyle expenses so that the investment capital dollars can continue to be reinvested to create more cash flow. So notice how the the cash flow is keeping her money up, she's got this $5,000+ in excess. Where does that money go? Either she increases her income— either she increases her expenses because she goes on vacations or she does more things or she spends money, or she pockets that in the investment, rolls it again, keeps going. Either or. So the question then becomes, well, how many times do I need to do that to get to the $15K per month? How long does it take? So in, in this example here, with $200 grand, we got to everything altogether— active, passive, and guaranteed— we're at $10,639.91. I'd be willing to bet with $400 grand or more, we most likely get to the $15K number, or very close when you combine it all together. So in just 4 years or less, we can see $15K on the board. And I'm sure you all watching can also see that very possibility through this one cash flow producing machine, private money lending, which again is not a set and forget investment, isn't— is actively engaged. Into this investment. She's the one doing it. So we very well can see ourselves getting the $15K per month. This is above and beyond what she needs to live, obviously, and it allows her to operate from an abundance position. We leverage mortality credits because the older we get, the higher the distribution is on lesser dollars. Okay, look, do it again. $200,000 times 4% distribution is only $8,000 per year. It's only $666. So she's getting above an 8% distribution. She's getting a 9% guaranteed distribution from $200,000, $1,500 a month. From with— and guess what? We don't compromise the portfolio. The portfolio continues to compound. So when we want to take income from our portfolio, the most efficient way to do that is roll money over in a lump sum, park it in the annuity. The annuity provides insurance, provides guarantees. We're not, we're not rolling money that's compounding to get a higher ROI. Because that wouldn't make sense. Annuities don't produce a high ROI, they produce a high distribution rate. Two different things. When you're solving for lifetime income, you need high distribution, not necessarily high ROI. So this annuity might be growing at 3 to 5%, but she's getting a guaranteed distribution 9 to 10%. More, more so 9 on the 15, and it only required $200 grand to do that. So you see how she can allow this money to keep compounding, roll some of it out, protect income, protect cost of living, allow her passive capital to not only get high ROI because she's actively engaged in it, but it's producing high cash flow, doubling her income. I would argue between now and 4 years, she'll probably triple her income, or by the 4th year, she'll be in a triple income position and actually seeing the cash flow come back to her in the form of payments, which she uses that to experience her lifestyle in abundance in retirement.









