This is a YouTube video titled "How to Fix Your HELOC Setup For The Best Results" created in August 2025. The content is a multi-speaker discussion focused on mortgage and home equity line of credit (HELOC) strategies, specifically addressing issues with refinancing, banking relationships, and velocity banking techniques to optimize debt management and cash flow. The speakers analyze the challenges of coordinating between different financial institutions and provide advice on improving the HELOC setup for better financial outcomes.
Shellpoint Mortgage Servicing is my HELOC provider. It is a secondary heloc, top of my first mortgage mortgage with JP Morgan. Okay, so let me look them up real quick.
Shellpoint. Shellpoint Servicing. Welcome to Shellpoint. Let's see, HELOC provides. Is this it? Crohn, South Carolina. That's where they're located, shellpoint.
I have a feeling Shell, shellpoint is not a bank bank. Let me know if you're ever to come off mute.
Chrome. Hey, can you hear me?
Yeah.
Do you remember who you went to apply when you got the heloc? All right, so more than likely you have the wrong heloc. So meaning you, you have a heloc, but it's not at a bank where you can have a checking account.
Right?
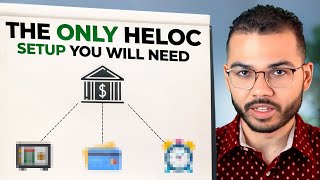
Because who do you, who do you bank with? Chase. Right. Okay, so here's our problem. So we have. And when did you get this heloc? How long ago? Okay, cool. So we don't have to stay married to that broker. And if we're serious about doing velocity banking and really making a change, then we're going to need to do our homework and make the switch. So our problem so far, we look at the velocity banking triangle. You've got income on one end, your line of credit on the other, debts, bills at the top. A proper velocity banking system. Over here, income, you have a checking account. So this implies I need to have a bank in order to do velocity banking properly and efficiently fully maximize, have to be working with a bank. So our first error is we're working with a broker, someone that did it for us.
Error.
So checking account has to be at the same bank as your line of credit. Same bank. Then, yeah, now that they're at the same bank, they can, they can communicate with each other. So I'm able to send money to my line of credit, I'm able to take money out of my line of credit. When I take money out of my line of credit, it pays bills and debts, right? So money goes in, money comes out, pays the debt off. That means the debt now sits in the line of credit at a lower cost of money. Right? You're essentially consolidating and then the cash flow flows back to your income. So now you got more cash flow to work with, which means what? More money gets to go inside the line of credit, which means what? Less interest is being paid. So you got this inter communication system being built. Whereas in your case, I have TD Bank, I have a broker and I have a HELOC somewhere with that broker. And then I have. So you got the line of credit that just. It's sitting somewhere. I don't know where. We'll find out. But there's no communication. And so I can't create a flow. So money is like. Money has to travel from here to the broker. Then I don't know, I guess the broker sticks it in the heloc. And then I got to reach out to the broker to move money out of the heloc. I guess it goes to Didi. And then TD will pay debt. So it's too much of this, like too many straight lines. We need a nice river flow of money. That's how our strategy will improve. So this is a simple, easy fix. TD bank offers home equity line of credit. So I could look up TD Bank. This doesn't mean that I should go with TD Bank. I'm just simply making a point. Point temporarily. You heard what I said, right? So are we in a rush? Let me ask that. No, of course not. Yeah, yeah, yeah. So. So what's going on is it's kind of like you're trying to. It sounds like you're pulling from two ends. Either I'm trying to get a HELOC or I'm trying to do a refinance.
You can't do both.
So it sounds like you're doing a refinance right now.
Correct.
So the first thing that needs to happen is the refinance, which has already occurred. I already applied for it and got approved.
Correct.
So I can't.
I can't do both.
Right.
That's.
That's about as simple as that. So I do the refinance, waiting for the close. I get that money. That money pays off debt. Now my credit will need time.
Right.
So are we in a rush? Let me ask that. No, of course not. Yeah, yeah, yeah. So. So what's going on is it's kind of like you're trying to. It sounds like you're pulling from two ends. Either I'm trying to get a HELOC or I'm trying to do a refinance.
You can't do both.
So it sounds like you're doing a refinance right now.
Correct.
So the first thing that needs to happen is the refinance, which has already occurred. I already applied for it and got approved.
Correct.
So I can't.
I can't do both.
Right.
That's about as simple as that. So I do the refinance, waiting for the close. I get that money. That money pays off debt. Now my credit will need Time to make those changes, make those reports. So I don't need to force velocity banking at this moment because you already did a refinance, you're using your credit to solve for something else. You can't have both. So you're going to have to settle the refinance, let that hit your credit, do the work that you intended to do. You stick to in the meantime, you stick to your payments. I wouldn't even try to use my heloc. I wouldn't try to consolidate any debt in there because you're not going to create any velocity with that. Going to have too many problems. You would simply go faster. More than likely by just directing after your refinance you pay off whatever debts, whatever money you're intending to use. I don't know if it's a split split between investing and paying off debt. Let's just say your intent is pay off debt with the cash out refinance. Once that settles. Now what I could do is the velocity banking pregame work, start building a relationship with a bank. TD bank is one option but I would want to look at the best home equity lines of credit whether I want a second or a first. So we look at the different options and then understanding that okay, I got a ding for applying with CMG too soon, got another credit hit with the cash out refinance. Got a lot of my DTI is high so I just need to do the pregame work to get my credit back up, DTI back down, utilization where it needs to be to obtain the best home equity line of credit. Then I'm going to be able to move forward efficiently, effectively. Does that make sense?